• Trade
  • Markets
  • Copy
  • Contests
  • 24/7
  • Calendar
  • Q&A
  • Chats
Screeners
SYMBOL
LAST
BID
ASK
HIGH
LOW
NET CHG.
%CHG.
SPREAD
SOURCE
SPX
S&P 500 Index
7722.71
7722.71
7722.71
7754.68
7700.52
+56.26
+ 0.73%
--
--
DJI
Dow Jones Industrial Average
51176.95
51176.95
51176.95
51382.87
50950.62
+250.39
+ 0.49%
--
--
IXIC
NASDAQ Composite Index
27190.85
27190.85
27190.85
27353.68
27112.24
+319.27
+ 1.19%
--
--
USDX
US Dollar Index
101.680
101.680
101.760
101.690
101.590
+0.060
+ 0.06%
--
--
EURUSD
Euro / US Dollar
1.12463
1.12463
1.12470
1.12608
1.12445
-0.00044
-0.04%
--
--
GBPUSD
Pound Sterling / US Dollar
1.32384
1.32384
1.32398
1.32494
1.32300
+0.00022
+ 0.02%
--
--
XAUUSD
Gold / US Dollar
4156.37
4156.37
4156.76
4158.10
4132.79
+14.43
+ 0.35%
--
--
WTI
Light Sweet Crude Oil
89.654
89.654
89.689
90.861
89.507
-0.669
-0.74%
--
--

Community Accounts

Signal Accounts
--
Profit Accounts
--
Loss Accounts
--
View More

Become a signal provider

Sell trading signals to earn additional income

View More

Guide to Copy Trading

Get started with ease and confidence

View More

Signal Accounts for Members

All Signal Accounts

Best Return
  • Best Return
  • Best P/L
  • Best MDD
Past 1W
  • Past 1W
  • Past 1M
  • Past 1Y

All Contests

  • All
  • Recommend
  • Stocks
  • Cryptocurrencies
  • Central Banks
  • Trump Updates
  • Featured News
Top News Only
Share

The UAE Attorney General Stated That The Co-pilot Involved In The Cockpit Altercation On The Dubai Airlines Plane Attempted A Terrorist Attack During Flight, Attacking The Captain With An Axe In An Attempt To Take Control Of The Aircraft

Share

Russian Defense Ministry: Russian Forces Struck A Cargo Ship In The Black Sea That Was Transporting Dual-use Supplies To The Ukrainian Army

Share

The Russian Ministry Of Defense Stated That Russian Forces Struck A Logistics Center In The Kyiv Region, Which Was Used To Store Supplies Needed By The Ukrainian Army

Share

Economist: Still Maintains The View That The Fed Will Hold Rates Steady In October And Raise Them In December

Share

The Mayor Of Kyiv Stated That The North Bridge Over The Nippur River Was Attacked During The Russian Airstrikes, And Emergency Services Are En Route To The Scene

Share

According To Axios: Trump's Senior Cabinet Members Gathered At Camp David For Hours On Friday To Discuss The War With Iran And The Next Steps In The Saudi-Houthi Conflict

Share

US President Trump Said He Would Send About $100 In Medicare Subsidies To More Than 20 Million Seniors

Share

Insider: Co-pilot Suspected Of Stabbing Captain On Flydubai Flight Admits Intent To “crash The Plane”

Share

Japanese Finance Minister Katsuya Okada: Japan Is Adjusting Its Communication Strategy To Counter The View That It Is Pursuing A Reflationary Policy

Share

Spokesperson Of The Ministry Of Commerce Answers Questions From The Press Regarding The Initiation Of An Anti-Dumping Investigation Into Imports Of P-Nitrotoluene Originating In The European Union

Share

Japanese Finance Minister Satsuki Katayama: The Japanese Government Has Limited Transparency Regarding The Composition Of Its Foreign Exchange Reserves

Share

Japanese Finance Minister Satsuki Katayama: Since The Joint Foreign Exchange Intervention, Foreign Exchange Trends Have Changed To Some Extent

Share

Japanese Finance Minister Satsuki Katayama: The United States And Japan Agree That It Is Very Important That Both Sides Remain Prepared To Take Decisive Action In Response To Foreign Exchange Fluctuations

Share

Vietnam's Q3 GDP Grew At An Annual Rate Of 9.95%, Up From The Previous Figure Of 8.39%

Share

Fed’s Hammack: Non-farm Payrolls Align With Recent Hiring Trends; Ample Time To Determine Policy Stance

Share

The UK Maritime Trade Organization Has Received Reports Of An Incident 4 Nautical Miles East Of Oman. The Captain Of An Oil Tanker Reported Being Attacked By An Unidentified Flying Object On His Port Side. All Crew Members Are Safe, And No Environmental Impact Has Been Reported

Share

The U.S. Coast Guard Said It Intercepted A Cargo Ship Carrying Fuel To Cuba

Share

Trump Stated That South Korea Would Face Higher Costs If It Withdraws From Its Investment In Alaska LNG Projects

Share

Pakistani Sources: Indian Border Forces Shot And Killed Two Pakistani Civilians At The Border

Share

According To Al Arabiyah TV, The Yemeni Military Claims To Have Attacked Houthi Weapons And Supply Vehicles En Route To Al-Wazi'iyah

TIME
ACT
FCST
PREV
IMPACT
U.S. Weekly Treasuries Held by Foreign Central Banks

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
South Korea CPI YoY (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
Japan Jobs to Applicants Ratio (Aug)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Tokyo Core CPI YoY (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Tokyo CPI YoY (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Unemployment Rate (Aug)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Tokyo CPI MoM (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Tokyo CPI MoM (Excl. Food & Energy) (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan Monetary Base YoY (SA) (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Italy Retail Sales MoM (SA) (Aug)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone HICP Prelim YoY (Sept)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Core CPI Prelim YoY (Sept)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Core CPI Prelim MoM (Sept)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Government Employment (Sept)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Unemployment Rate (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Nonfarm Payrolls (SA) (Sept)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Average Hourly Wage YoY (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Average Hourly Wage MoM (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. U6 Unemployment Rate (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Manufacturing Employment (SA) (Sept)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Labor Force Participation Rate (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Average Weekly Working Hours (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Private Nonfarm Payrolls (SA) (Sept)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Factory Orders MoM (Excl. Defense) (Aug)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Factory Orders MoM (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Factory Orders MoM (Excl. Transport) (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Weekly Total Oil Rig Count

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
U.S. Weekly Total Rig Count

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
Australia has begun observing Daylight Saving Time, meaning its financial market trading hours and economic data release times will be one hour earlier than Standard Time.
Australia Services PMI Prelim (Sept)

A:--

F: --

P: --

AUDUSD
  • AUDUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Japan IHS Markit Composite PMI (Sept)

--

F: --

P: --

Japan IHS Markit Services PMI (Sept)

--

F: --

P: --

Saudi Arabia IHS Markit Composite PMI (Sept)

--

F: --

P: --

Japan Household Consumer Confidence Index (Sept)

--

F: --

P: --

Russia IHS Markit Services PMI (Sept)

--

F: --

P: --

Turkey CPI YoY (Sept)

--

F: --

P: --

Turkey PPI YoY (Sept)

--

F: --

P: --

South Africa IHS Markit Composite PMI (SA) (Sept)

--

F: --

P: --

Italy Composite PMI (Sept)

--

F: --

P: --

Italy Services PMI (SA) (Sept)

--

F: --

P: --

Germany Composite PMI Final (SA) (Sept)

--

F: --

P: --

Euro Zone Services PMI Final (Sept)

--

F: --

P: --

Euro Zone Composite PMI Final (Sept)

--

F: --

P: --

ECB Chief Economist Lane Speaks
Euro Zone Sentix Investor Confidence Index (Oct)

--

F: --

P: --

U.K. Official Reserves Changes (Sept)

--

F: --

P: --

U.K. Services PMI Prelim (Sept)

--

F: --

P: --

U.K. Composite PMI Prelim (Sept)

--

F: --

P: --

Euro Zone PPI MoM (Aug)

--

F: --

P: --

Euro Zone PPI YoY (Aug)

--

F: --

P: --

Canada National Economic Confidence Index

--

F: --

P: --

Brazil IHS Markit Services PMI (Sept)

--

F: --

P: --

Brazil IHS Markit Composite PMI (Sept)

--

F: --

P: --

U.S. IHS Markit Composite PMI Final (Sept)

--

F: --

P: --

U.S. IHS Markit Services PMI Final (Sept)

--

F: --

P: --

U.S. ISM Non-Manufacturing Inventories Index (Sept)

--

F: --

P: --

U.S. ISM Non-Manufacturing New Orders Index (Sept)

--

F: --

P: --

U.S. ISM Non-Manufacturing Employment Index (Sept)

--

F: --

P: --

U.S. ISM Non-Manufacturing Price Index (Sept)

--

F: --

P: --

U.S. Conference Board Employment Trends Index (SA) (Sept)

--

F: --

P: --

U.S. ISM Non-Manufacturing PMI (Sept)

--

F: --

P: --

Q&A with Experts
    • All
    • Chatrooms
    • Groups
    • Friends
    sanjeev flag
    sanjeev flag
    no sell in gold
    sanjeev flag
    my new mom not to be seen with her speculation. busy on with my old father or what hahaha
    sanjeev flag
    hey mom tgt of gold. give four plate speculation with treat guaranteed one
    sanjeev flag
    Areeba Mini❣️❣️
    Your father is an owl, and you're the son of an owl. 🤣 hahahaha
    @Areeba Mini❣️❣️ how many night did it take you to find out that my father is an owl. was he not able to handle well in dark room hahaha.
    sanjeev flag
    when everyone else will start giving there analysis then my mom would start flooding group with her third grade sketching on chart hahaha
    sanjeev flag
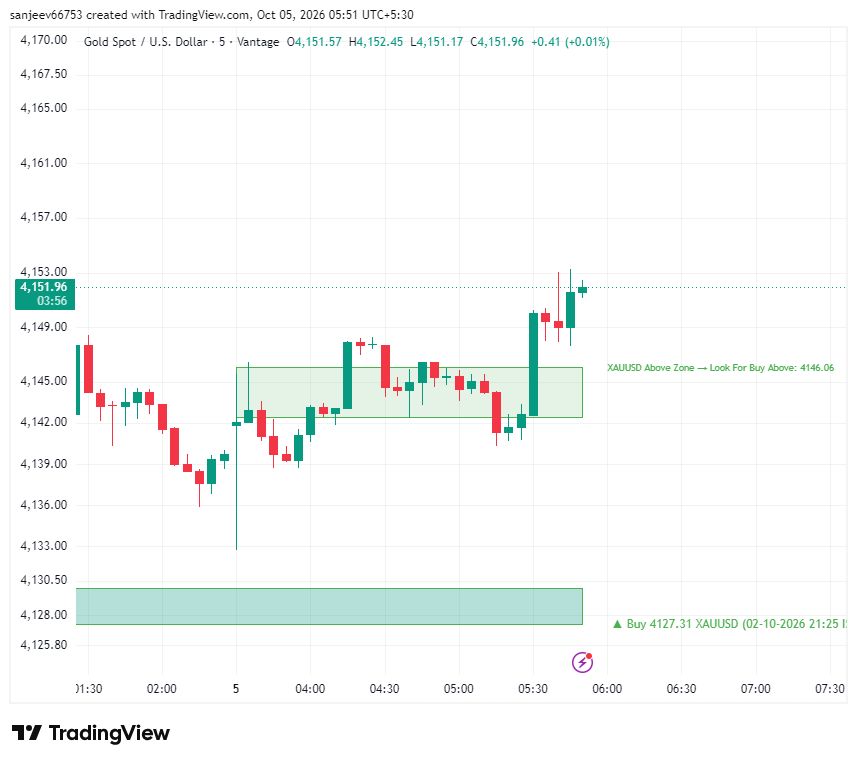
    i will take risk and hold longs . cmp 4142
    Đức Long flag
    buy xau
    sanjeev flag
    did you say any thing to me.
    sanjeev flag
    sanjeev
    i will take risk and hold longs . cmp 4142
    4148 again
    sanjeev flag
    no sell signal yet.the moment it comes i m out else will run
    sanjeev flag
    after crossing 93k moving towards 193k with extreme speed. four plate to 8 plate now
    sanjeev flag
    sanjeev flag
    no sell yet now 4153 but 4157 level to watch. may get sell signal there if not will ride the trend
    sanjeev flag
    signal is real time. not a single second lag. so immediate action either buy or sell.
    sanjeev flag
    sanjeev flag
    as expected near 4157 sell signal
    sanjeev flag
    now i am exiting all my lon gs untill buy comes
    Osaghae Cephas flag
    xauusd buyyyyyyyy😉🤣
    sanjeev flag
    buy bro i am out 4157 as my tgt
    Type here...
    Add Symbol or Code

      No matching data

      All
      Recommend
      Stocks
      Cryptocurrencies
      Central Banks
      Trump Updates
      Featured News
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint

      Search
      Products

      Charts Free Forever

      Chats Q&A with Experts
      Screeners Economic Calendar Data Tools
      Membership Features
      Data Warehouse Market Trends Institutional Data Policy Rates Macro

      Market Trends

      Market Sentiment Order Book Forex Correlations

      Top Indicators

      Charts Free Forever
      Markets

      News

      24/7 Analysis Education

      Latest Views

      Latest Update

      Signals

      Copy Rankings Latest Signals Become a signal provider AI Rating
      Contests
      Brokers

      Overview Brokers Assessment Rankings Regulators News Claims
      Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
      Q&A Complaint Scam Alert Videos Tips to Detect Scam
      More

      Business
      Events
      Careers About Us Advertising Help Center

      White Label

      Broker API

      Data API

      Web Plug-ins

      Affiliate Program

      Awards Institution Evaluation IB Seminar Salon Event Exhibition
      Vietnam Thailand Singapore Dubai
      Fans Party Investment Sharing Session
      FastBull Summit BrokersView Expo
      Recent Searches
        Top Searches
          Markets
          Analysis
          User
          24/7
          Economic Calendar
          Education
          Data
          • Names
          • Latest
          • Prev

          View All

          No data

          Scan to Download

          Faster Charts, Chat Faster!

          Download
          English
          • English
          • Español
          • العربية
          • Bahasa Indonesia
          • Bahasa Melayu
          • Tiếng Việt
          • ภาษาไทย
          • Français
          • Italiano
          • Türkçe
          • Русский язык
          • 简中
          • 繁中
          Open Account
          Search
          Products
          Charts Free Forever
          Markets
          News
          Signals

          Copy Rankings Latest Signals Become a signal provider AI Rating
          Contests
          Brokers

          Overview Brokers Assessment Rankings Regulators News Claims
          Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
          Q&A Complaint Scam Alert Videos Tips to Detect Scam
          More

          Business
          Events
          Careers About Us Advertising Help Center

          White Label

          Broker API

          Data API

          Web Plug-ins

          Affiliate Program

          Awards Institution Evaluation IB Seminar Salon Event Exhibition
          Vietnam Thailand Singapore Dubai
          Fans Party Investment Sharing Session
          FastBull Summit BrokersView Expo

          European Union Fiscal Rules: It's Already Time to Reform the Reform

          Bruegel

          Economic

          Political

          Summary:

          The fiscal framework is at risk of unravelling in the face of the heightened geopolitical tensions since Russia’s invasion of Ukraine. To prevent progressive erosion of the framework, the European Commission and EU countries should consider a focused ‘reform of the reform’ to realign it with its original goal: ensuring public debt sustainability based on a risk-based methodology with a limited role for rigid numerical targets.

          European Union Fiscal Rules: It's Already Time to Reform the Reform

          The European Union’s fiscal framework – a set of rules intended to ensure countries keep their debts manageable – was most recently reformed in April 20241. The reform followed an unprecedented spell of de-facto suspension of the fiscal rules starting in 2020, when countries were given virtually unlimited fiscal leeway to respond to the coronavirus pandemic and subsequently to the energy crisis triggered by the war in Ukraine.
          Now, little more than one year on from the reform, the fiscal framework is at risk of unravelling in the face of the heightened geopolitical tensions since Russia’s invasion of Ukraine. To prevent progressive erosion of the framework, the European Commission and EU countries should consider a focused ‘reform of the reform’ to realign it with its original goal: ensuring public debt sustainability based on a risk-based methodology with a limited role for rigid numerical targets.
          Risks to the April 2024 reform have arisen in particular for two reasons:
          First, activation has been permitted of the ‘national escape clause’ of the Stability and Growth Pact (SGP – the collective term for the EU fiscal framework legislation)2. The activation of the national escape clause, which temporarily eases the fiscal rules, is to allow countries to incur extra defence-related deficit spending (European Commission, 2025). Countries already submitted plans in the autumn of 2024 showing how they would put their spending into sustainable territory over four or seven years; the national escape clause allows them to spend up to 1.5 percent of GDP more for a maximum of four years.
          However, activating an escape clause almost as soon as the new fiscal rules begin to apply raises the understandable concern that the rules might not be enforced at all in the next few years. In particular, there are reasons to expect that no new excessive deficit procedures (EDP – a corrective procedure overseen by the European Commission for countries spending beyond the agreed limits) will be opened3 or that existing procedures4 will be escalated (Pench, 2024, 2025). Remarkably, some of the countries with the highest debts, which are the main intended beneficiaries of the escape clause, have so far declined to take advantage of it – in particular France, Italy and Spain. This presumably reflects the perceived risk of falling into a ‘debt trap’ triggered by market reactions, irrespective of whether the rules allow temporary extra borrowing for rearmament.
          The second risk factor for the reformed EU fiscal rules is that Germany in March 2025 agreed at record speed a reform of its constitutional ‘debt brake’ fiscal rule, to permanently remove borrowing constraints for defence expenditure (above a 1 percent of GDP floor) and to allow for a one-off €500 billion extra budgetary fund for ‘additional’ infrastructure investment. The new German fiscal posture has been largely welcomed as boosting the economy and addressing neglected spending priorities, at both national and European level5, without risking adverse market reactions.
          Although the German move was dictated exclusively by domestic considerations, the Commission can also present it as a vindication of sorts of the national escape clause (Germany has a debt slightly in excess of the maximum of 60 percent of GDP required under the SGP). However, under plausible assumptions, implementing the new German fiscal rule would still run up against the EU fiscal rules, potentially, given Germany’s weight, with repercussions for the whole framework. In particular, extra deficit spending on defence would become problematic beyond the time limit set for the national escape clause. Even in the short term, the EU fiscal rules, which do not permit exemptions for spending on investment programmes, may obstruct deployment of Germany’s infrastructure fund (Steinbach and Zettelmeyer, 2025).
          Agreeing on the April 2024 reform of the EU fiscal framework was difficult and it is understandable that the Commission may wish to dismiss concerns about the future of the framework raised by these developments6. In particular, it may be tempted to accommodate the new German posture on fiscal policy – in other words, papering over possible violations of the EU fiscal rules. Allowing Germany to fudge the EU rules to achieve domestic objectives is unlikely to raise strong objections in the rest of the EU, given that an expansionary German fiscal stance would help lift growth across the continent. However, this would compound the doubts on the working of the new fiscal framework raised by the early activation of the national escape clause. In particular, it would rekindle long-standing preoccupations with ‘equal treatment’, bearing in mind that Germany reformed its fiscal rules without any consultation with the EU.

          Going back to make it better

          Rather than contemplating an early withering of the new EU fiscal framework, the Commission could respond proactively by proposing a surgical ‘reform of the reform’. It could even bring the framework closer to the Commission’s original design (European Commission, 2022a), which was partially overturned in the legislative process because of concern that the consensus necessary for its adoption would not be reached. That worry reflected the traditional German fixation on strict numerical deficit and debt targets. Germany’s own fiscal overhaul thus offers an unexpected opportunity to refocus the EU fiscal framework reform on its original aim, allowing in the process the use of fiscal space where it is available and the elimination of rules devoid of economic justification.
          The EU reform’s original aim can be described as the de-risking of national debts, ie the eventual removal of situations in which a country’s public debt poses a high sustainability risk. Rather than requiring debt to hit a target by a certain time or to diminish by a certain amount, the concept of sustainability was long operationalised by the Commission through the development of a specific methodology for assessing medium-term sustainability risk (European Commission, 2023). This combines countries’ projected debt levels with their projected trajectories, suitably stress-tested, to reach an overall conclusion on whether debt presents a high sustainability risk.
          With some approximation, the criteria can be described as follows: for countries with debt projected to stay at very high levels – in excess of 90 percent of GDP – the projected debt trajectory should be declining continuously, with a high probability that debt will not rise. For countries with debt projected to stay between 60 percent and 90 percent of GDP, the debt trajectory may rise temporarily, provided that there is a high probability debt will be trending downwards before the end of the projection period. Meanwhile, countries with debt projected to stay below 60 percent of GDP are not deemed high sustainability risks.
          The Commission’s sustainability-risk assessment methodology continues to provide the main foundation of the new EU fiscal rules, specifically the requirement for countries’ medium-term adjustment plans to show that debt is on a “plausibly downward” trajectory or will stay “at prudent levels” (Pench, 2023). However, the translation of the methodology into legal requirements accentuated existing rigidities and missed opportunities for clarification. In particular, the April 2024 reform inherited a cumbersome approach to stress testing the baseline debt trajectory; it effectively obliterated any difference between countries with debts projected to stay above 90 percent of GDP and those in the 60 percent to 90 percent range; and it did not factor in the possibility that the debt trajectory may be affected temporarily by time-limited spending programmes, eg on infrastructure.
          The reform also introduced unrelated numerical debt and deficit requirements: the so-called ‘debt sustainability safeguard’ and the ‘deficit resilience safeguard’. The latter, requiring countries to eventually reach an arbitrarily set deficit level, results in an unrealistic tightening of the adjustment requirement for countries with very high debts. The former, requiring a minimum pace of debt reduction already during the adjustment period, while the debt exceeds 60 percent of GDP, paradoxically turns out to be potentially penalising not for the countries with very high debts, but for those in the middle range.

          ‘Surgical’ reform

          A targeted revision of the reform to address critical weaknesses would be relatively easy.
          First, the risk-based requirements should be reviewed to make them less rigid for countries projected to stay in the middle range of debt (60-90 percent of GDP). For those countries, the requirement could be that debt stabilisation should occur with high probability before the end of the sustainability assessment horizon (ie the period including the four to seven-year medium-term adjustment plan and the subsequent 10-year ‘unchanged policy’ projection)7. In turn, the definition of ‘unchanged policy’ should be tweaked to allow for self-reverting spending programmes, such as the German infrastructure fund, with opportune safeguards against their extension.
          Second, the debt sustainability safeguard and the deficit resilience safeguard should be abolished to restore the reform’s underlying sustainability-risk-centred approach. Eliminating the numerical safeguards would be necessary to allow for limited increases in the debt ratios of countries in the middle range, and would avoid disproportionate penalisation of countries with very high debts.
          This solution would be preferable to simply raising the Treaty-based debt threshold from 60 percent of GDP to 90 percent (as suggested by eg Steinbach and Zettelmeyer, 2025). Besides the symbolic value attached to the 60 percent threshold, simply replacing it with 90 percent after Germany announced plans to increase its debt would risk creating the impression that the target is being shifted to please the EU’s dominant player.

          Impact on Germany

          Admittedly, such a surgical reform of the reform would fall short of allowing Germany to exploit all the room for increasing debt implied by its new domestic rules (as estimated by Zettelmeyer, 2025). Germany would still be required to stabilise its debt below 90 percent of GDP and eventually bring it further down towards 60 percent (barring new expenditure programmes). This, however, would confirm the logic of the proposed new reform as not simply accommodating shifting German priorities. It would also reinforce the message that borrowing to finance an expenditure increase, such as for defence, which is expected to be permanent, while politically expedient, is not an economically desirable policy.
          The unwillingness shown by the highest-debt countries to profit from the national escape clause suggests that these countries should not be hostile to greater differentiation within the group of countries with debts above 60 percent of GDP. As to the elimination of the two safeguards, the apparent dismissal of these in the application of the national escape clause by the Commission suggests that they are already implicitly recognised as a source of unnecessary and damaging complexity.
          The surgical reform could be done through an amendment to Regulation (EU) 2024/1263 of April 2024 (the regulation traditionally referred to as the ‘preventive arm’ of the SGP). This, unlike replacement of the 60 percent of GDP debt threshold, would not need unanimity of EU countries.
          Further specification of the risk-based requirements should be done by reference to the Commission methodology (under the control of an ad-hoc working group of EU countries, Commission and European Central Bank representatives), as it is already the case with the current rules.
          The methodology should be reviewed to ensure full consistency with the proposed definition of the risk-based requirements and, more generally, to deal with critical issues that the April 2024 reform left unaddressed. In particular, the specifications for the construction of the ‘fan chart’, illustrating the range of possible outcomes around the central adjustment scenario and their probabilities, could be reviewed including in terms of statistical technique, period covered and the operationalisation of the requirement for debt stabilisation with high probability.

          来源:bruegel

          To stay updated on all economic events of today, please check out our Economic calendar
          Risk Warnings and Disclaimers
          You understand and acknowledge that there is a high degree of risk involved in trading. Following any strategies or investment methods may lead to potential losses. The content on the site is provided by our contributors and analysts for information purposes only. You are solely responsible for determining whether any trading assets, securities, strategy, or any other product is suitable for investing based on your own investment objectives and financial situation.
          Add to Favorites
          Share
          FastBull
          Copyright © 2026 FastBull Ltd

          728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG

          TelegramInstagramTwitterfacebooklinkedin
          App Store Google Play Android Windows
          Products
          Charts

          Chats

          Q&A with Experts
          Screeners
          Economic Calendar
          Data
          Tools
          Membership
          Features
          Function
          Markets
          Copy Trading
          Latest Signals
          Contests
          24/7
          Analysis
          Education
          Company
          Careers
          About Us
          Contact Us
          Advertising
          Download FastBull
          Help Center
          Feedback
          User Agreement
          Privacy Policy
          Personal Information Protection Statement
          Business

          White Label

          Broker API

          Data API

          Web Plug-ins

          Poster Maker

          Affiliate Program

          Risk Disclosure

          The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.

          No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.

          Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.

          Not Logged In

          Log in to access more features

          Connect Broker
          Become a signal provider
          Help Center
          Customer Service
          Dark Mode
          Price Up/Down Colors

          Log In

          Sign Up

          Position
          Layout
          Fullscreen
          Default to Chart
          The chart page opens by default when you visit fastbull.com