


- USDX
- XAUUSD
- XAGUSD
- WTI


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev












Risk-off sentiment intensified in US tech sector overnight, with another down day in the NASDAQ.
Risk-off sentiment intensified in US tech sector overnight, with another down day in the NASDAQ. The move reflected growing unease rather than a single catalyst, as investors continue to reassess the implications of artificial intelligence for earnings, valuations, and capital discipline. That weakness carried into Asia, where Japanese and Korean equities saw steep declines.
So far, traditional and non-tech stocks have shown greater resilience. That divergence supports the narrative that markets are undergoing sector rotation rather than a full-blown risk-off episode. However, whether that insulation can hold if tech pressure persists remains an open question.
Several overlapping themes are driving the current reassessment. The first is growing concern that AI represents a competitive threat to software companies rather than a pure growth catalyst. Software firms long valued for sticky subscriptions and predictable renewals are now under scrutiny. Investors are questioning whether AI-driven automation could compress pricing, reduce switching costs, and lower barriers to entry for new competitors.
A second theme is the rapidly escalating cost of AI investment. Alphabet reported solid results, but its projected capital expenditure of USD 175–185 billion for this year came in well above expectations and rattled investors. The concern is not isolated. Alphabet and its Big Tech peers are expected to collectively spend more than USD 500 billion on AI this year. The scale of spending is forcing investors to question near-term returns. With monetization timelines uncertain, aggressive outlays are increasingly seen as a drag on free cash flow rather than a guarantee of future dominance.
A third pressure point came from the semiconductor space. AMD suffered its worst single-day decline since 2017 after delivering a lackluster forecast. Expectations had been high for a stronger outlook driven by AI demand and data center expansion. The reaction highlighted that even the chip subsector is not immune to broader market sensitivity. AI exposure alone is no longer sufficient to insulate companies from disappointment if guidance falls short.
In FX markets, the shift in sentiment has favored defensive currencies. Both Dollar and Yen found support in Asian session, while Aussie and kiwi softened. Euro and Sterling were mixed as markets awaited policy decisions from the ECB and the BOE.
Despite the daily moves, weekly performance still shows a different ranking. Aussie remains the strongest currency so far this week, followed by Dollar and Sterling. Yen continues to lag at the bottom, trailed by Swiss Franc and Kiwi, while Euro and Loonie sit in the middle.
In Asia, at the time of writing, Nikkei is down -0.86%. Hong Kong HSI is down -0.95%. China Shanghai SSE is down -0.83%. Singapore Strait Times is down -0.27%. Japan 10-year JGB yield is down -0.012 at 2.239. Overnight, DOW rose 0.53%. S&P 500 fell -0.51%. NASDAQ fell -1.51%. 10-year yield rose 0.001 to 2.750.
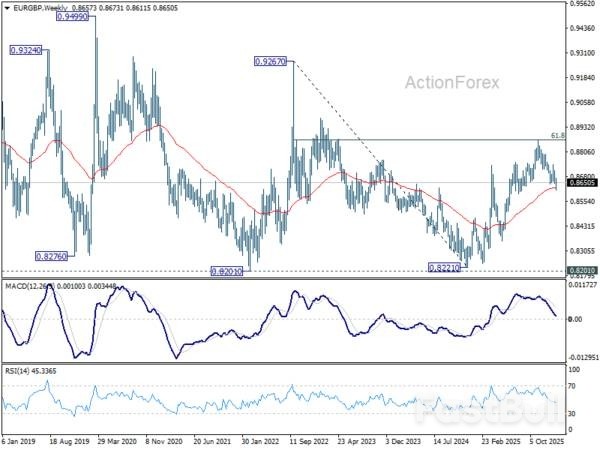
EUR/GBP is sitting at a key technical and macro junction around 0.86 level as markets head into rate decisions from the ECB and the BoE. While neither meeting is expected to deliver an immediate policy shift, both carry important signals that could shape expectations and positioning in the cross.
Both central banks are widely expected to stand pat. The ECB is set to keep the deposit rate unchanged at 2.00%, while the BoE is expected to leave Bank Rate steady at 3.75%. With these results fully priced in, the focus is firmly on guidance rather than the decisions themselves.
For the ECB, President Christine Lagarde is likely to repeat that policy is in a "good place." There is little appetite within the Governing Council to debate changes to borrowing costs in the near term, reinforcing expectations of an extended pause.
Near-term inflation has softened, slipping to just 1.7% in January and potentially easing further in coming months. However, that downside surprise has not meaningfully altered the ECB's broader inflation outlook. One reason is energy. The recent rebound in oil prices, if sustained, would offset much of the disinflationary impact from Euro strength. That reduces any urgency for the ECB to respond to near-term CPI weakness.
Inflation expectations also remain a concern. The ECB's latest Consumer Expectations Survey showed five-year inflation expectations rising to 2.4% in December, the highest since the survey began. Shorter- and medium-term expectations also edged higher, supporting the ECB's view that inflation could reaccelerate.
As a result, the ECB appears comfortable with a prolonged pause, with the next move still more likely to be a hike than a cut. One key focus today will be whether Lagarde references recent Dollar weakness and the EUR/USD exchange rate, particularly around the recently tested 1.20 level.
In the UK, the policy picture is more fractured. The BoE's December rate cut passed by a narrow 5–4 vote, underscoring deep divisions within the Monetary Policy Committee. UK inflation remains elevated, with December's 3.4% reading the highest among G7 economies. While inflation is expected to move back toward the 2% target, some policymakers remain concerned that underlying pressures are still too strong.
Market pricing reflects that caution. Investors largely expect no move until at least April, and possibly not until July, a much slower pace of easing than seen in 2025. As usual, the MPC vote split will be closely watched for clues on the balance between hawks and doves.
Technically, EUR/GBP is testing a critical support cluster near 0.86. The favored view is that the rebound from the 0.8221 (2024 low was corrective) and may have completed at 0.8863 after failing near 61.8% retracement of 0.9267 (2022 high) to 0.8221 (2024 low) at 0.8867. Decisive break below the 0.8631 support zone (38.2% retracement of 0.8221 to 0.8663 at 0.8618, and 55 W EMA at 0.8625) would confirm bearish reversal.
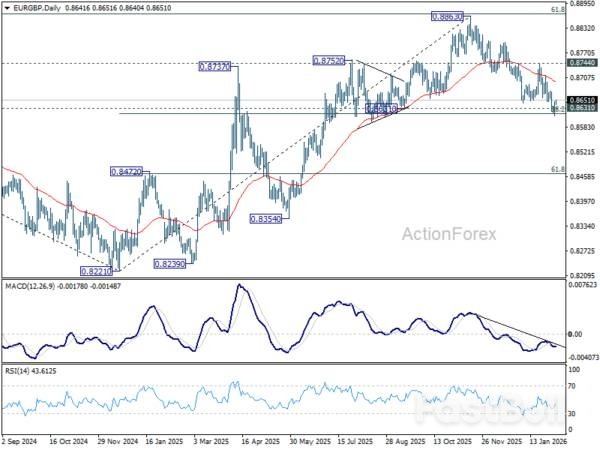
However, downside confirmation is still lacking. If EUR/GBP finds firm support around current levels and stages a convincing rebound, a break above 0.8744 resistance would suggest that the fall from 0.8863 was merely a corrective pullback. In that scenario, the rise from 0.8221 would likely be resuming, with scope to extend toward through 0.8863 towards 0.9267 in the medium term.
Fed Governor Lisa Cook said risks are currently "tilted toward higher inflation," explaining why she supported the FOMC's decision to hold interest rates steady at last week's meeting.
Cook noted in a speech that understanding why inflation leveled off in 2025 requires looking beneath the headline. Disinflation has continued in housing services, while non-housing services inflation has also eased, consistent with a labor market that is no longer as tight as before.
The area of concern, however, lies in "core good prices". Cook highlighted a notable pickup in goods inflation, largely driven by last year's tariff increases on a wide range of imported products.
While anchored inflation expectations suggest tariff effects should amount to a "one-time rise" in the price level, Cook stressed that uncertainty remains high. The "future direction of tariff policy is unclear", and it is uncertain how quickly price increases will fully pass through or whether they risk influencing expectations.
Until clearer evidence emerges that inflation is moving sustainably back toward target, Cook said inflation is "where my focus will be", barring unexpected changes in the labor market.
Daily Pivots: (S1) 0.6966; (P) 0.7004; (R1) 0.7037;
AUD/USD dips mildly today as range trading continues and intraday bias stays neutral. Further rise is still in favor. On the upside, break of 0.7093 will extend larger up trend to 100% projection of 0.5913 to 0.6706 from 0.6420 at 0.7213 next. However, break of 0.6907 will bring lengthier consolidations before rally resumption. Deeper pullback would then be seen to 38.2% retracement of 0.6420 to 0.7093 at 0.6836.
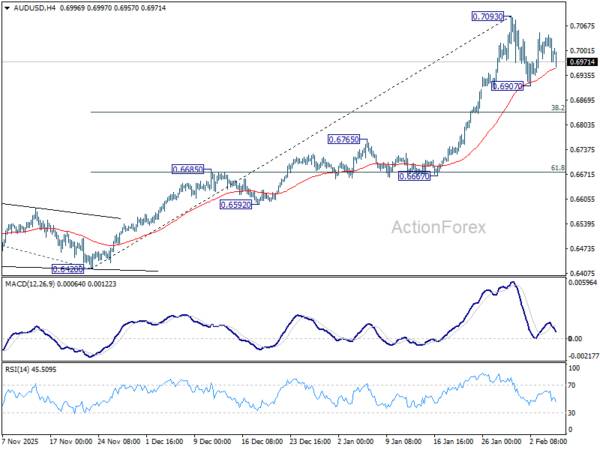
In the bigger picture, current development argues that rise from 0.5913 (2024 low) is reversing whole down trend from 0.8006 (2021 high). Further rally should be seen to 61.8% retracement of 0.8006 to 0.5913 at 0.7206. This will remain the favored case as long as 0.6706 resistance turned support holds, even in case of deep pullback.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


