• Trade
  • Markets
  • Copy
  • Contests
  • 24/7
  • Calendar
  • Q&A
  • Chats
Screeners
SYMBOL
LAST
BID
ASK
HIGH
LOW
NET CHG.
%CHG.
SPREAD
SOURCE
SPX
S&P 500 Index
7700.26
7700.26
7700.26
7732.21
7690.94
-43.72
-0.56%
--
--
DJI
Dow Jones Industrial Average
52191.03
52191.03
52191.03
52405.88
52086.13
-284.07
-0.54%
--
--
IXIC
NASDAQ Composite Index
26110.24
26110.24
26110.24
26286.46
26053.16
-439.60
-1.66%
--
--
USDX
US Dollar Index
101.820
101.820
101.900
102.270
101.755
-0.138
-0.14%
--
--
EURUSD
Euro / US Dollar
1.11644
1.11644
1.11652
1.11733
1.11042
+0.00122
+ 0.11%
--
--
GBPUSD
Pound Sterling / US Dollar
1.33641
1.33641
1.33652
1.33796
1.32955
+0.00399
+ 0.30%
--
--
XAUUSD
Gold / US Dollar
4005.57
4005.57
4005.98
4068.79
4005.55
-61.67
-1.52%
--
--
WTI
Light Sweet Crude Oil
101.148
101.148
101.178
101.530
99.081
-0.057
-0.06%
--
--

Community Accounts

Signal Accounts
--
Profit Accounts
--
Loss Accounts
--
View More

Become a signal provider

Sell trading signals to earn additional income

View More

Guide to Copy Trading

Get started with ease and confidence

View More

Signal Accounts for Members

All Signal Accounts

Best Return
  • Best Return
  • Best P/L
  • Best MDD
Past 1W
  • Past 1W
  • Past 1M
  • Past 1Y

All Contests

  • All
  • Recommend
  • Stocks
  • Cryptocurrencies
  • Central Banks
  • Trump Updates
  • Featured News
Top News Only
Share

US President Trump Has Proposed Renaming The Strait Of Hormuz To The Trump Strait

Share

Trump: The United States Is Working With Venezuela To Extract Millions Of Barrels Of Oil To Supply The United States

Share

US President Trump Reiterated His Intention To Rename The Gulf Of Mexico To The United States Gulf

Share

US President Trump: Canada Has Recently Been Friendly To The United States

Share

Venezuelan Opposition Leader Machado: Those Who Assist In The Transition Process Will Need To Be Guaranteed

Share

Venezuelan Opposition Leader Machado: The Next Government Must Launch A Truth Commission. There Must Also Be A Transitional Judicial Process

Share

Venezuelan Opposition Leader Machado: The United States Will Play A Role In Venezuela In The Long Term

Share

The UK Maritime Trade Operations Office (MTO) Has Reported That The Company’s Security Officer Has Informed The MTO That Its Tanker Was Hit By An Unidentified Shell While Completing Its Transit Through The Strait Of Hormuz

Share

Fitch Ratings: Inflation Outpaces Wage Growth, Putting Eurozone Consumer Resilience To The Test

Share

LME Tin Futures Closed Down $1,020

Share

LME Copper Futures Closed Down $121 At $14,356 Per Tonne. LME Aluminum Futures Closed Up $6 At $3,078 Per Tonne. LME Zinc Futures Closed Up $20 At $3,883 Per Tonne. LME Lead Futures Closed Up $16 At $1,915 Per Tonne. LME Nickel Futures Closed Down $69 At $15,536 Per Tonne. LME Tin Futures Closed Down $1,020 At $49,697 Per Tonne. LME Cobalt Futures Closed Unchanged At $33,510 Per Tonne

Share

New York Gold Futures Fell Below $4,020 Per Ounce, Down 0.78% On The Day

Share

Spot Gold Fell Below $4,010 Per Ounce, Down 1.41% On The Day

Share

Trump: The United States Had To Strike Iran To Prevent It From Acquiring Nuclear Weapons

Share

US President Trump Reiterated That The Iran Conflict Will End Soon

Share

Venezuelan Opposition Leader Machado: An Orderly Transition In Venezuela Is In The Interest Of The United States And The Entire Western Hemisphere

Share

Russian President Putin: We Do Not Want A Situation Like The One In The Strait Of Hormuz To Happen In The Baltic Sea

Share

Russian President Putin: No Country In The World Other Than Russia Has The Capability To Produce Small Nuclear Power Plants

Share

Venezuelan Opposition Leader Machado: Relations With The United States Are Based On Mutual Respect

Share

Russian President Putin: If Things Go Too Far, There Will Be No Winners

TIME
ACT
FCST
PREV
IMPACT
U.K. Mortgage Lending (Sept)

A:--

F: --

P: --
GBPUSD
  • GBPUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Consumer Inflation Expectations (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Selling Price Expectations (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Industrial Climate Index (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Consumer Confidence Index Final (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Economic Sentiment Indicator (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Services Sentiment Index (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Italy 5-Year BTP Bond Auction Avg. Yield

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Italy 10-Year BTP Bond Auction Avg. Yield

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Initial Jobless Claims 4-Week Avg. (SA)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Continued Jobless Claims (SA)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Real Personal Consumption Expenditures MoM (Sept)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. PCE Price Index MoM (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Personal Income MoM (Sept)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. PCE Price Index YoY (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. PCE Price Index Prelim QoQ (SA) (Q3)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Core PCE Price Index MoM (Sept)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. GDP Deflator Prelim QoQ (SA) (Q3)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Real Personal Consumption Expenditures Prelim QoQ (Q3)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Core PCE Price Index Annualized QoQ Prelim (SA) (Q3)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Personal Outlays MoM (SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Real GDP Annualized QoQ Prelim (SA) (Q3)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Initial Jobless Claims (SA)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Core PCE Price Index YoY (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone ECB Deposit Rate

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone ECB Main Refinancing Rate

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone ECB Marginal Lending Rate

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
ECB Monetary Policy Statement
ECB Press Conference
U.S. EIA Weekly Natural Gas Stocks Change

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
U.S. Dallas Fed PCE Price Index YoY (Sept)

--

F: --

P: --

Brazil CAGED Net Payroll Jobs (Sept)

--

F: --

P: --

U.S. Weekly Treasuries Held by Foreign Central Banks

--

F: --

P: --

South Korea Retail Sales MoM (Sept)

--

F: --

P: --

South Korea Services Output MoM (Sept)

--

F: --

P: --

South Korea Industrial Output MoM (SA) (Sept)

--

F: --

P: --

Japan Tokyo CPI MoM (Oct)

--

F: --

P: --

Japan Jobs to Applicants Ratio (Sept)

--

F: --

P: --

Japan Tokyo CPI YoY (Oct)

--

F: --

P: --

Japan Tokyo Core CPI YoY (Oct)

--

F: --

P: --

Japan Unemployment Rate (Sept)

--

F: --

P: --

Japan Tokyo CPI MoM (Excl. Food & Energy) (Oct)

--

F: --

P: --

Japan Retail Sales MoM (SA) (Sept)

--

F: --

P: --
Japan Retail Sales YoY (Sept)

--

F: --

P: --
Japan Industrial Output Prelim MoM (Sept)

--

F: --

P: --

Japan Industrial Output Prelim YoY (Sept)

--

F: --

P: --

Japan Industrial Inventory MoM (Sept)

--

F: --

P: --

Japan Retail Sales (Sept)

--

F: --

P: --

Australia PPI YoY (Q3)

--

F: --

P: --

Australia PPI QoQ (Q3)

--

F: --

P: --

Japan Benchmark Interest Rate

--

F: --

P: --

BOJ Monetary Policy Statement
Japan Construction Orders YoY (Sept)

--

F: --

P: --

Japan New Housing Starts YoY (Sept)

--

F: --

P: --

France GDP Prelim YoY (SA) (Q3)

--

F: --

P: --

BOJ Press Conference
Turkey Economic Sentiment Indicator (Oct)

--

F: --

P: --

U.K. Nationwide House Price Index MoM (Oct)

--

F: --

P: --

U.K. Nationwide House Price Index YoY (Oct)

--

F: --

P: --

France PPI MoM (Sept)

--

F: --

P: --

Germany Unemployment Rate (SA) (Oct)

--

F: --

P: --

Q&A with Experts
    • All
    • Chatrooms
    • Groups
    • Friends
    SHIZEN flag
    EuroTrader
    @SHIZENokay mate, that's good, can you remind me what we were talking about e
    @EuroTraderCan you show me your EU chart first let me see the update
    EuroTrader flag
    SHIZEN
    @EuroTraderi can't remember exactly but we were talking about risk
    @SHIZENOkay that's a good one mate, so tell me what do you wish to know about risk?
    EuroTrader flag
    SHIZEN
    @EuroTraderCan you show me your EU chart first let me see the update
    @SHIZENAlright mate, hold on let me get you my chart on what I'm seeing over there
    SHIZEN flag
    EuroTrader
    @SHIZENAlright mate, hold on let me get you my chart on what I'm seeing over there
    @EuroTraderokay I'm waiting
    SHIZEN flag
    EuroTrader
    @SHIZENOkay that's a good one mate, so tell me what do you wish to know about risk?
    @EuroTraderwhich one so better, a fixed or flexible risk in the market?
    EuroTrader flag
    SHIZEN
    @EuroTraderwhich one so better, a fixed or flexible risk in the market?
    @SHIZENWell it depends on what you wish to attend, but i prefer the flexible risk
    EuroTrader flag
    EuroTrader flag
    EuroTrader
    @SHIZENWell it depends on what you wish to attend, but i prefer the flexible risk
    @SHIZENThough you can have an average RR while doing that
    EuroTrader flag
    EuroTrader
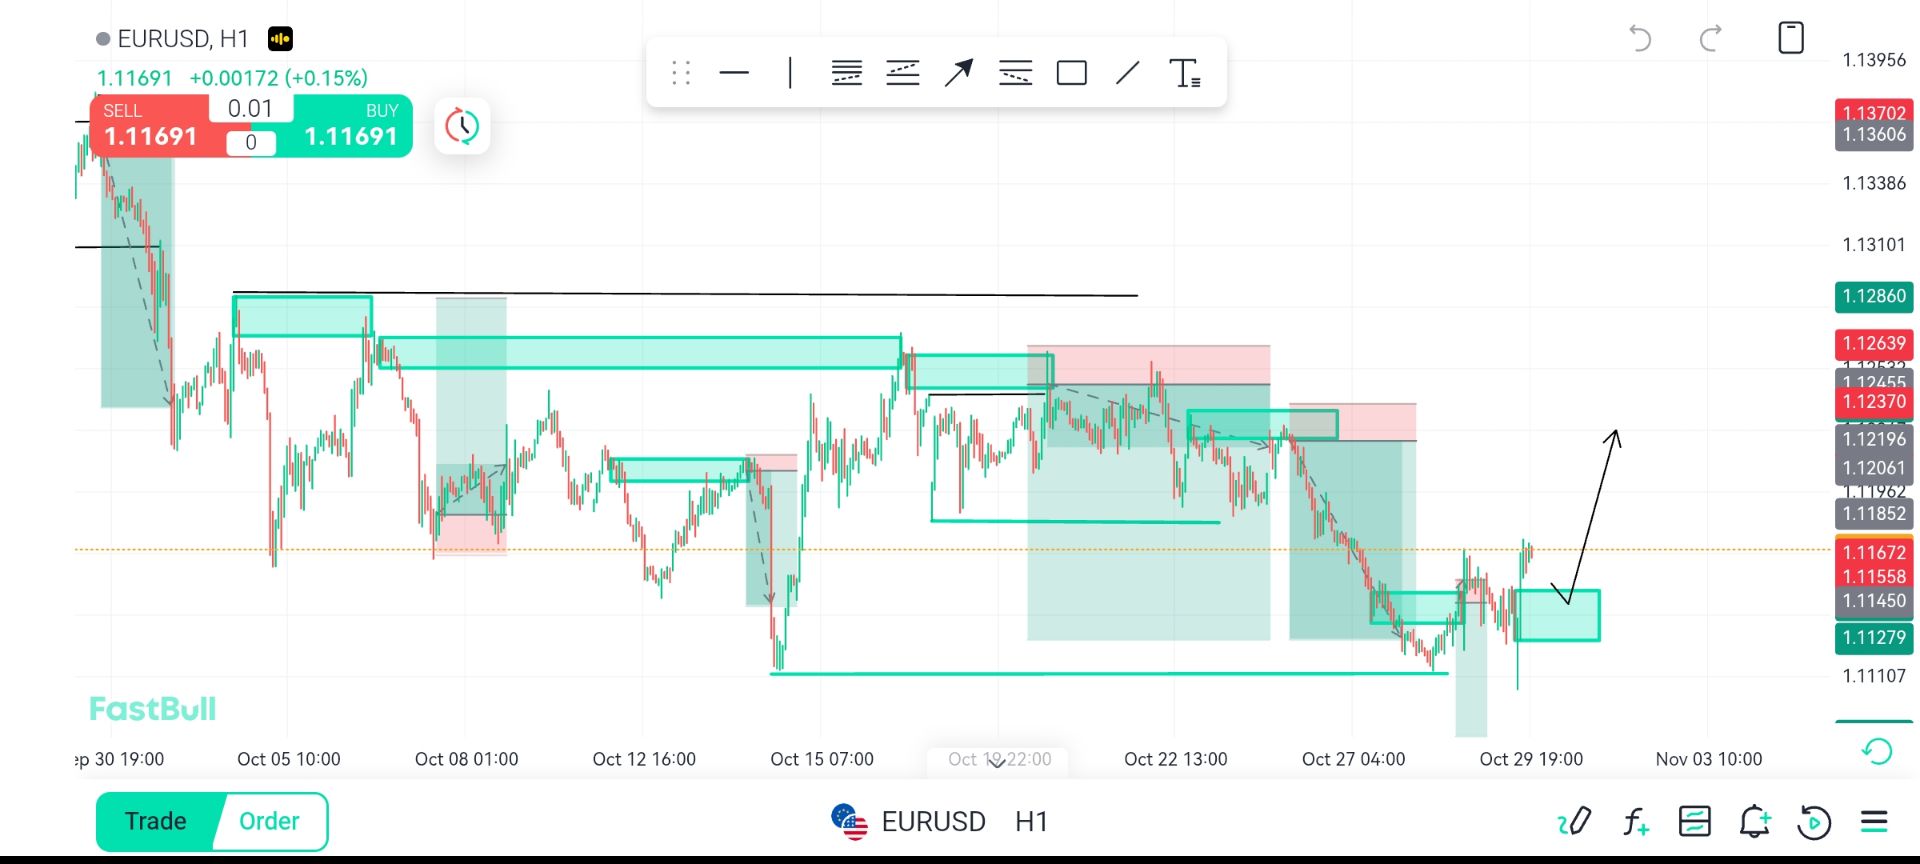
    @SHIZENHere mate, this is what's happening on the EU market at the moment
    SHIZEN flag
    EuroTrader
    @SHIZENThough you can have an average RR while doing that
    @EuroTraderokay
    SHIZEN flag
    EuroTrader
    @SHIZENWell it depends on what you wish to attend, but i prefer the flexible risk
    @EuroTraderwhy do you prefer the flexible risk sir?
    EuroTrader flag
    SHIZEN
    @EuroTraderwhy do you prefer the flexible risk sir?
    @SHIZENIt's simple mate, all the set ups you will see in the market won't be the same
    EuroTrader flag
    EuroTrader
    @SHIZENIt's simple mate, all the set ups you will see in the market won't be the same
    @SHIZENThat's are some with a higher probability than others, some traders call it A+
    EuroTrader flag
    EuroTrader
    @SHIZENThat's are some with a higher probability than others, some traders call it A+
    @SHIZENSo when you see such set up, you shouldn't be risking little because you are doing a fixed RR
    SHIZEN flag
    EuroTrader
    @SHIZENHere mate, this is what's happening on the EU market at the moment
    @EuroTraderokay thanks a lot for this, EU is still shooting up
    SHIZEN flag
    EuroTrader
    @SHIZENThat's are some with a higher probability than others, some traders call it A+
    @EuroTraderyesh okay this is valid sir.
    SHIZEN flag
    EuroTrader
    @SHIZENThat's are some with a higher probability than others, some traders call it A+
    @EuroTraderSo howany percentage do you think the trade could add to such a set up
    EuroTrader flag
    SHIZEN
    @EuroTraderokay thanks a lot for this, EU is still shooting up
    @SHIZENyeah mate that's what we are seeing at the moment, and from there we will change structure
    EuroTrader flag
    SHIZEN
    @EuroTraderSo howany percentage do you think the trade could add to such a set up
    @SHIZENThis heavily depends on the trade mate, it's not a general rule
    EuroTrader flag
    EuroTrader
    @SHIZENThis heavily depends on the trade mate, it's not a general rule
    @SHIZENHowever, i can tell you that even when adding some weight to the lots, you should take a calculated risk
    Type here...
    Add Symbol or Code

      No matching data

      All
      Recommend
      Stocks
      Cryptocurrencies
      Central Banks
      Trump Updates
      Featured News
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint

      Search
      Products

      Charts Free Forever

      Chats Q&A with Experts
      Screeners Economic Calendar Data Tools
      Membership Features
      Data Warehouse Market Trends Institutional Data Policy Rates Macro

      Market Trends

      Market Sentiment Order Book Forex Correlations

      Top Indicators

      Charts Free Forever
      Markets

      News

      24/7 Analysis Education

      Latest Views

      Latest Update

      Signals

      Copy Rankings Latest Signals Become a signal provider AI Rating
      Contests
      Brokers

      Overview Brokers Assessment Rankings Regulators News Claims
      Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
      Q&A Complaint Scam Alert Videos Tips to Detect Scam
      More

      Business
      Events
      Careers About Us Advertising Help Center

      White Label

      Broker API

      Data API

      Web Plug-ins

      Affiliate Program

      Awards Institution Evaluation IB Seminar Salon Event Exhibition
      Vietnam Thailand Singapore Dubai
      Fans Party Investment Sharing Session
      FastBull Summit BrokersView Expo
      Recent Searches
        Top Searches
          Markets
          Analysis
          User
          24/7
          Economic Calendar
          Education
          Data
          • Names
          • Latest
          • Prev

          View All

          No data

          Scan to Download

          Faster Charts, Chat Faster!

          Download
          English
          • English
          • Español
          • العربية
          • Bahasa Indonesia
          • Bahasa Melayu
          • Tiếng Việt
          • ภาษาไทย
          • Français
          • Italiano
          • Türkçe
          • Русский язык
          • 简中
          • 繁中
          Open Account
          Search
          Products
          Charts Free Forever
          Markets
          News
          Signals

          Copy Rankings Latest Signals Become a signal provider AI Rating
          Contests
          Brokers

          Overview Brokers Assessment Rankings Regulators News Claims
          Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
          Q&A Complaint Scam Alert Videos Tips to Detect Scam
          More

          Business
          Events
          Careers About Us Advertising Help Center

          White Label

          Broker API

          Data API

          Web Plug-ins

          Affiliate Program

          Awards Institution Evaluation IB Seminar Salon Event Exhibition
          Vietnam Thailand Singapore Dubai
          Fans Party Investment Sharing Session
          FastBull Summit BrokersView Expo

          The ‘Doom Loop’ and Default Incentives

          CEPR

          Economic

          Bond

          Summary:

          This column explores the impact of default risk on policies aimed at breaking the doom loop. According to the authors’ model, factoring in default risk has major implications for the choice and calibration of such policies.

          The ‘doom loop’ describes the spillovers between fiscal sustainability risk and financial stability risk, arising from the government and financial sectors each being exposed to stress in the other sector. Specifically, if sovereign bonds lose value because the government’s creditworthiness is declining, the balance sheets of financial institutions suffer, because they hold large amounts of domestic government bonds. Weakened financial institutions, in turn, may force the government to bail out the financial system. Such bailouts entail expenses for the government, casting a further shadow over their finances. This vicious circle can exacerbate economic downturns (Acharya et al. 2014, Farhi and Tirole 2018) or even trigger purely panic-driven crises (Brunnermeier et al. 2016, 2017;, Cooper and Nikolov 2018). This is why sovereign crises can develop suddenly – and can easily spiral out of control.
          The ‘Doom Loop’ and Default Incentives_1
          To break the doom loop, a common policy recommendation is to sever the link between the financial system, or banks for short, and the government. How can this be done? One way is to limit banks’ exposure to domestic sovereign debt – for example, through regulatory requirements. Another way is to stabilise bond prices near their fundamental value by providing a central bank backstop through bond purchases. Indeed, such policy proposals have emerged as lessons learned from the euro area debt crisis (e.g. Bénassy-Quéré et al. 2019).
          However, this reasoning overlooks a critical aspect: how the identity of the government’s creditors shapes its default incentives and ultimately the sustainability of its debt. Lowering domestic banks’ exposure to sovereign debt can weaken a government’s incentives to avoid default in two ways (Bolton and Jeanne 2011, Gennaioli et al. 2014). First, if domestic banks hold lower volumes of domestic sovereign bonds, a greater share needs to be held by foreigners. Governments are typically less inclined to repay foreign lenders than domestic ones, so this increases the likelihood of default. Second, if banks are shielded from a sovereign debt crisis, the fallout of a sovereign default will be less severe, which can also increase the likelihood of default. We refer to these two effects as the ‘temptation channel’ and the ‘commitment channel’, respectively. Through these channels, policies reducing the exposure of domestic banks to domestic sovereign debt may inadvertently undermine fiscal sustainability.
          In Rojas and Thaler (2024), we explore this tension between the detrimental effects of banks’ exposure to domestic sovereign debt (the doom loop) and the beneficial effects related to governments’ default incentives (the temptation and the commitment channels). We use a simple three-period model of sovereign debt and banking that incorporates multiple equilibria – similar to the frameworks used in the aforementioned studies. We focus on the strategic nature of sovereign default. Our analysis reveals the unintended consequences of interventions aimed at breaking the doom loop and highlights unexpected benefits of non-interventionist approaches.

          Unintended consequences of limiting banks’ exposure

          Limiting banks’ holdings of domestic sovereign bonds deactivates the doom loop by breaking one link in the chain: domestic banks’ balance sheets are no longer negatively affected if the price of sovereign bonds falls, which prevents further financial stress.
          However, it entails other risks and costs. In most countries, the domestic financial sector is a major holder of domestic sovereign bonds. As Figure 2 shows, in 2023 the domestic financial sector held more than 50% of sovereign debt in countries like Spain, Italy and Germany. So, a limit would cause a significant shift of sovereign debt from domestic to foreign holders.
          The ‘Doom Loop’ and Default Incentives_2
          This shift can affect the likelihood of default through the temptation and commitment channels. The lower the holdings by domestic banks, the greater the temptation for that government to default, as a higher fraction of debt is held by foreigners. Simultaneously, the less the domestic financial sector would suffer from a government default, the weaker that government’s implicit commitment to repay. So where is the problem, as long as the sovereign does not actually default? In fact, while limiting banks’ exposure can reduce the likelihood of a panic driven by the doom loop, the associated higher risk of fundamental default would increase risk premia and therefore public sector financing costs during normal times. These costs must be weighed against the benefits of eliminating the doom loop. If the risk of a doom loop is sufficiently low, why pay to insure against it?

          Benefits of debt renationalisation during panics

          During financial turmoil, governments often incur significant fiscal expenses – such as bailouts – which force the government to issue additional debt. If all of the new debt is bought by foreign investors, then the government’s temptation to default increases, fuelling the doom loop. Conversely, if domestic banks purchase the additional debt, the temptation to default does not rise and sovereign debt prices do not fall in response to a bailout – effectively disabling the doom loop.
          In other words, debt renationalisation can act as a stabiliser in times of sovereign stress by preventing self-reinforcing fears of default. Both the European sovereign debt crisis and, more recently, the COVID-19 crisis featured debt renationalisation. While such shifts in investor composition are often seen as a problem, our theory suggests they may actually be beneficial – and should not be restricted by regulation.

          Policies in a monetary union

          At the EU level, two policy proposals have attracted particular attention: first a central bank backstop such as the ECB’s Transmission Protection Instrument (TPI) and, second, the European Safe Bonds (ESBies) proposal by Brunnermeier et al. (2016, 2017). By analysing the interplay between investor composition and government default, we uncover important lessons for both policy approaches.

          The Transmission Protection Instrument

          As yields on European debt climbed at the start of the COVID crisis, sparking fears of a return of the doom loop, the ECB launched the Transmission Protection Instrument (TPI). It enables the ECB “to make secondary market purchases of securities issued in jurisdictions experiencing a deterioration in financing conditions not warranted by country-specific fundamentals” (ECB press release, 21 July 2022). The doom loop produces just such non-fundamental variation in sovereign bond prices.
          In our set-up, the TPI can indeed be an effective tool to avoid the panic-driven doom loop. Flooring sovereign debt prices limits the potential losses of financial institutions, avoiding large bailouts and consequently the spillover from fiscal to financial risk.
          However, the policy must be carefully calibrated to avoid the risk of a new self-fulfilling panic. Imagine that all private investors sell off the bonds of one particular government. Bond prices drop until they reach the threshold at which the ECB intervenes by buying debt to stabilise the price. This insulates banks from any further losses in case of a subsequent default, reducing the government’s incentive to repay its debts through the commitment channel. And to the extent that part of the default losses faced by the ECB are shared across the member states, it also reduces the repayment incentive through the temptation channel. Consequently, the perceived risk of a sovereign default increases. If the ECB buys the bonds at prices above the levels justified by the higher default risk due to a change in investor composition, the initial sell-off to the ECB is rational from an investor’s perspective. The sell-off thus becomes self-fulfilling.
          Such a panic can be avoided if the ECB sets a floor for bond prices far enough below their fundamental value. However, the floor must not be too low, or it will fail to curb the original doom loop panic. Picking the right intervention threshold is therefore a delicate balancing act.
          The risk-sharing arrangements among the individual national central banks and the rest of the Eurosystem play an important role in finding this balance. The less risk-sharing there is, the larger the range of desirable intervention thresholds for the bond price. In other words, less risk-sharing makes it easier to successfully calibrate the TPI.

          European Safe Bonds

          The proposal for European Safe Bonds (ESBies) consists in a macroprudential policy restricting the sovereign bond holdings of euro area banks to ESBies, which would be the senior tranche of a bundle of European bonds. This way banks would avoid large exposures to their own government and would have a ‘safer’ asset. However, this policy could have two unwanted side effects.
          First, as mentioned earlier, this could increase financing costs due to weakened incentives to repay. Second, while the doom loop at the national level would disappear, a new doom loop could emerge: sufficiently widespread panic about euro area countries’ ability to repay their debts could trigger a repricing of the senior tranche, destabilising the financial system Europe-wide. This, in turn, could force several countries to bail out their banks – creating a new, even larger doom loop at the European level.
          To stay updated on all economic events of today, please check out our Economic calendar
          Risk Warnings and Disclaimers
          You understand and acknowledge that there is a high degree of risk involved in trading. Following any strategies or investment methods may lead to potential losses. The content on the site is provided by our contributors and analysts for information purposes only. You are solely responsible for determining whether any trading assets, securities, strategy, or any other product is suitable for investing based on your own investment objectives and financial situation.
          Add to Favorites
          Share
          FastBull
          Copyright © 2026 FastBull Ltd

          728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG

          TelegramInstagramTwitterfacebooklinkedin
          App Store Google Play Android Windows
          Products
          Charts

          Chats

          Q&A with Experts
          Screeners
          Economic Calendar
          Data
          Tools
          Membership
          Features
          Function
          Markets
          Copy Trading
          Latest Signals
          Contests
          24/7
          Analysis
          Education
          Company
          Careers
          About Us
          Contact Us
          Advertising
          Download FastBull
          Help Center
          Feedback
          User Agreement
          Privacy Policy
          Personal Information Protection Statement
          Business

          White Label

          Broker API

          Data API

          Web Plug-ins

          Poster Maker

          Affiliate Program

          Risk Disclosure

          The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.

          No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.

          Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.

          Not Logged In

          Log in to access more features

          Connect Broker
          Become a signal provider
          Help Center
          Customer Service
          Dark Mode
          Price Up/Down Colors

          Log In

          Sign Up

          Position
          Layout
          Fullscreen
          Default to Chart
          The chart page opens by default when you visit fastbull.com