


- GBPUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev











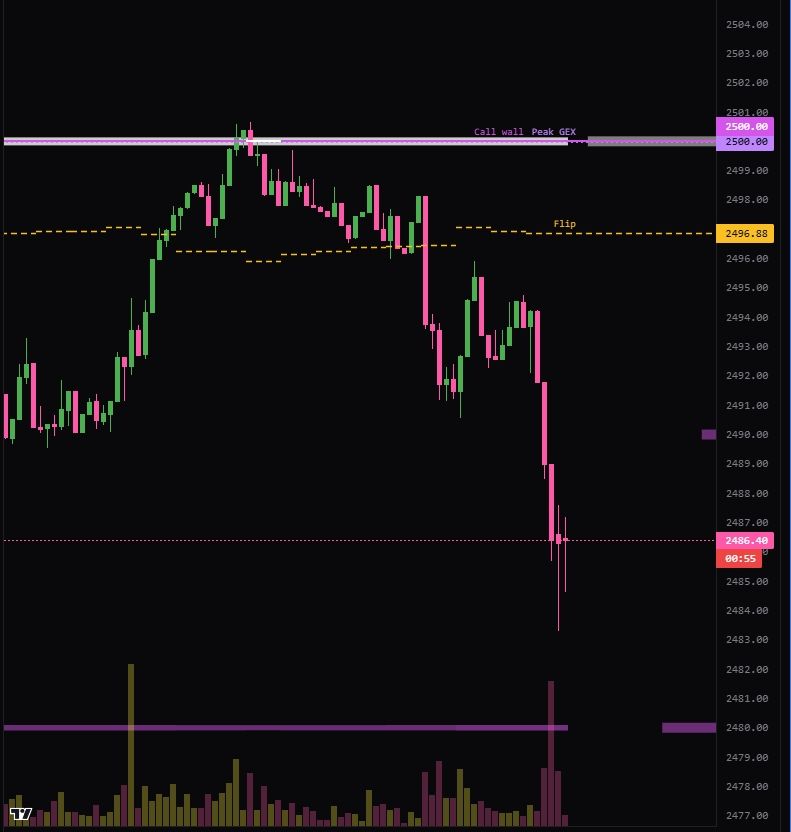
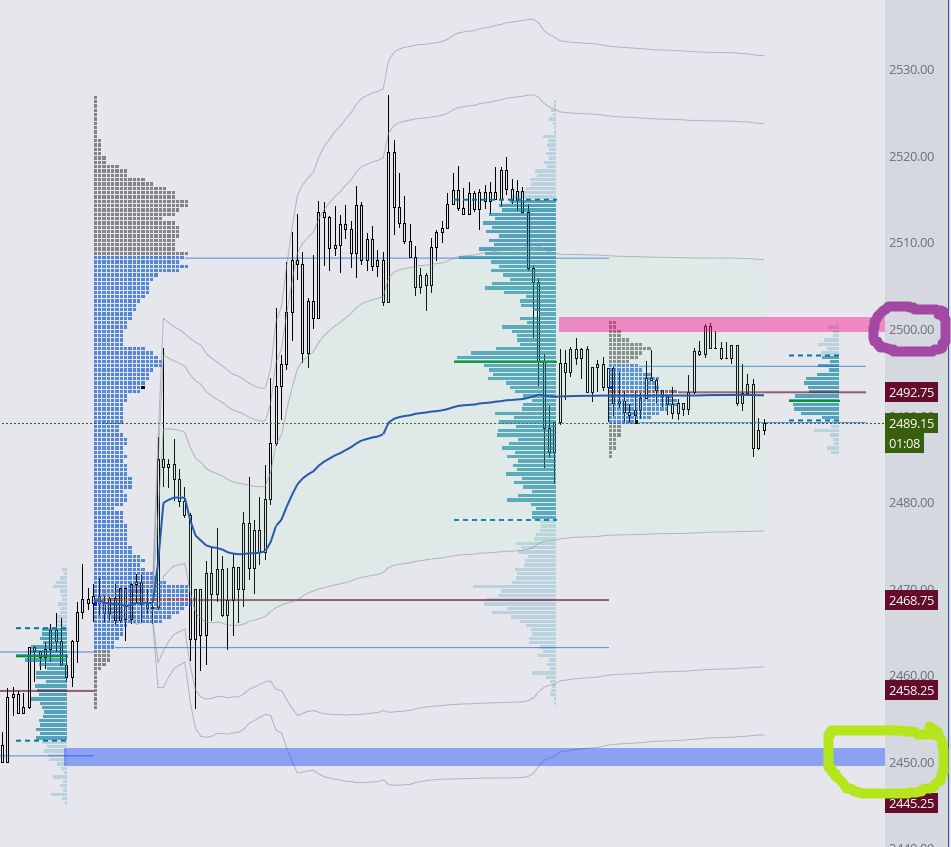
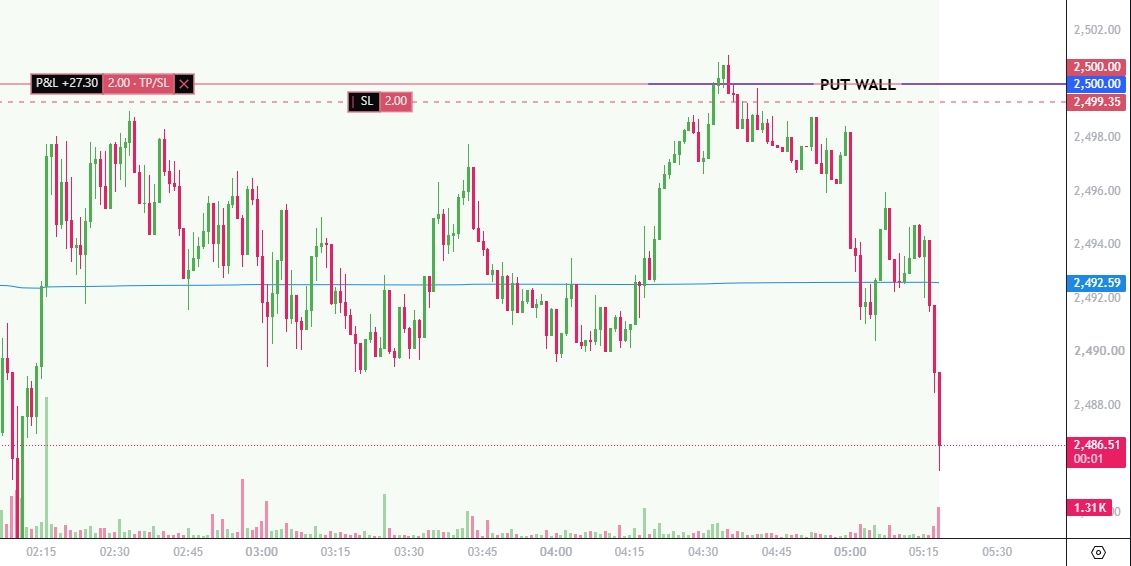
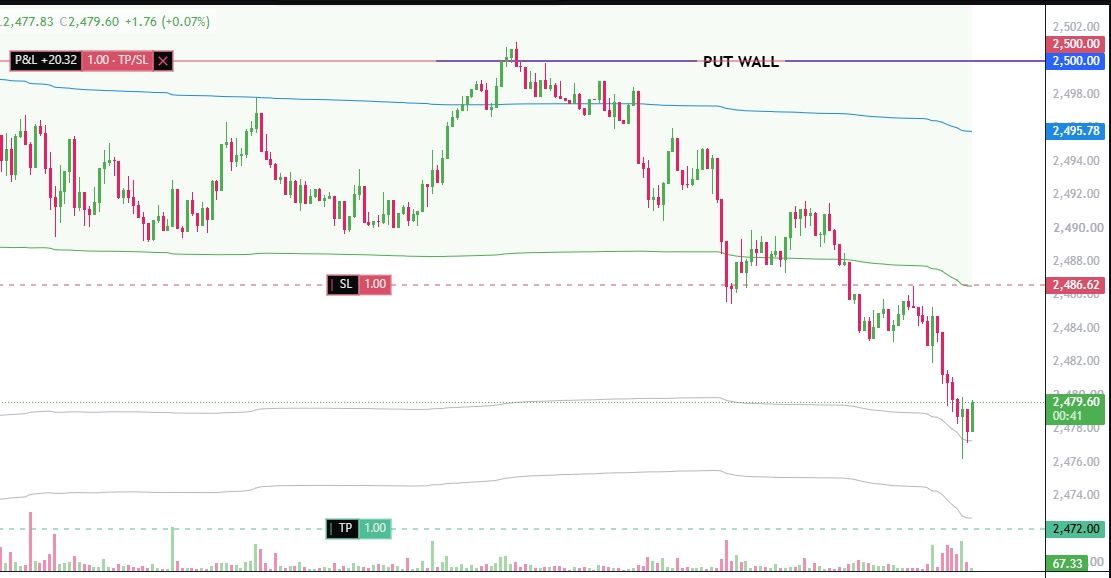
The US Federal Reserve (Fed) mostly did what was expected when it announced its policy update yesterday: it kept rates unchanged.
The US Federal Reserve (Fed) mostly did what was expected when it announced its policy update yesterday: it kept rates unchanged. Fed Chair Powell didn't comment on the latest political drama surrounding the Fed and himself, nor on whether he would leave the committee when his term as Chair ends in May. Instead, he advised the next lucky person to take the helm of the Fed to "stay out of elected politics." Two members voted to cut rates by 25bp – guess who?
That was the expected part. The surprise came from the economic outlook.
Powell pointed to a "clear improvement" in the US outlook, said the job market shows signs of steadying, and highlighted surprisingly "strong" growth. But a good part of that growth is explained by AI investment, which for now does not create many jobs. On the contrary, there has been a wave of job cuts announced recently. Amazon, for example, is looking to cut 16'000 jobs on top of the 14'000 let go last year. Meta is laying off around 10% of its Reality Labs employees. Microsoft cut more than 9'000 jobs last year. Nvidia is cutting jobs. Banks are cutting jobs. Some of these cuts have nothing to do with AI, but some clearly do. Meanwhile, yesterday's survey showed that people find it harder to get jobs.
So the Fed is caught between a rock and a hard place. If inflation continues cooling, the Fed's job will be easier. But energy prices are pushing higher this January, driven by cold weather and geopolitical tensions involving oil producers. US natural gas prices jumped more than 50% in less than two weeks. US crude climbed past the $64pb mark this morning on fears of a potential US attack on Iran. Prices are now above the 200-day moving average and testing a key Fibonacci level — the 38.2% retracement of the June-to-December sell-off — while US gasoline prices are up more than 13% this month.
In the medium term, these heightened energy price pressures should ease. Weather- and geopolitically-driven price spikes don't change longer-term fundamentals. Global oil supply remains ample and comfortably meets demand.
In the shorter run, however, this argues for the Fed to sit tight before delivering another rate cut — assuming it already cut rates over the three meetings preceding this week's decision. The next Fed rate cut is not expected before June, and that with roughly a 60% probability. Things could change quickly — in either direction — so incoming data will matter.
For now, bets still tilt towards a less dovish Fed. The US 2-year yield, which captures Fed rate expectations, appears to be bottoming near 3.60%, while the 10-year yield has climbed above 4.20% since the start of the week. Yields are also being pressured by talk of a potential partial government shutdown if Congress fails to pass new appropriations by tomorrow midnight.
Japanese yields, meanwhile, are moving lower, which helps avoid additional upward pressure on global yields. Still, a more hawkish-than-expected Fed tone following this week's FOMC decision, combined with political and geopolitical uncertainty, is weighing on US bonds. This theme is likely to persist unless something fundamental changes in the way the White House operates.
Equities, however, don't seem to care. The S&P 500 hit the 7'000 mark for the first time, and futures are positive at the time of writing. Three US tech giants reported earnings after the bell yesterday. They beat expectations and announced higher AI spending, but market reactions varied sharply.
Meta was praised for its improved profit outlook. The company has manages to turn AI spending into cash via advertising revenues, showing that its core business is performing well. Investors also welcomed the reduced focus on Reality Labs, a cash-burning division that has yet to gain meaningful adoption. Microsoft, by contrast, was punished as cloud growth came in below analysts' expectations — a major concern given that cloud is the segment meant to justify heavy AI investment. Slower cloud growth made investors unhappy about further AI spending.
As for Tesla, profits plunged 61% in Q4 year-on-year. No surprise: sales have been falling since last year, partly reflecting Elon Musk's political positioning. What's surprising, however, is the market's reaction. Tesla is a case study in itself — one that will allow academics to examine how a company with profits down more than 60% can still attract investor enthusiasm for projects largely unrelated to its core business. Investors welcomed Tesla's plans to invest more than $20 billion this year in advanced AI, robotics, autonomous vehicles and energy storage, including a $2 billion investment in Elon Musk's xAI startup! The company's price-to-earnings ratio is now above 350. This is pure speculation on someone entirely unpredictable — but admittedly, it's entertaining!
In FX markets, the Fed's optimistic tone initially helped the US dollar rebound, but gains proved short-lived. The dollar index is back under pressure this morning.
One factor weighing on the dollar was US Treasury Secretary Scott Bessent's CNBC interview, during which he said the US is "absolutely not" intervening to support the Japanese yen. The New York Fed's calls to traders to check yen levels were, apparently, just that — curiosity, information-gathering…
The immediate consequence for Japan is that Bessent effectively spoiled the intervention narrative. The USDJPY bounced from the 152 level, which had been reached on speculation that US and Japanese authorities might jointly step in to curb yen weakness. Japan is now on its own. With or without the US help, authorities will continue to fight against the yen shorts as they dislike the pace of depreciation as it hurts households and erodes purchasing power, but at 152, intervention looks unlikely. On that basis, yen shorts may cautiously rebuild positions at these levels — cautiously though, until intervention threats ease.
Fundamentally, the yen is likely to remain under pressure at least until the February 8 snap election, which prices the risk of Takaichi consolidating political power. She favours ample fiscal spending — pushing yields higher — alongside supportive monetary policy, which weighs on the yen. As per the the Bank of Japan, it does not suffer from independence issues and remains willing to hike rates as part of its policy-normalisation process. But even so, last year's hawkish signals did little to provide lasting support for the yen.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


