• Trade
  • Markets
  • Copy
  • Contests
  • 24/7
  • Calendar
  • Q&A
  • Chats
Screeners
SYMBOL
LAST
BID
ASK
HIGH
LOW
NET CHG.
%CHG.
SPREAD
SOURCE
SPX
S&P 500 Index
7663.43
7663.43
7663.43
7702.94
7637.36
-93.74
-1.21%
--
--
DJI
Dow Jones Industrial Average
52867.98
52867.98
52867.98
52927.88
52508.38
+11.89
+ 0.02%
--
--
IXIC
NASDAQ Composite Index
26008.85
26008.85
26008.85
26359.41
25918.09
-694.00
-2.60%
--
--
USDX
US Dollar Index
101.470
101.470
101.550
101.470
101.290
+0.040
+ 0.04%
--
--
EURUSD
Euro / US Dollar
1.12105
1.12105
1.12115
1.12261
1.12099
-0.00047
-0.04%
--
--
GBPUSD
Pound Sterling / US Dollar
1.33930
1.33930
1.33941
1.34071
1.33841
-0.00057
-0.04%
--
--
XAUUSD
Gold / US Dollar
3994.89
3994.89
3995.27
4032.52
3992.53
-29.45
-0.73%
--
--
WTI
Light Sweet Crude Oil
99.951
99.951
99.986
100.079
98.359
+1.338
+ 1.36%
--
--

Community Accounts

Signal Accounts
--
Profit Accounts
--
Loss Accounts
--
View More

Become a signal provider

Sell trading signals to earn additional income

View More

Guide to Copy Trading

Get started with ease and confidence

View More

Signal Accounts for Members

All Signal Accounts

Best Return
  • Best Return
  • Best P/L
  • Best MDD
Past 1W
  • Past 1W
  • Past 1M
  • Past 1Y

All Contests

  • All
  • Recommend
  • Stocks
  • Cryptocurrencies
  • Central Banks
  • Trump Updates
  • Featured News
Top News Only
Share

The Most Active Polypropylene Futures Contract Rose 4% Intraday, Currently Trading At 9638.00 Yuan

Share

The Main Liquefied Petroleum Gas (LPG) Futures Contract Rose 7% Intraday, Currently Trading At 7330.00 Yuan

Share

Liquefied Petroleum Gas (LPG) Contracts Hit Their Daily Limit Up, With Contracts 2703, 2704, 2705, And 2708 All Hitting Their Daily Limit Up During The Session. The Main Contract (2612) Rose By Nearly 7%

Share

The Shanghai Crude Oil Futures Contract Rose 4% Intraday, Currently Trading At 730.20 Yuan

Share

New York Gold Futures Fell Below $4,010 Per Ounce, Down 1.24% On The Day

Share

The Most Active Fuel Oil Futures Contract Rose 6% Intraday, Currently Trading At 5102.00 Yuan

Share

New York Silver Futures Fell 2% On The Day, Currently Trading At $53.89 Per Ounce

Share

The Most Active Liquefied Petroleum Gas (LPG) Futures Contract Rose 6% Intraday, Currently Trading At 7260.00 Yuan

Share

New York Gold Futures Fell 1% On The Day, Currently Trading At $4,018.43 Per Ounce

Share

Spot Gold Fell Below $4,010 Per Ounce, Down 0.38% On The Day

Share

The Most Active Soda Ash Futures Contract Rose 1% Intraday, Currently Trading At 946.00 Yuan

Share

The Yield On Japan's Two-year Government Bonds Fell 6 Basis Points To 1.840%

Share

The Colombian Government Has Ordered A 13.8 Trillion Peso Cut In Its 2026 Budget

Share

The Yield On Japan's 5-year Government Bonds Fell 10.5 Basis Points To 2.185%

Share

Spot Silver Fell 1.00% On The Day, Currently Trading At $54.03 Per Ounce

Share

Song Xiaoxiao Of Changjiang Securities: With Exports And Fiscal Policy As Dual Supports, The Economy Is Resilient In The Fourth Quarter

Share

Japanese Officials: The Japanese Government Is Considering Reducing Gasoline Subsidies As Early As December

Share

The Main Manganese Silicon Futures Contract Rose By 2.00% During The Day, Currently Trading At 5904.00 Yuan/ton

Share

The Most Active Tin Contract On The Shanghai Stock Exchange Fell 2.00% During The Day, Currently Trading At 375,830.00 Yuan/ton

Share

Samsung Is Reportedly Planning To Increase Its Mobile Phone Exports To India, And May Move Some Of Its Production Lines From Vietnam To India

TIME
ACT
FCST
PREV
IMPACT
U.K. CBI Industrial Prices Expectations (Oct)

A:--

F: --

P: --

GBPUSD
  • GBPUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Turkey Late Liquidity Window Rate (LON) (Oct)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Turkey Overnight Lending Rate (O/N) (Oct)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Turkey 1-Week Repo Rate

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Mexico Unemployment Rate (Not SA) (Sept)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Canada New Housing Price Index MoM (Sept)

A:--

F: --

P: --

USDCAD
  • USDCAD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Canada Industrial Product Price Index YoY (Sept)

A:--

F: --

P: --
USDCAD
  • USDCAD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Canada Industrial Product Price Index MoM (Sept)

A:--

F: --

P: --
USDCAD
  • USDCAD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Initial Jobless Claims (SA)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Initial Jobless Claims 4-Week Avg. (SA)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Continued Jobless Claims (SA)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
BOE Gov Bailey Speaks
U.S. Conference Board Coincident Economic Index MoM (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Conference Board Lagging Economic Index MoM (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Conference Board Leading Economic Index (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Euro Zone Consumer Confidence Index Prelim (Oct)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Conference Board Leading Economic Index MoM (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. EIA Weekly Natural Gas Stocks Change

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
U.S. Kansas Fed Manufacturing Production Index (Oct)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Kansas Fed Manufacturing Composite Index (Oct)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Argentina Retail Sales YoY (Aug)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Treasuries Held by Foreign Central Banks

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Australia Composite PMI Prelim (Oct)

A:--

F: --

P: --

AUDUSD
  • AUDUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Australia Manufacturing PMI Prelim (Oct)

A:--

F: --

P: --

AUDUSD
  • AUDUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.K. GfK Consumer Confidence Index (Oct)

A:--

F: --

P: --

GBPUSD
  • GBPUSD
  • XAUUSD
  • XAGUSD
  • WTI
Japan National Core CPI YoY (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan National CPI YoY (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan National CPI MoM (Not SA) (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan National CPI MoM (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
Japan CPI MoM (Sept)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Japan Manufacturing PMI Prelim (SA) (Oct)

A:--

F: --

P: --

USDJPY
  • USDJPY
  • XAUUSD
  • XAGUSD
  • WTI
U.K. Retail Sales MoM (SA) (Sept)

--

F: --

P: --

U.K. Core Retail Sales YoY (SA) (Sept)

--

F: --

P: --

U.K. Retail Sales YoY (SA) (Sept)

--

F: --

P: --

France Manufacturing PMI Prelim (Oct)

--

F: --

P: --

France Services PMI Prelim (SA) (Oct)

--

F: --

P: --

France Composite PMI Prelim (SA) (Oct)

--

F: --

P: --

Germany Manufacturing PMI Prelim (SA) (Oct)

--

F: --

P: --

Germany Services PMI Prelim (SA) (Oct)

--

F: --

P: --

Germany Composite PMI Prelim (SA) (Oct)

--

F: --

P: --

Euro Zone Composite PMI Prelim (SA) (Oct)

--

F: --

P: --

Euro Zone Manufacturing PMI Prelim (SA) (Oct)

--

F: --

P: --

Euro Zone Services PMI Prelim (SA) (Oct)

--

F: --

P: --

U.K. Manufacturing PMI Prelim (Oct)

--

F: --

P: --

U.K. Services PMI Prelim (Oct)

--

F: --

P: --

U.K. Composite PMI Prelim (Oct)

--

F: --

P: --

Russia Key Rate

--

F: --

P: --

Mexico Economic Activity Index YoY (Aug)

--

F: --

P: --

Canada Retail Sales MoM (SA) (Aug)

--

F: --

P: --

Canada Core Retail Sales MoM (SA) (Aug)

--

F: --

P: --

U.S. IHS Markit Services PMI Prelim (SA) (Oct)

--

F: --

P: --

U.S. IHS Markit Composite PMI Prelim (SA) (Oct)

--

F: --

P: --

U.S. IHS Markit Manufacturing PMI Prelim (SA) (Oct)

--

F: --

P: --

U.S. UMich Consumer Expectations Index Final (Oct)

--

F: --

P: --

U.S. UMich Consumer Sentiment Index Final (Oct)

--

F: --

P: --

U.S. UMich 1-Year-Ahead Inflation Expectations Final (Oct)

--

F: --

P: --

U.S. UMich Current Economic Conditions Index Final (Oct)

--

F: --

P: --

U.S. Weekly Total Oil Rig Count

--

F: --

P: --

U.S. Weekly Total Rig Count

--

F: --

P: --

Germany IFO Business Climate Index (SA) (Oct)

--

F: --

P: --

Germany Ifo Current Business Situation Index (SA) (Oct)

--

F: --

P: --

Q&A with Experts
    • All
    • Chatrooms
    • Groups
    • Friends
    tama flag
    wow
    1999kk.king flag
    1999kk.king flag
    5884583 flag
    how u know gold was bottom already
    1999kk.king flag
    没有说触底就算有低点继续持有 中长线肯定大大盈利获利可观
    1999kk.king flag
    认为价位可以满足你的地方你就可以持有啦迟早都会上来的一直追空也没意思价位越来越低你做空的风险就越来越大
    5884583 flag
    You have great vision
    Areeba Mini❣️❣️ flag
    Nawhdir flag
    Nawhdir flag
    Areeba Mini❣️❣️ flag
    1999kk.king flag
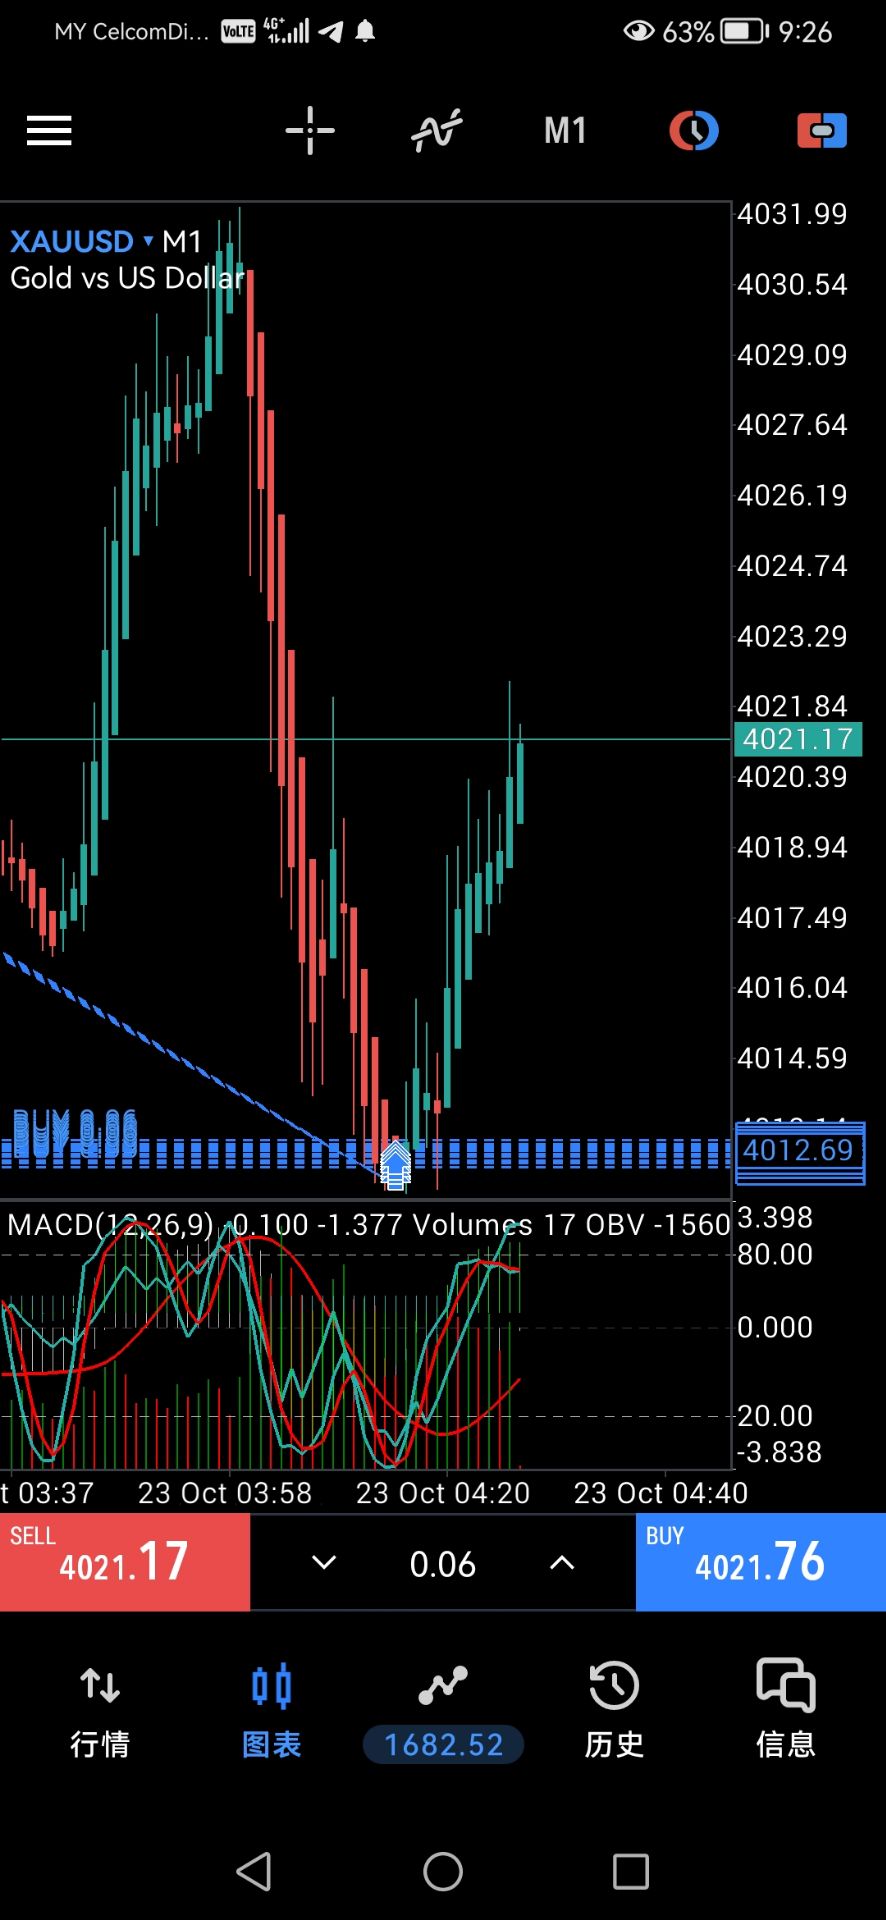
    4012也做了
    1999kk.king flag
    Areeba Mini❣️❣️ flag
    Areeba Mini❣️❣️ flag
    fulltimetrader flag
    4023-4025↓ SL4032.5
    "fulltimetrader" recalled a message
    fulltimetrader flag
    4010很可能破位
    JianhuiFan flag
    尝试做多一下
    77 flag
    要疯了
    Type here...
    Add Symbol or Code

      No matching data

      All
      Recommend
      Stocks
      Cryptocurrencies
      Central Banks
      Trump Updates
      Featured News
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint

      Search
      Products

      Charts Free Forever

      Chats Q&A with Experts
      Screeners Economic Calendar Data Tools
      Membership Features
      Data Warehouse Market Trends Institutional Data Policy Rates Macro

      Market Trends

      Market Sentiment Order Book Forex Correlations

      Top Indicators

      Charts Free Forever
      Markets

      News

      24/7 Analysis Education

      Latest Views

      Latest Update

      Signals

      Copy Rankings Latest Signals Become a signal provider AI Rating
      Contests
      Brokers

      Overview Brokers Assessment Rankings Regulators News Claims
      Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
      Q&A Complaint Scam Alert Videos Tips to Detect Scam
      More

      Business
      Events
      Careers About Us Advertising Help Center

      White Label

      Broker API

      Data API

      Web Plug-ins

      Affiliate Program

      Awards Institution Evaluation IB Seminar Salon Event Exhibition
      Vietnam Thailand Singapore Dubai
      Fans Party Investment Sharing Session
      FastBull Summit BrokersView Expo
      Recent Searches
        Top Searches
          Markets
          Analysis
          User
          24/7
          Economic Calendar
          Education
          Data
          • Names
          • Latest
          • Prev

          View All

          No data

          Scan to Download

          Faster Charts, Chat Faster!

          Download
          English
          • English
          • Español
          • العربية
          • Bahasa Indonesia
          • Bahasa Melayu
          • Tiếng Việt
          • ภาษาไทย
          • Français
          • Italiano
          • Türkçe
          • Русский язык
          • 简中
          • 繁中
          Open Account
          Search
          Products
          Charts Free Forever
          Markets
          News
          Signals

          Copy Rankings Latest Signals Become a signal provider AI Rating
          Contests
          Brokers

          Overview Brokers Assessment Rankings Regulators News Claims
          Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
          Q&A Complaint Scam Alert Videos Tips to Detect Scam
          More

          Business
          Events
          Careers About Us Advertising Help Center

          White Label

          Broker API

          Data API

          Web Plug-ins

          Affiliate Program

          Awards Institution Evaluation IB Seminar Salon Event Exhibition
          Vietnam Thailand Singapore Dubai
          Fans Party Investment Sharing Session
          FastBull Summit BrokersView Expo

          IC Markets Asia Fundamental Forecast | 6 August 2025

          IC Markets

          Commodity

          Forex

          Economic

          Summary:

          U.S. stocks rebounded from oversold levels, but the macro backdrop remains tentative: jobs growth is soft, services and manufacturing are under pressure, and global trade uncertainty continues to weigh on sentiment.

          What happened in the U.S session?

          U.S. stocks rebounded from oversold levels, but the macro backdrop remains tentative: jobs growth is soft, services and manufacturing are under pressure, and global trade uncertainty continues to weigh on sentiment. Safe-haven demand held for bonds and gold as prospects for Fed easing increased; the dollar was volatile amid shifting rate outlooks and policy uncertainty. The most-affected assets were technology stocks, exporter equities, Treasuries, the dollar, and industrial commodities like copper. Overall, the session reflected cautious optimism for risk assets but remains highly sensitive to economic data and new trade policy headlines, with defensive positioning prevalent across global markets.

          What does it mean for the Asia sessions?

          Asian traders should watch for volatility driven by regional data, U.S. tariff fallout, and powerful capital rotation flows. Earnings resilience and currency support remain tailwinds, even as headlines around trade, shipping, and macro releases heighten the potential for sharp, reactive moves throughout Wednesday’s session. Foreign funding rotation into Asian equities remains the dominant theme, aided by currency momentum and robust earnings, but sensitive to policy shifts and global trade headlines.Market focus stays on U.S. tariff escalations and their supply chain impacts, especially for India, South Korea, and China. Wednesday’s inflation prints (China), central bank updates (India), and wage/employment reports (Japan, NZ) are likely to drive near-term volatility, particularly for FX and equities. Watch for further declines in metals and freight rates if Chinese data stays weak, but oil may remain rangebound awaiting fresh supply/demand signals.

          The Dollar Index (DXY)

          On August 6, 2025, the dollar is showing mild weakness, pressured by increasingly soft domestic economic data, firm bets for Fed rate cuts, and defensive global risk sentiment. The dollar’s trend remains volatile and data-driven, with further swings possible as the macro and policy landscape develops through the week. The U.S. dollar continued to weaken against most major and emerging market currencies, following a sharp drop triggered by soft U.S. ISM PMI and factory order data earlier in the week. The DXY index fell from above 100 to below 99 late last week and has been unable to recover meaningfully, with volatility staying elevated due to shifting Fed expectations.Central Bank Notes:

          ● The Board of Governors of the Federal Reserve System voted unanimously to maintain the Federal Funds Rate in a target range of 4.25% to 4.50% at its meeting on July 29–30, 2025, keeping policy unchanged for the fifth consecutive meeting.
          ● The Committee reiterated its objective of achieving maximum employment and inflation at the rate of 2% over the longer run. While uncertainty around the economic outlook has diminished since earlier in the year, the Committee notes that challenges remain and continued vigilance is warranted.
          ● Policymakers remain highly attentive to risks on both sides of their dual mandate. The unemployment rate remains low, near 4.2%–4.5%, and labor market conditions are described as solid. However, inflation is still somewhat elevated, with the PCE price index at 2.6% and core inflation forecast at 3.1% for year-end 2025, up from earlier projections; tariff-related pressures are cited as a contributing factor.
          ● The Committee acknowledged that recent economic activity has expanded at a solid pace, with second-quarter annualized growth estimates near 2.4%. However, GDP growth for 2025 has been revised downward to 1.4% (from 1.7% projected in March), reflecting expectations of a slowdown in the coming quarters.
          ● In the revised Summary of Economic Projections, the unemployment rate is expected to average 4.5% in 2025, and headline PCE inflation is forecast at 3.0% for the year, with core PCE at 3.1%. Policymakers continue to anticipate that inflation will moderate gradually, with ongoing risks from tariffs and global conditions.
          ● The Committee reaffirmed its data-dependent and risk-aware approach to future policy decisions. Officials stated they are prepared to adjust the stance of monetary policy as appropriate if risks emerge that could impede progress toward the Fed’s goals.
          ● As previously outlined, the Committee continues the measured run-off of its securities holdings. The pace of balance sheet reduction, which slowed since April (monthly redemption cap on Treasury securities reduced from $25B to $5B, while holding agency MBS cap steady at $35B), was left unchanged this month to support orderly market functioning and financial conditions.
          ● The next meeting is scheduled for 16 to 17 September 2025.

          Next 24 Hours Bias

          Weak Bearish

          Gold (XAU)

          Gold continues to trade near all-time highs, underpinned by dovish Fed expectations, robust safe-haven demand, and ongoing political and trade uncertainty, even as minor U.S. dollar strength briefly caps further gains. The outlook remains bullish-to-neutral with volatility likely as global headline risk persists. Gold remains supported by a surge in expectations for a September interest rate cut from the Federal Reserve, triggered by last week’s weak jobs data and ongoing economic softness. Market participants currently price in about an 81% chance of a rate cut in September, with at least two cuts forecast before year-end.

          Next 24 Hours Bias

          Medium Bullish

          The Australian Dollar (AUD)

          The Australian Dollar starts August 6 on the defensive, trading at multi-month lows versus the U.S. dollar as the RBA is expected to cut rates, and labor data signal ongoing softening. Modest gains in household spending and services activity offer some support, but the overall trend remains weak amid global and local headwinds. Markets are positioned for further volatility tied to monetary policy, jobs data, and global macro developments.

          Central Bank Notes:

          ● The RBA held its cash rate steady at 3.85% at the July meeting on 8 July 2025, following a 25bps reduction in May and in line with widespread market expectations after recent data showed inflation tracking within the target band.
          ● Inflation continues to ease from its peak, with higher interest rates helping to rebalance demand and supply across the Australian economy. Data for the June quarter signaled ongoing progress, though underlying pressures persist in certain sectors.
          ● Trimmed mean inflation for the June quarter likely remained near 2.9% and headline CPI around 2.4%, both within the RBA’s 2–3% target range. The Board noted further evidence of inflation convergence, but flagged that not all price categories are moving in tandem.
          ● Financial markets have shown increased volatility in the wake of global tariff and trade policy developments—especially as a result of recent U.S. and EU announcements. This has pushed asset prices higher but contributed to an uncertain outlook for domestic growth and employment.
          ● Private domestic demand showed a tentative recovery. Real household incomes improved and signs of easing household financial stress emerged, but some business sectors continued to face subdued demand, limiting their ability to pass on cost increases.
          ● Labour market conditions remained tight overall. Employment continued to expand, with low rates of underutilization. Business surveys suggest labour availability remains a constraint, though there are signs of a gradual easing compared to earlier in 2025.
          ● Underlying wage growth softened modestly, though unit labour cost growth remains elevated due to below-trend productivity gains. The Board remains attentive to developments in wage and productivity dynamics as cost pressures continue to evolve.
          ● Uncertainties persist for both domestic activity and inflation. Consumption growth has risen, but more slowly than anticipated three months ago, with global and domestic factors both contributing to the cautious outlook.
          ● There remains a risk that household spending picks up more slowly than forecast, which could result in ongoing subdued aggregate demand and a sharper deterioration in employment conditions.
          ● Given that inflation is expected to remain around the target band, the Board judged that it was appropriate to keep policy settings unchanged in July, maintaining a position that is still mildly restrictive.
          ● The Board continues to monitor all incoming data and assesses risks carefully, with a focus on global trends, domestic demand indicators, inflation outcomes, and the labour market outlook.
          ● The RBA remains committed to its mandate of price stability and full employment and stands ready to adjust policy as needed to achieve these objectives.
          ● The next meeting is on 11 to 12 August 2025.
          Next 24 Hours Bias

          Weak Bearish

          The Kiwi Dollar (NZD)

          The NZD is moderately bearish as of Wednesday, pressured by rising expectations of an RBNZ rate cut, global trade headwinds (especially new U.S. tariffs), and subdued domestic economic momentum. Markets are defensive awaiting the Q2 jobs report and central bank policy updates, with risks skewed to further downside if local or external data disappoints. The New Zealand Dollar remains weak, trading at $0.589 against the U.S. dollar, near two-month lows and down roughly 1.8% over the past month. The currency has been in a mild downtrend ahead of crucial Q2 labor data, with the market anticipating a higher jobless rate and slower wage growth.

          Central Bank Notes:

          ● The Monetary Policy Committee (MPC) agreed to hold the Official Cash Rate (OCR) at 3.25% on 9 July, marking the first pause following six consecutive rate cuts.
          ● The MPC cited heightened uncertainty and near-term inflation risks as reasons to wait until August for further action.
          ● Although the annual consumer price index inflation increased to 2.5% in the first quarter of 2025, it remained within the MPC’s target range of 1 to 3%, noting that the outlook for medium-term inflation pressures has evolved broadly in line with the May MPS projections.
          ● While it is expected to be near the upper end of the band in the second and third quarters of this year, easing core inflation and spare capacity in the economy should help return it toward the 2% midpoint over time.
          ● The MPC noted that, despite global factors, domestic financial conditions are evolving broadly as expected, as mortgage and deposit interest rates have continued to decline, reflecting a lower OCR, strong bank liquidity, and soft credit growth.
          ● In aggregate, GDP growth over the December and March quarters was stronger than expected, reflecting a pickup in household consumption and business investment. However, higher-frequency indicators suggest weaker-than-expected growth in April and May.
          ● Large economic policy shifts overseas and concerns about sovereign risk could result in additional financial market volatility and increased bond yields, while prolonged economic uncertainty might induce further precautionary behaviour by households and firms, slowing the domestic economic recovery.
          ● Subject to medium-term inflation pressures continuing to ease in line with the Committee’s central projections, the Committee expects to lower the OCR further, broadly consistent with the projection outlined in May.
          ● The next meeting is on 20 August 2025.

          Next 24 Hours Bias

          Weak Bearish

          The Japanese Yen (JPY)

          The Japanese yen is holding its recent gains and remains in demand as a global safe-haven, supported by cautious BOJ policy commentary, elevated global trade risks, and persistent volatility in risk assets. Daily direction for the yen is firm to bullish on Wednesday, 6 August 2025. Over the last week, the yen appreciated notably, benefiting from a global unwind of yen carry trades and rising investor risk aversion. The currency remains up over 2% from last Friday’s lows after safe-haven flows boosted demand for the yen.

          Central Bank Notes:

          ● The Policy Board of the Bank of Japan decided on 31 July, by a unanimous vote, to set the following guidelines for money market operations for the inter-meeting period:
          ● The Bank will encourage the uncollateralized overnight call rate to remain at around 0.5%.
          ● The BOJ will maintain its gradual reduction of monthly outright purchases of Japanese Government Bonds (JGBs). The scheduled amount of long-term government bond purchases will, in principle, continue to decrease by about ¥400 billion each quarter from January to March 2026, and by about ¥200 billion each quarter from April to June 2026 onward, targeting a purchase level near ¥2 trillion in January to March 2027.
          ● Japan’s economy is experiencing a moderate recovery overall, though some sectors remain sluggish. Overseas economies are generally growing moderately, but recent trade policies in major economies have introduced pockets of weakness. Exports and industrial production in Japan are essentially flat, with any uptick largely driven by front-loaded demand ahead of U.S. tariff increases.
          ● On the price front, the year-on-year rate of change in consumer prices (excluding fresh food) remains in the mid-3% range. This reflects continued wage pass-through, previous import cost surges, and further increases in food prices, particularly rice. Expectations for future inflation have begun to rise moderately.
          ● The effects of the earlier import price and food cost increases are expected to fade during the outlook period. There may be a temporary stagnation in core inflation as overall growth momentum softens.
          ● Looking forward, the economy is likely to see a slower growth pace in the near term as overseas economies feel the pinch of ongoing global trade policies, putting downward pressure on Japanese corporate profits. Accommodative financial conditions are expected to buffer these headwinds somewhat. In the medium term, as global growth recovers, Japan’s growth rate is also expected to improve.
          ● With renewed economic expansion, intensifying labor shortages, and a steady rise in medium- to long-term expected inflation rates, core inflation is projected to gradually pick up. By the latter half of the BOJ’s projection period, inflation is forecast to move in line with the 2% price stability target.
          ● There are multiple risks to the outlook, with especially elevated uncertainty regarding the future path of global trade policies and overseas price trends. The BOJ will continue to closely monitor their impact on financial and foreign exchange markets, as well as on Japan’s economy and inflation.
          ● The next meeting is scheduled for 17 to 18 September 2025.

          Next 24 Hours BiasStrong Bullish

          Oil

          Oil prices are under clear pressure on August 6, 2025, as the market digests a major OPEC+ output hike and renewed geopolitical tensions from U.S. sanctions threats and ongoing Russian supply risks. The near-term outlook remains weak to bearish, barring a meaningful supply disruption or positive surprise in macroeconomic data.OPEC+ agreed to increase production by 547,000 barrels per day for September, completing the reversal of previous supply cuts. The significant rise in OPEC+ supply is a primary factor weighing on prices as traders now fear a burgeoning glut, especially amid signs of softer global demand.Next 24 Hours Bias

          Weak Bearish

          Source: IC Markets

          To stay updated on all economic events of today, please check out our Economic calendar
          Risk Warnings and Disclaimers
          You understand and acknowledge that there is a high degree of risk involved in trading. Following any strategies or investment methods may lead to potential losses. The content on the site is provided by our contributors and analysts for information purposes only. You are solely responsible for determining whether any trading assets, securities, strategy, or any other product is suitable for investing based on your own investment objectives and financial situation.
          Add to Favorites
          Share
          FastBull
          Copyright © 2026 FastBull Ltd

          728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG

          TelegramInstagramTwitterfacebooklinkedin
          App Store Google Play Android Windows
          Products
          Charts

          Chats

          Q&A with Experts
          Screeners
          Economic Calendar
          Data
          Tools
          Membership
          Features
          Function
          Markets
          Copy Trading
          Latest Signals
          Contests
          24/7
          Analysis
          Education
          Company
          Careers
          About Us
          Contact Us
          Advertising
          Download FastBull
          Help Center
          Feedback
          User Agreement
          Privacy Policy
          Personal Information Protection Statement
          Business

          White Label

          Broker API

          Data API

          Web Plug-ins

          Poster Maker

          Affiliate Program

          Risk Disclosure

          The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.

          No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.

          Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.

          Not Logged In

          Log in to access more features

          Connect Broker
          Become a signal provider
          Help Center
          Customer Service
          Dark Mode
          Price Up/Down Colors

          Log In

          Sign Up

          Position
          Layout
          Fullscreen
          Default to Chart
          The chart page opens by default when you visit fastbull.com