• Trade
  • Markets
  • Copy
  • Contests
  • 24/7
  • Calendar
  • Q&A
  • Chats
Screeners
SYMBOL
LAST
BID
ASK
HIGH
LOW
NET CHG.
%CHG.
SPREAD
SOURCE
SPX
S&P 500 Index
7743.40
7743.40
7743.40
7752.08
7693.07
+39.27
+ 0.51%
--
--
DJI
Dow Jones Industrial Average
51828.61
51828.61
51828.61
51874.95
51339.25
+478.63
+ 0.93%
--
--
IXIC
NASDAQ Composite Index
27068.71
27068.71
27068.71
27122.76
26876.27
+129.34
+ 0.48%
--
--
USDX
US Dollar Index
100.740
100.740
100.820
101.010
100.560
-0.200
-0.20%
--
--
EURUSD
Euro / US Dollar
1.13891
1.13891
1.13924
1.14112
1.13680
+0.00101
+ 0.09%
--
--
GBPUSD
Pound Sterling / US Dollar
1.32419
1.32419
1.32491
1.32631
1.32085
+0.00247
+ 0.19%
--
--
XAUUSD
Gold / US Dollar
4284.85
4284.85
4284.85
4315.57
4254.29
+10.59
+ 0.25%
--
--
WTI
Light Sweet Crude Oil
91.319
91.319
91.413
93.606
90.344
-2.502
-2.67%
--
--

Community Accounts

Signal Accounts
--
Profit Accounts
--
Loss Accounts
--
View More

Become a signal provider

Sell trading signals to earn additional income

View More

Guide to Copy Trading

Get started with ease and confidence

View More

Signal Accounts for Members

All Signal Accounts

Best Return
  • Best Return
  • Best P/L
  • Best MDD
Past 1W
  • Past 1W
  • Past 1M
  • Past 1Y

All Contests

  • All
  • Recommend
  • Stocks
  • Cryptocurrencies
  • Central Banks
  • Trump Updates
  • Featured News
Top News Only
Share

According To Yonhap News Agency: South Korean President Lee Jae-myung Has Concluded His Trip To The United States And Mexico And Departed For Home

Share

Japan's Ministry Of Foreign Affairs: U.S. President Donald Trump And Japanese Prime Minister Sanae Takaichi Had A Phone Conversation Of About 20 Minutes At 12:00 GMT On Saturday (20:00 Beijing Time On Saturday)

Share

Terry Branstad, Chairman Of The US‑China Business Council: Sino‑U.S. Economic And Trade Relations Are Of Paramount Importance And Indispensable

Share

Head Of AmCham Shanghai: China-U.S. Relations Downgraded To Second-Biggest Challenge For Companies In China

Share

Yuyuantan Sky: Sino-U.S. Relations Require An Answer That Transcends Time

Share

US President Trump: We Have The Best Financial Data In History, But The Fake News Media Refuse To Report It

Share

Cuban Foreign Minister: The U.S.'s Continued Embargo Against Cuba Constitutes “collective Punishment”

Share

Russian Foreign Minister: The Situation In The West Bank Is Rapidly Deteriorating

Share

Russia Claims To Have Gained Control Of Several Settlements, While Ukraine Says It Has Launched Multiple Offensives

Share

Saudi Arabia Says The Strait Of Hormuz Must Be Restored To Its "pre-conflict Status."

Share

US President Trump: If The Republicans Win, All Adults Will Receive A $5,000 Bonus, While The Democrats Will Not

Share

The Southern Theater Command Of The Chinese People's Liberation Army Conducted Joint Sea And Air Exercises In The Maritime And Aerial Areas Surrounding Huangyan Island

Share

U.S. Media: U.S. And Russia Jointly Amend AI Weapons Agreement, Removing Numerous Safeguard Provisions

Share

Iran's "Persian Gulf Strait Authority": Shipowners Must Remain Vigilant Against Such Illegal Activities By Certain Charterers. Once Verified, The Relevant Charterers Will Be Placed On A "non-compliance List," And Transit Through The Strait Of Hormuz For All Vessels Under Their Name Will Be Restricted

Share

Iran's Persian Gulf Straits Authority Reports That Some Charterers Are Forcing Vessels To Use "illegal Routes." This Not Only Exposes Ships, Owners, Captains, And Crew To Economic Losses And Life Risks, But Also Severely Restricts Their Future Ability To Transit The Strait Of Hormuz

Share

Iranian Foreign Minister Araqchi: Only A Solution Reached Through Negotiations Can Break The Deadlock, And That Is Our Position

Share

Iranian Foreign Minister Araqchi: Our Conditions Are Very Clear, And Any Move To Reopen The Strait Of Hormuz Depends On The Fulfillment Of These Conditions

Share

Iranian Foreign Minister Araqchi: We Have Seen The Initial Response From The US President To Iran's Proposal, But The Mediators Have Not Yet Conveyed Any Information To US. We Are Waiting For The Mediators To Convey Their Specific Opinions And Will Make A Decision Accordingly

Share

Canadian Prime Minister Mark Carney: Vietnam Is Canada's Largest Trading Partner In ASEAN. This Week, We Further Deepened This Partnership, Aiming To Create More Opportunities For Canadian Businesses In One Of The World's Fastest-growing Consumer Markets

Share

St. Louis Federal Reserve: Financial Market Stress Levels Eased Slightly In The Week Ending September 18 Compared To The Previous Week. The St. Louis Fed Financial Stress Index Recorded -0.91, Compared To -0.85 The Previous Week

TIME
ACT
FCST
PREV
IMPACT
U.S. Weekly Initial Jobless Claims (SA)

A:--

F: --

P: --
XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
FOMC Member Hammack Speaks
U.S. Annual Total New Home Sales (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. New Home Sales Annualized MoM (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Philadelphia Fed President Henry Paulson delivers a speech
U.S. EIA Weekly Natural Gas Stocks Change

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
U.S. Kansas Fed Manufacturing Production Index (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Kansas Fed Manufacturing Composite Index (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Mexico Policy Interest Rate

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Treasuries Held by Foreign Central Banks

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.K. GfK Consumer Confidence Index (Sept)

A:--

F: --

P: --

GBPUSD
  • GBPUSD
  • XAUUSD
  • XAGUSD
  • WTI
Germany GfK Consumer Confidence Index (SA) (Oct)

A:--

F: --

P: --
EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone 3-Month M3 Money Supply YoY (Aug)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone M3 Money Supply YoY (Aug)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Euro Zone Private Sector Credit YoY (Aug)

A:--

F: --

P: --

EURUSD
  • EURUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
New York Federal Reserve President Williams delivered a speech.
India Deposit Gowth YoY

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
Mexico Unemployment Rate (Not SA) (Aug)

A:--

F: --

P: --

XAUUSD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Durable Goods Orders MoM (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Durable Goods Orders MoM (Excl.Transport) (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Non-Defense Capital Durable Goods Orders MoM (Excl. Aircraft) (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. Durable Goods Orders MoM (Excl. Defense) (SA) (Aug)

A:--

F: --

P: --
USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. UMich Current Economic Conditions Index Final (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. UMich Consumer Expectations Index Final (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. UMich Consumer Sentiment Index Final (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
U.S. UMich 1-Year-Ahead Inflation Expectations Final (Sept)

A:--

F: --

P: --

USDX
  • USDX
  • XAUUSD
  • XAGUSD
  • WTI
Canada Federal Government Budget Balance (Jul)

A:--

F: --

P: --

USDCAD
  • USDCAD
  • XAUUSD
  • XAGUSD
  • WTI
  • USDX
U.S. Weekly Total Oil Rig Count

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
U.S. Weekly Total Rig Count

A:--

F: --

P: --

WTI
  • WTI
  • XAUUSD
  • XAGUSD
  • USDX
FOMC Member Hammack Speaks
China, Mainland Industrial Profit YoY (YTD) (Aug)

--

F: --

P: --

India Manufacturing Output MoM (Aug)

--

F: --

P: --

India Industrial Production Index YoY (Aug)

--

F: --

P: --

Brazil Current Account (Aug)

--

F: --

P: --

Mexico Trade Balance (Aug)

--

F: --

P: --

Canada National Economic Confidence Index

--

F: --

P: --

U.S. Dallas Fed General Business Activity Index (Sept)

--

F: --

P: --

U.S. Dallas Fed New Orders Index (Sept)

--

F: --

P: --

U.K. BRC Shop Price Index YoY (Sept)

--

F: --

P: --

Australia Overnight (Borrowing) Key Rate

--

F: --

P: --

RBA Rate Statement
RBA Press Conference
Turkey Economic Sentiment Indicator (Sept)

--

F: --

P: --

U.K. M4 Money Supply YoY (Aug)

--

F: --

P: --

U.K. Mortgage Lending (Aug)

--

F: --

P: --

U.K. M4 Money Supply MoM (Aug)

--

F: --

P: --

U.K. Mortgage Approvals (Aug)

--

F: --

P: --

Euro Zone Consumer Confidence Index Final (Sept)

--

F: --

P: --

Euro Zone Services Sentiment Index (Sept)

--

F: --

P: --

Euro Zone Economic Sentiment Indicator (Sept)

--

F: --

P: --

Euro Zone Industrial Climate Index (Sept)

--

F: --

P: --

Italy PPI YoY (Aug)

--

F: --

P: --

Euro Zone Consumer Inflation Expectations (Sept)

--

F: --

P: --

Euro Zone Selling Price Expectations (Sept)

--

F: --

P: --

France Unemployment Class-A (Aug)

--

F: --

P: --

Brazil Unemployment Rate (Aug)

--

F: --

P: --

Canada GDP YoY (Jul)

--

F: --

P: --

Canada GDP MoM (SA) (Jul)

--

F: --

P: --

U.S. Weekly Redbook Index YoY

--

F: --

P: --

U.S. FHFA House Price Index (Jul)

--

F: --

P: --

U.S. S&P/CS 20-City Home Price Index YoY (Not SA) (Jul)

--

F: --

P: --

Q&A with Experts
    • All
    • Chatrooms
    • Groups
    • Friends
    1999kk.king flag
    Areeba Mini❣️❣️ flag
    Osaghae Cephas
    @Areeba Mini❣️❣️what's ur bias on gold open tommorow night buys or sells or are u still holding ur sells?
    @Osaghae Cephas4220::4200⬇️✅
    1999kk.king flag
    00:04
    sanjeev flag
    1999kk.king flag
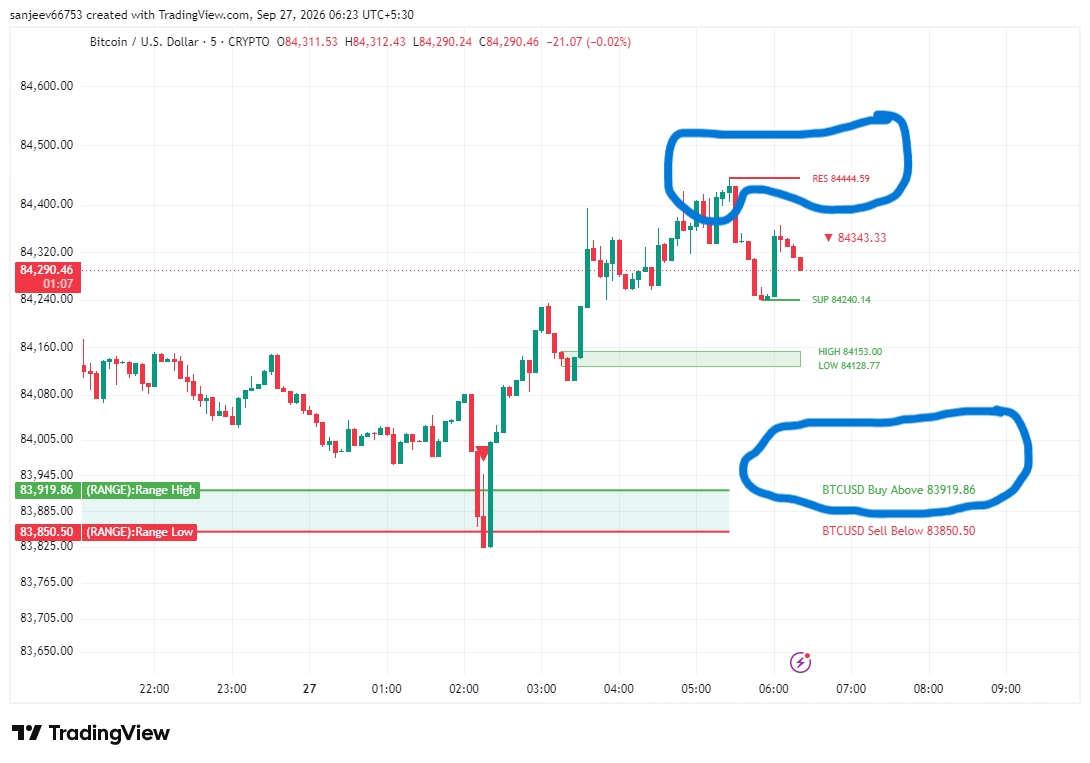
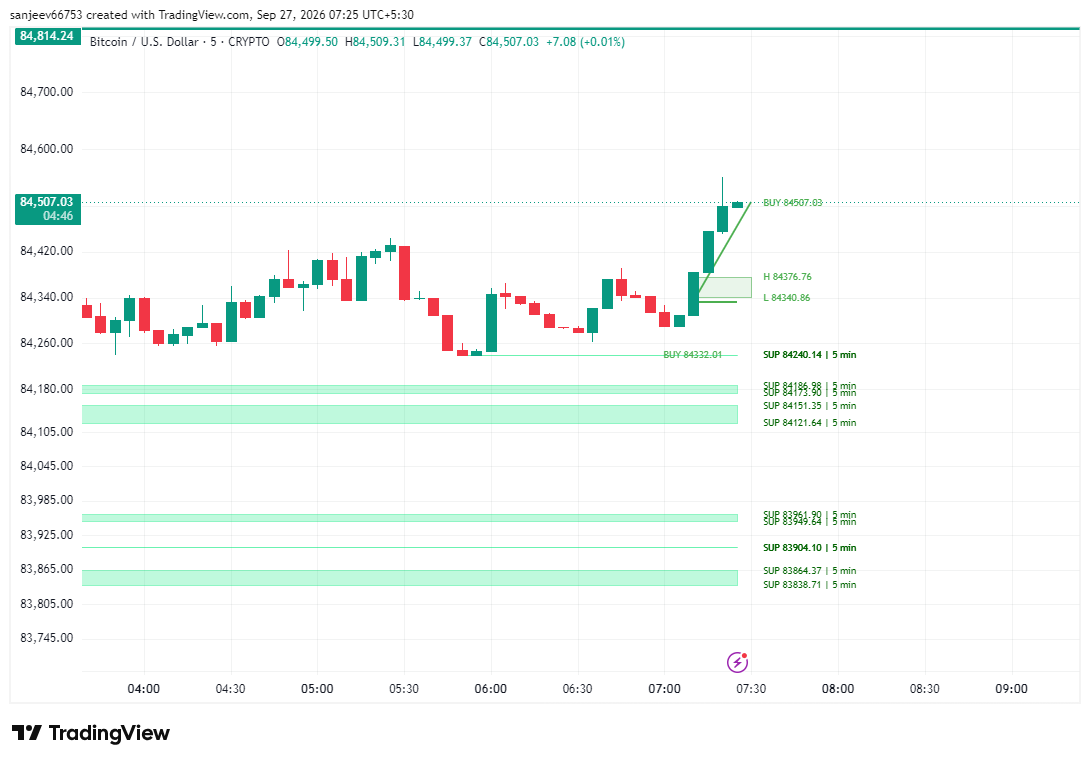
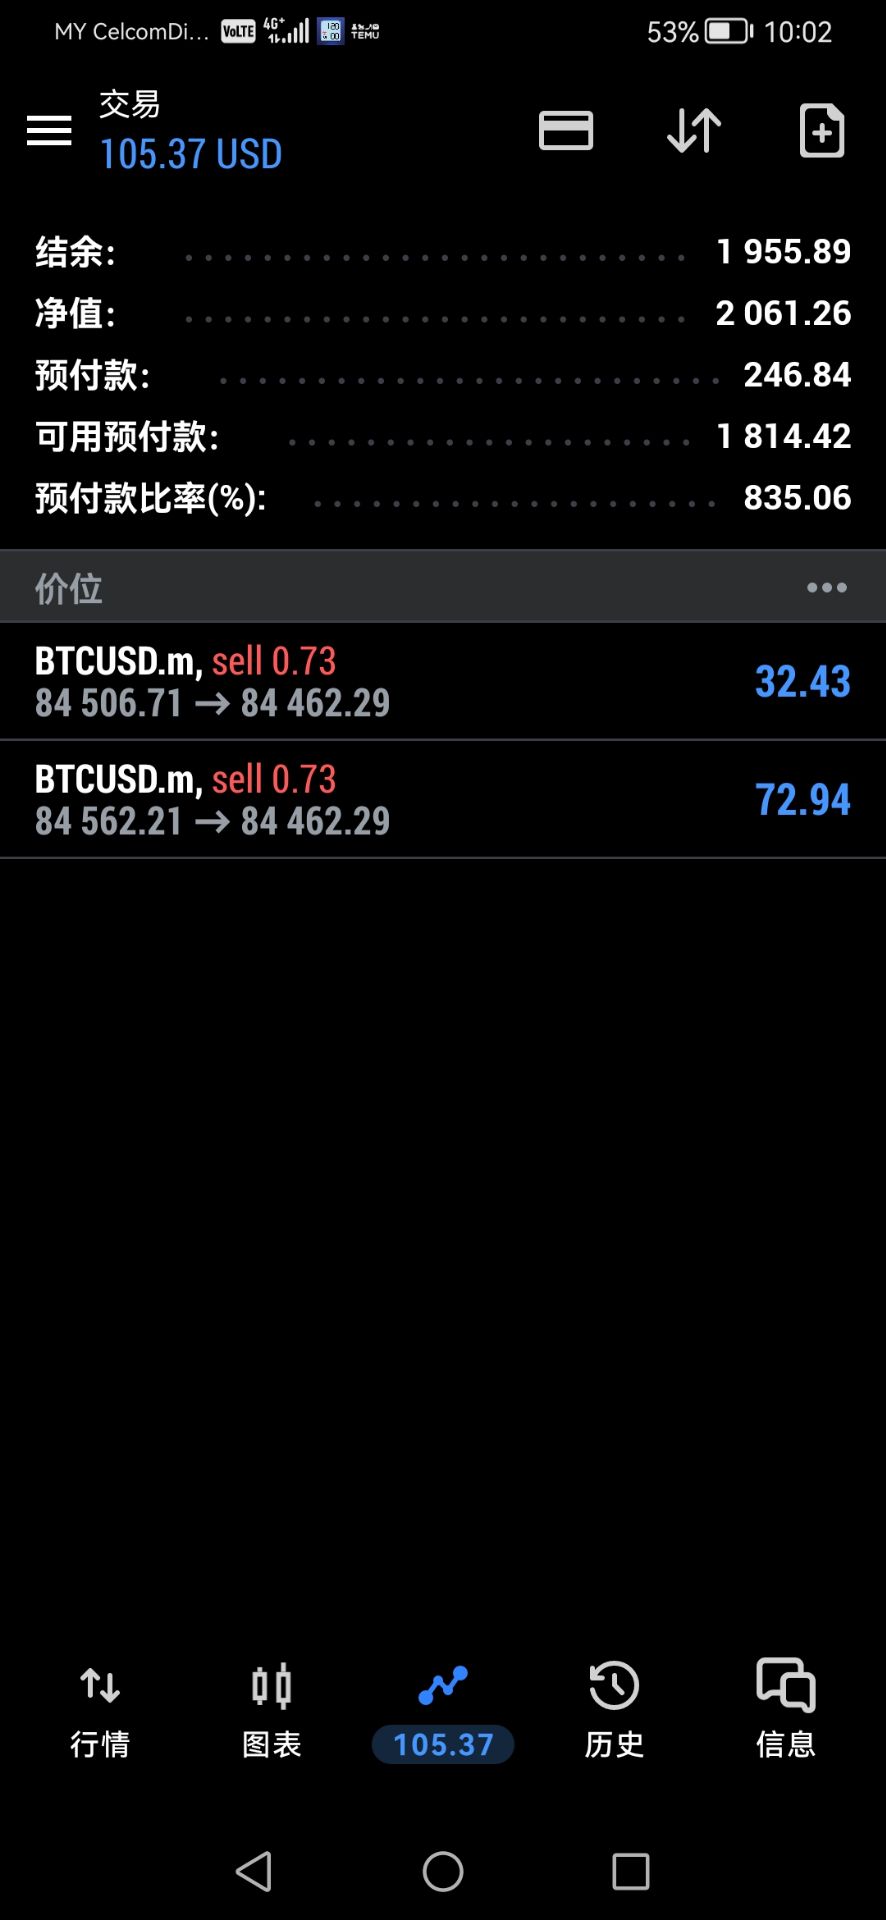
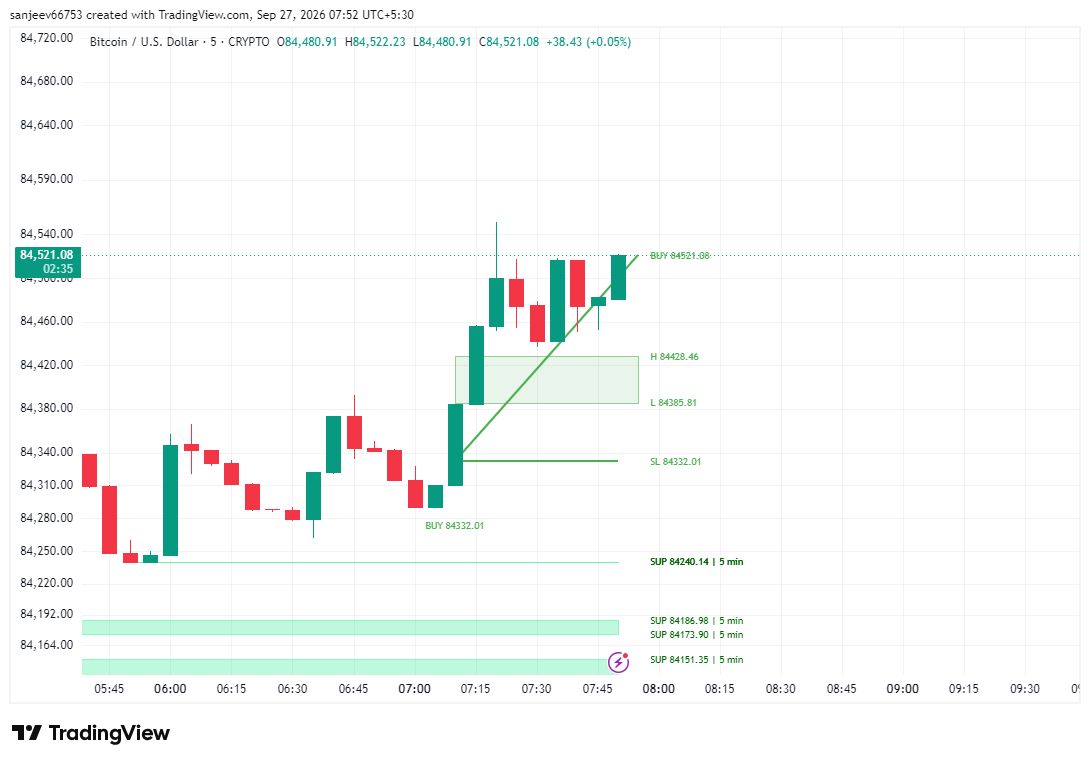
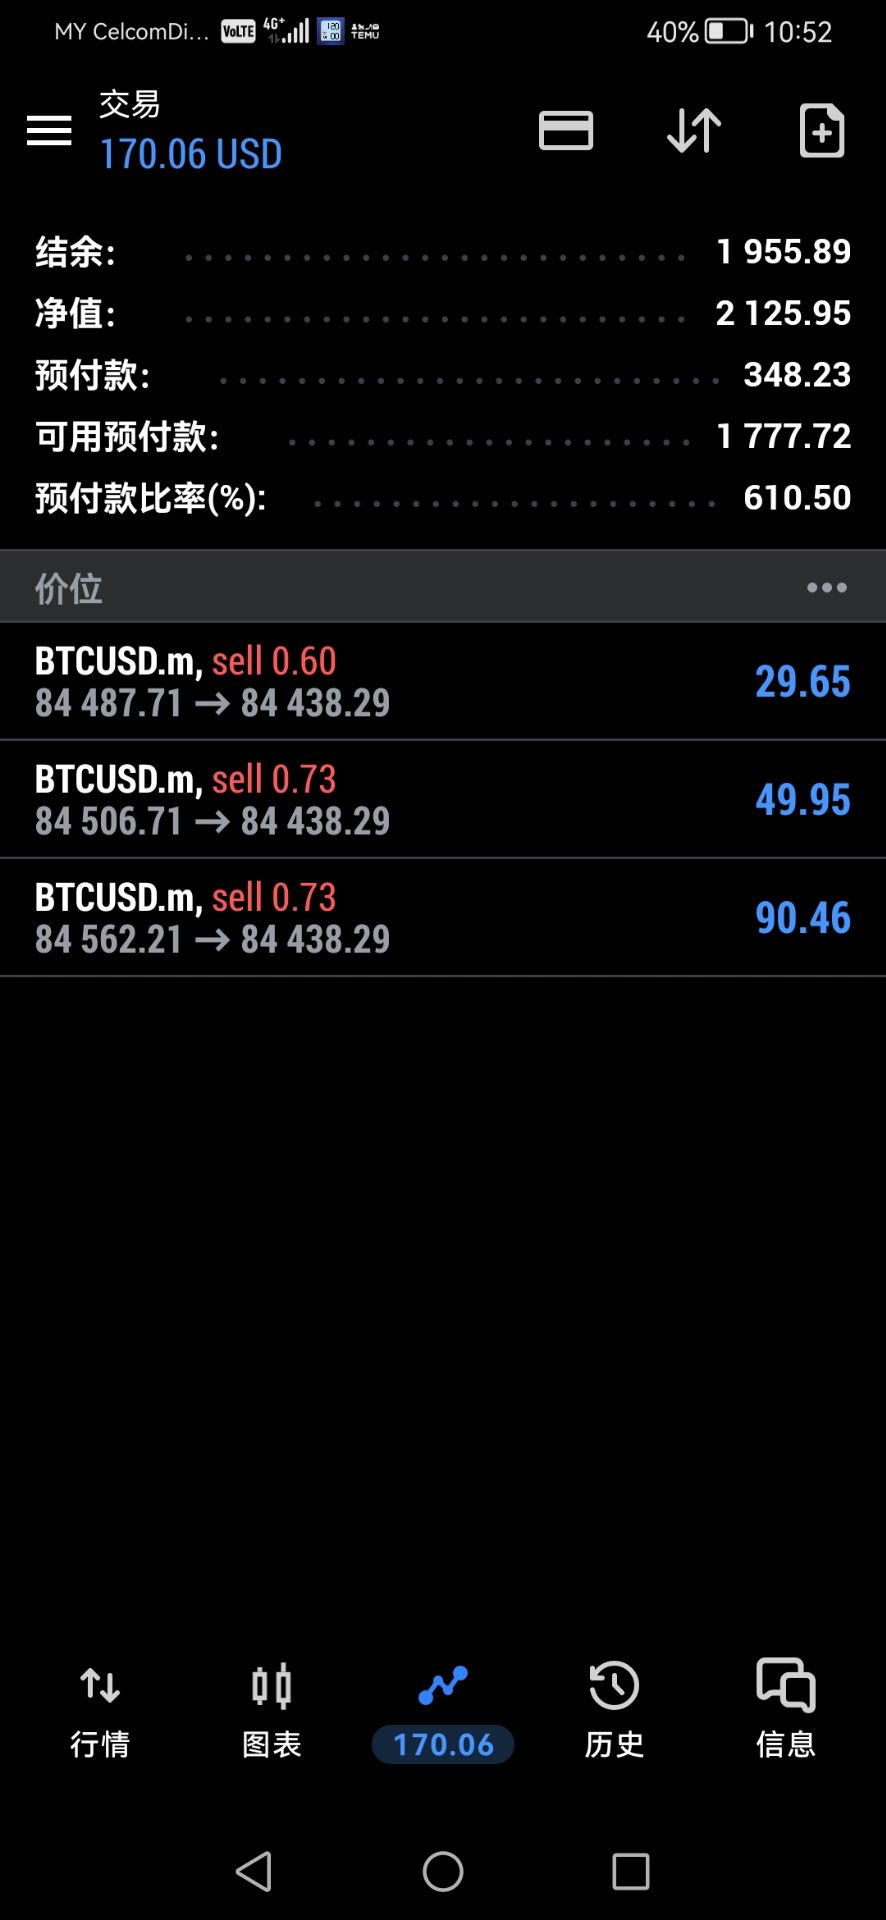
    84456tptp。了
    1999kk.king flag
    84500 sell sell sell
    1999kk.king flag
    on
    1999kk.king flag
    sell
    1999kk.king flag
    tp84320
    sanjeev flag
    1999kk.king flag
    1999kk.king flag
    sanjeev flag
    sanjeev
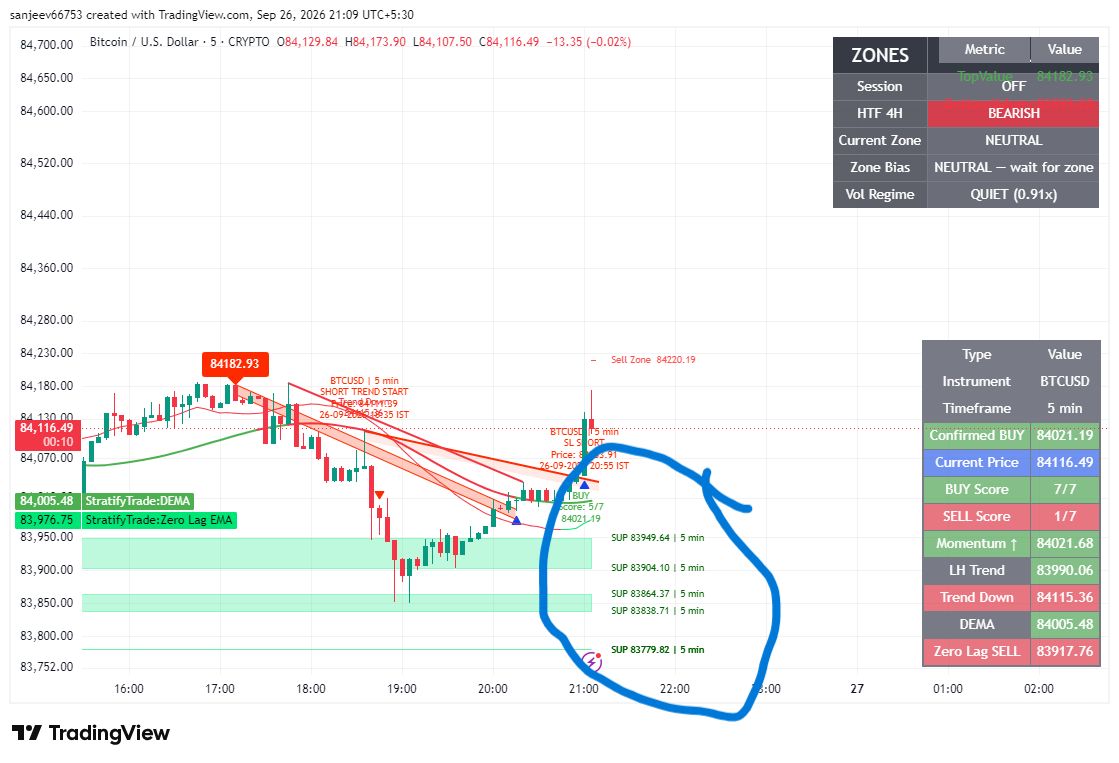
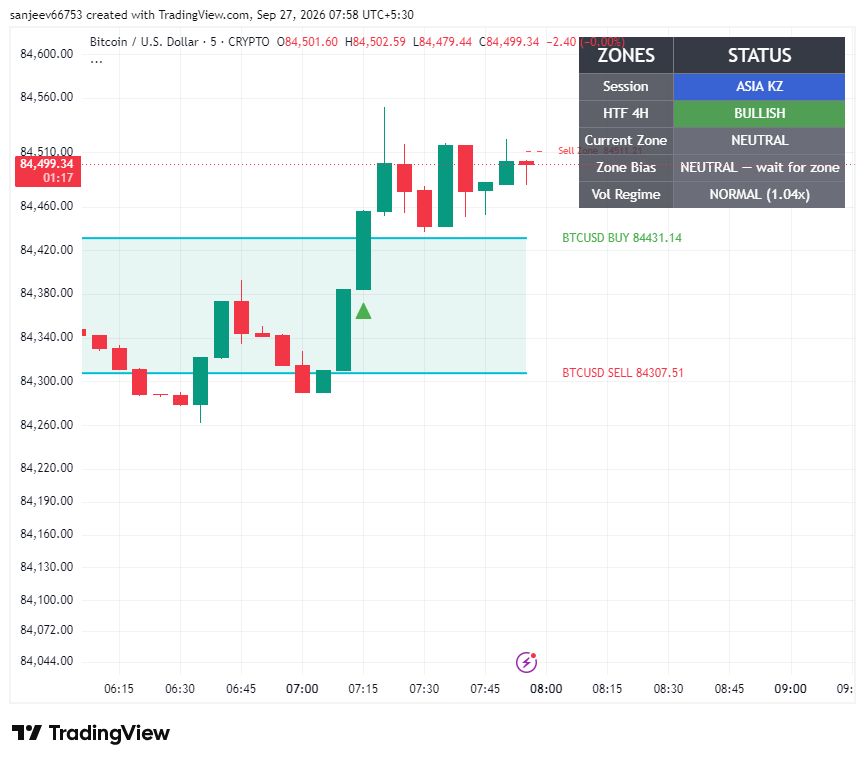
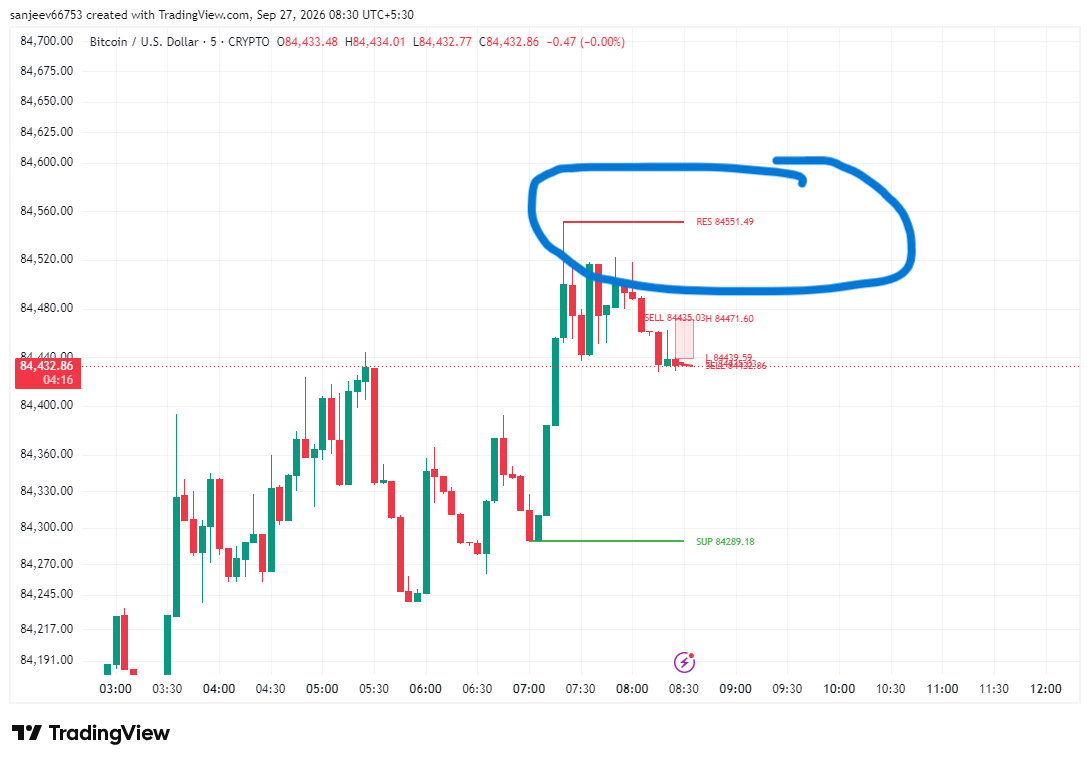
    buyers for now firmly at 84034.sellers trying hard at 84136.but immeditely kicked out by buyers. for now.lets see what happens.cmp 84138
    sanjeev flag
    sanjeev flag
    sanjeev
    high 84500 plus till now
    sanjeev flag
    1999kk.king flag
    1999kk.king flag
    Treder12 flag
    nfp buy atau sel
    sanjeev flag
    Type here...
    Add Symbol or Code

      No matching data

      All
      Recommend
      Stocks
      Cryptocurrencies
      Central Banks
      Trump Updates
      Featured News
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint
      • All
      • Russia-Ukraine Conflict
      • Middle East Flashpoint

      Search
      Products

      Charts Free Forever

      Chats Q&A with Experts
      Screeners Economic Calendar Data Tools
      Membership Features
      Data Warehouse Market Trends Institutional Data Policy Rates Macro

      Market Trends

      Market Sentiment Order Book Forex Correlations

      Top Indicators

      Charts Free Forever
      Markets

      News

      24/7 Analysis Education

      Latest Views

      Latest Update

      Signals

      Copy Rankings Latest Signals Become a signal provider AI Rating
      Contests
      Brokers

      Overview Brokers Assessment Rankings Regulators News Claims
      Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
      Q&A Complaint Scam Alert Videos Tips to Detect Scam
      More

      Business
      Events
      Careers About Us Advertising Help Center

      White Label

      Broker API

      Data API

      Web Plug-ins

      Affiliate Program

      Awards Institution Evaluation IB Seminar Salon Event Exhibition
      Vietnam Thailand Singapore Dubai
      Fans Party Investment Sharing Session
      FastBull Summit BrokersView Expo
      Recent Searches
        Top Searches
          Markets
          Analysis
          User
          24/7
          Economic Calendar
          Education
          Data
          • Names
          • Latest
          • Prev

          View All

          No data

          Scan to Download

          Faster Charts, Chat Faster!

          Download
          English
          • English
          • Español
          • العربية
          • Bahasa Indonesia
          • Bahasa Melayu
          • Tiếng Việt
          • ภาษาไทย
          • Français
          • Italiano
          • Türkçe
          • Русский язык
          • 简中
          • 繁中
          Open Account
          Search
          Products
          Charts Free Forever
          Markets
          News
          Signals

          Copy Rankings Latest Signals Become a signal provider AI Rating
          Contests
          Brokers

          Overview Brokers Assessment Rankings Regulators News Claims
          Broker listing Forex Brokers Comparison Tool Live Spread Comparison Scam
          Q&A Complaint Scam Alert Videos Tips to Detect Scam
          More

          Business
          Events
          Careers About Us Advertising Help Center

          White Label

          Broker API

          Data API

          Web Plug-ins

          Affiliate Program

          Awards Institution Evaluation IB Seminar Salon Event Exhibition
          Vietnam Thailand Singapore Dubai
          Fans Party Investment Sharing Session
          FastBull Summit BrokersView Expo

          IC Markets Asia Fundamental Forecast | 05 September 2025

          IC Markets

          Commodity

          Forex

          Economic

          Summary:

          The overnight US session was dominated by weak labor market data that solidified expectations for a 25 basis point Fed rate cut on September 17, with markets now pricing in a 96-98% probability.

          What happened in the U.S session?

          The overnight US session was dominated by weak labor market data that solidified expectations for a 25 basis point Fed rate cut on September 17, with markets now pricing in a 96-98% probability. The combination of disappointing ADP employment figures, rising jobless claims, and declining job openings created a dovish environment that benefited rate-sensitive assets like gold and growth stocks, while pressuring the US dollar and oil prices. Tech giants Alphabet and Apple were the session’s biggest winners due to favorable regulatory developments, while Treasury yields declined across the curve as investors positioned for monetary easing.

          What does it mean for the Asia sessions?

          Friday’s trading will be dominated by US employment data, which could solidify or derail Fed rate cut expectations for September 17. Asian traders should particularly watch for any surprises in the NFP numbers, as this could trigger significant moves in USD pairs and global risk sentiment. The combination of potential Fed easing, Chinese market intervention concerns, and ongoing trade uncertainties creates a complex but potentially volatile environment for Asian markets. Oil’s continued decline and gold’s strength reflect the current risk-off sentiment, while emerging market currencies appear positioned to benefit from dollar weakness if the Fed proceeds with cuts as expected.

          The Dollar Index (DXY)

          The US dollar enters Friday’s crucial employment data release from a position of significant technical and fundamental weakness. With Fed rate cuts appearing increasingly certain and political pressures mounting, the dollar faces its most challenging period in years. The September 5th jobs report will likely determine whether the current weakness accelerates or if seasonal patterns provide temporary relief for the beleaguered greenback.Central Bank Notes:

          ● The Board of Governors of the Federal Reserve System voted unanimously to maintain the Federal Funds Rate in a target range of 4.25% to 4.50% at its meeting on July 29–30, 2025, keeping policy unchanged for the fifth consecutive meeting.
          ● The Committee reiterated its objective of achieving maximum employment and inflation at the rate of 2% over the longer run. While uncertainty around the economic outlook has diminished since earlier in the year, the Committee notes that challenges remain and continued vigilance is warranted.
          ● Policymakers remain highly attentive to risks on both sides of their dual mandate. The unemployment rate remains low, near 4.2%–4.5%, and labor market conditions are described as solid. However, inflation remains somewhat elevated, with the PCE price index at 2.6% and a core inflation forecast of 3.1% for year-end 2025, up from earlier projections; tariff-related pressures are cited as a contributing factor.
          ● The Committee acknowledged that recent economic activity has expanded at a solid pace, with second-quarter annualized growth estimates near 2.4%. However, GDP growth for 2025 has been revised downward to 1.4% (from 1.7% projected in March), reflecting expectations of a slowdown in the coming quarters.
          ● In the revised Summary of Economic Projections, the unemployment rate is expected to average 4.5% in 2025, and headline PCE inflation is forecast at 3.0% for the year, with core PCE at 3.1%. Policymakers continue to anticipate that inflation will moderate gradually, with ongoing risks from tariffs and global conditions.
          ● The Committee reaffirmed its data-dependent and risk-aware approach to future policy decisions. Officials stated they are prepared to adjust the stance of monetary policy as appropriate if risks emerge that could impede progress toward the Fed’s goals.
          ● As previously outlined, the Committee continues the measured run-off of its securities holdings. The pace of balance sheet reduction, which slowed since April (monthly redemption cap on Treasury securities reduced from $25B to $5B, while holding agency MBS cap steady at $35B), was left unchanged this month to support orderly market functioning and financial conditions.
          ● The next meeting is scheduled for 16 to 17 September 2025.

          Next 24 Hours Bias

          Medium Bullish

          Gold (XAU)

          Gold enters Friday, September 5, 2025, in a powerful position, supported by multiple bullish catalysts, including Fed easing expectations, political uncertainty around central bank independence, robust institutional demand, and technical momentum. The day’s NFP release will determine whether gold can break to new all-time highs or experience a temporary consolidation. With Goldman Sachs forecasting potential moves to $4,000-$5,000 and technical indicators remaining bullish, the precious metal appears well-positioned for continued gains despite already significant year-to-date performance of over 40%.Next 24 Hours Bias

          Strong Bullish

          The Australian Dollar (AUD)

          The Australian Dollar enters September 5, 2025, supported by strong fundamentals including robust GDP growth, record trade surpluses, and improving China relations. However, the currency faces near-term headwinds from rising domestic inflation that has effectively ruled out a September RBA rate cut, technical resistance levels, and mixed commodity price performance. The key drivers to watch include upcoming US employment data, Fed policy decisions, Chinese economic indicators, and Australia’s next inflation readings.Central Bank Notes:

          ● The RBA held its cash rate steady at 3.85% at the August meeting on 11–12 August 2025, maintaining its stance after keeping rates unchanged in July. The decision was widely expected, reflecting confidence that inflation is settling sustainably within the target.
          ● Inflation continues to moderate, though headline outcomes for the September quarter are not yet available. Timely indicators suggest price pressures in housing-related services and insurance remain elevated, even as tradables inflation stays subdued.
          ● The RBA’s preferred measure, trimmed mean inflation, is estimated to track close to 2.8 — 2.9%, signaling continued progress toward the midpoint of the 2–3% target range. Headline CPI is likely near 2.3%, subject to volatility in energy and food prices.
          ● Global conditions remain a source of uncertainty. The market reaction to ongoing U.S.–EU trade frictions has tempered slightly, but volatility persists across equity and commodity markets. These developments continue to feed into Australia’s trade outlook and business sentiment.
          ● Domestic demand showed further signs of recovery. Household consumption strengthened modestly over the winter months, helped by improving real incomes and a stabilizing housing market. However, business investment intentions remain mixed, with service industries stronger than manufacturing and construction.
          ● Labour market conditions remain relatively tight, but indicators point to reduced momentum compared with the first half of 2025. Job vacancies have eased, and while employment growth continues, underutilization edged slightly higher for the first time this year.
          ● Wage growth has moderated further, consistent with easing labour demand, though unit labour costs remain above average due to weak productivity performance. The RBA continues to flag productivity as a medium-term risk to cost dynamics.
          ● Forward-looking indicators suggest consumption growth may be softer than previously assumed, with households cautious despite modest income gains. Elevated rents and high borrowing costs continue to weigh on discretionary spending.
          ● The Board reasserted the risk that household spending may underperform forecasts, potentially dampening business conditions and leading to weaker labour demand if confidence fails to strengthen.
          ● The overall stance of monetary policy remains mildly restrictive, consistent with inflation outcomes near target and ongoing progress toward balance in the economy. The Board judged it prudent to leave rates unchanged, while emphasizing that adjustments remain contingent on incoming data.
          ● The Reserve Bank reaffirmed its commitment to price stability and full employment, noting its readiness to adjust settings if conditions diverge materially from baseline projections.
          ● The next meeting is on 8 to 9 September 2025.Next 24 Hours Bias
          Medium Bullish

          The Kiwi Dollar (NZD)

          The New Zealand Dollar (NZD) continues to face downward pressure on Friday, September 5, 2025, trading around 0.5835-0.5840 against the US Dollar. The Kiwi has weakened 0.74% from the previous session and is down 6.19% over the past 12 months. Despite some recent positive momentum earlier in the week, the NZD remains under pressure from dovish RBNZ policy expectations and broader market uncertainty ahead of key US employment data.Central Bank Notes:

          ● The Monetary Policy Committee (MPC) agreed to cut the Official Cash Rate (OCR) by 25 basis points to 3.00% on 20 August 2025, marking a three-year low and continuing the easing cycle after July’s pause. The vote was split 4-2, with two members advocating a 50-basis-point cut, highlighting diverging views within the Committee.
          ● Policymakers indicated that significant uncertainty and a stalling economic recovery prompted this move, leaving the door open for further rate cuts later in the year, with a possible trough around 2.5% by December.
          ● Annual consumer price index inflation rose to 2.7% in the June quarter and is expected to reach 3% for the September quarter—at the upper end of the MPC’s 1 to 3% target band—but medium-term expectations remain anchored near the 2% midpoint..
          ● Despite the near-term uptick, headline inflation is projected to return toward 2% by mid-2026, as tradables inflation pressures ease and significant spare capacity continues to dampen domestic price momentum.
          ● Domestic financial conditions are broadly aligning with MPC expectations, as lower wholesale rates have translated into reduced borrowing costs for households. However, declining consumption and investment demand, higher unemployment, and subdued wage growth reflect ongoing economic slack.
          ● GDP growth stalled in the second quarter of 2025, contrasting with earlier projections. High-frequency indicators point to continued weakness driven by rising prices for essentials, weakening household savings, and constrained business lending.
          ● The MPC cautioned that ongoing global tariff uncertainties and policy shifts, especially recent changes in US trade regulations, could amplify market volatility and present both upside and downside risks to New Zealand’s recovery.
          ● Subject to medium-term inflation pressures continuing to ease as projected, the MPC signaled scope for further OCR cuts, possibly down to 2.5% by year-end, consistent with the latest Monetary Policy Statement outlook.

          ● The next meeting is on 22 October 2025.

          Next 24 Hours Bias

          Weak Bearish

          The Japanese Yen (JPY)

          The Japanese Yen faces a perfect storm of challenges heading into Friday, September 5, 2025. Political uncertainty surrounding PM Ishiba’s leadership, combined with the BoJ’s cautious monetary policy stance and persistent real wage declines, continues to undermine the currency. While inflation remains above the 2% target, the central bank appears reluctant to accelerate rate hikes amid global economic uncertainties and domestic political instability.Central Bank Notes:

          ● The Policy Board of the Bank of Japan decided on 31 July, by a unanimous vote, to set the following guidelines for money market operations for the inter-meeting period:
          ● The Bank will encourage the uncollateralized overnight call rate to remain at around 0.5%.
          ● The BOJ will maintain its gradual reduction of monthly outright purchases of Japanese Government Bonds (JGBs). The scheduled amount of long-term government bond purchases will, in principle, continue to decrease by about ¥400 billion each quarter from January to March 2026, and by about ¥200 billion each quarter from April to June 2026 onward, targeting a purchase level near ¥2 trillion in January to March 2027.
          ● Japan’s economy is experiencing a moderate recovery overall, though some sectors remain sluggish. Overseas economies are generally growing moderately, but recent trade policies in major economies have introduced pockets of weakness. Exports and industrial production in Japan are essentially flat, with any uptick largely driven by front-loaded demand ahead of U.S. tariff increases.
          ● On the price front, the year-on-year rate of change in consumer prices (excluding fresh food) remains in the mid-3% range. This reflects continued wage pass-through, previous import cost surges, and further increases in food prices, particularly rice. Expectations for future inflation have begun to rise moderately.
          ● The effects of the earlier import price and food cost increases are expected to fade during the outlook period. There may be a temporary stagnation in core inflation as overall growth momentum softens.
          ● Looking forward, the economy is likely to see a slower growth pace in the near term as overseas economies feel the pinch of ongoing global trade policies, putting downward pressure on Japanese corporate profits. Accommodative financial conditions are expected to buffer these headwinds somewhat. In the medium term, as global growth recovers, Japan’s growth rate is also expected to improve.
          ● With renewed economic expansion, intensifying labor shortages, and a steady rise in medium- to long-term expected inflation rates, core inflation is projected to gradually pick up. By the latter half of the BOJ’s projection period, inflation is forecast to move in line with the 2% price stability target.
          ● There are multiple risks to the outlook, with especially elevated uncertainty regarding the future path of global trade policies and overseas price trends. The BOJ will continue to closely monitor their impact on financial and foreign exchange markets, as well as on Japan’s economy and inflation.
          ● The next meeting is scheduled for 17 to 18 September 2025.

          Next 24 Hours BiasWeak Bearish

          Oil

          The oil market enters a critical phase as OPEC+ faces the choice between defending prices through production restraint or prioritizing market share through increased output. With the EIA projecting significant inventory builds averaging more than 2 million barrels per day in Q4 2025 and Q1 2026, the group’s September 7 decision will likely determine the market’s trajectory through year-end.

          Next 24 Hours Bias

          Medium Bearish

          Source: IC Markets

          To stay updated on all economic events of today, please check out our Economic calendar
          Risk Warnings and Disclaimers
          You understand and acknowledge that there is a high degree of risk involved in trading. Following any strategies or investment methods may lead to potential losses. The content on the site is provided by our contributors and analysts for information purposes only. You are solely responsible for determining whether any trading assets, securities, strategy, or any other product is suitable for investing based on your own investment objectives and financial situation.
          Add to Favorites
          Share
          FastBull
          Copyright © 2026 FastBull Ltd

          728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG

          TelegramInstagramTwitterfacebooklinkedin
          App Store Google Play Android Windows
          Products
          Charts

          Chats

          Q&A with Experts
          Screeners
          Economic Calendar
          Data
          Tools
          Membership
          Features
          Function
          Markets
          Copy Trading
          Latest Signals
          Contests
          24/7
          Analysis
          Education
          Company
          Careers
          About Us
          Contact Us
          Advertising
          Download FastBull
          Help Center
          Feedback
          User Agreement
          Privacy Policy
          Personal Information Protection Statement
          Business

          White Label

          Broker API

          Data API

          Web Plug-ins

          Poster Maker

          Affiliate Program

          Risk Disclosure

          The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.

          No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.

          Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.

          Not Logged In

          Log in to access more features

          Connect Broker
          Become a signal provider
          Help Center
          Customer Service
          Dark Mode
          Price Up/Down Colors

          Log In

          Sign Up

          Position
          Layout
          Fullscreen
          Default to Chart
          The chart page opens by default when you visit fastbull.com