


- WTI
- XAUUSD
- XAGUSD
- USDX



Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev




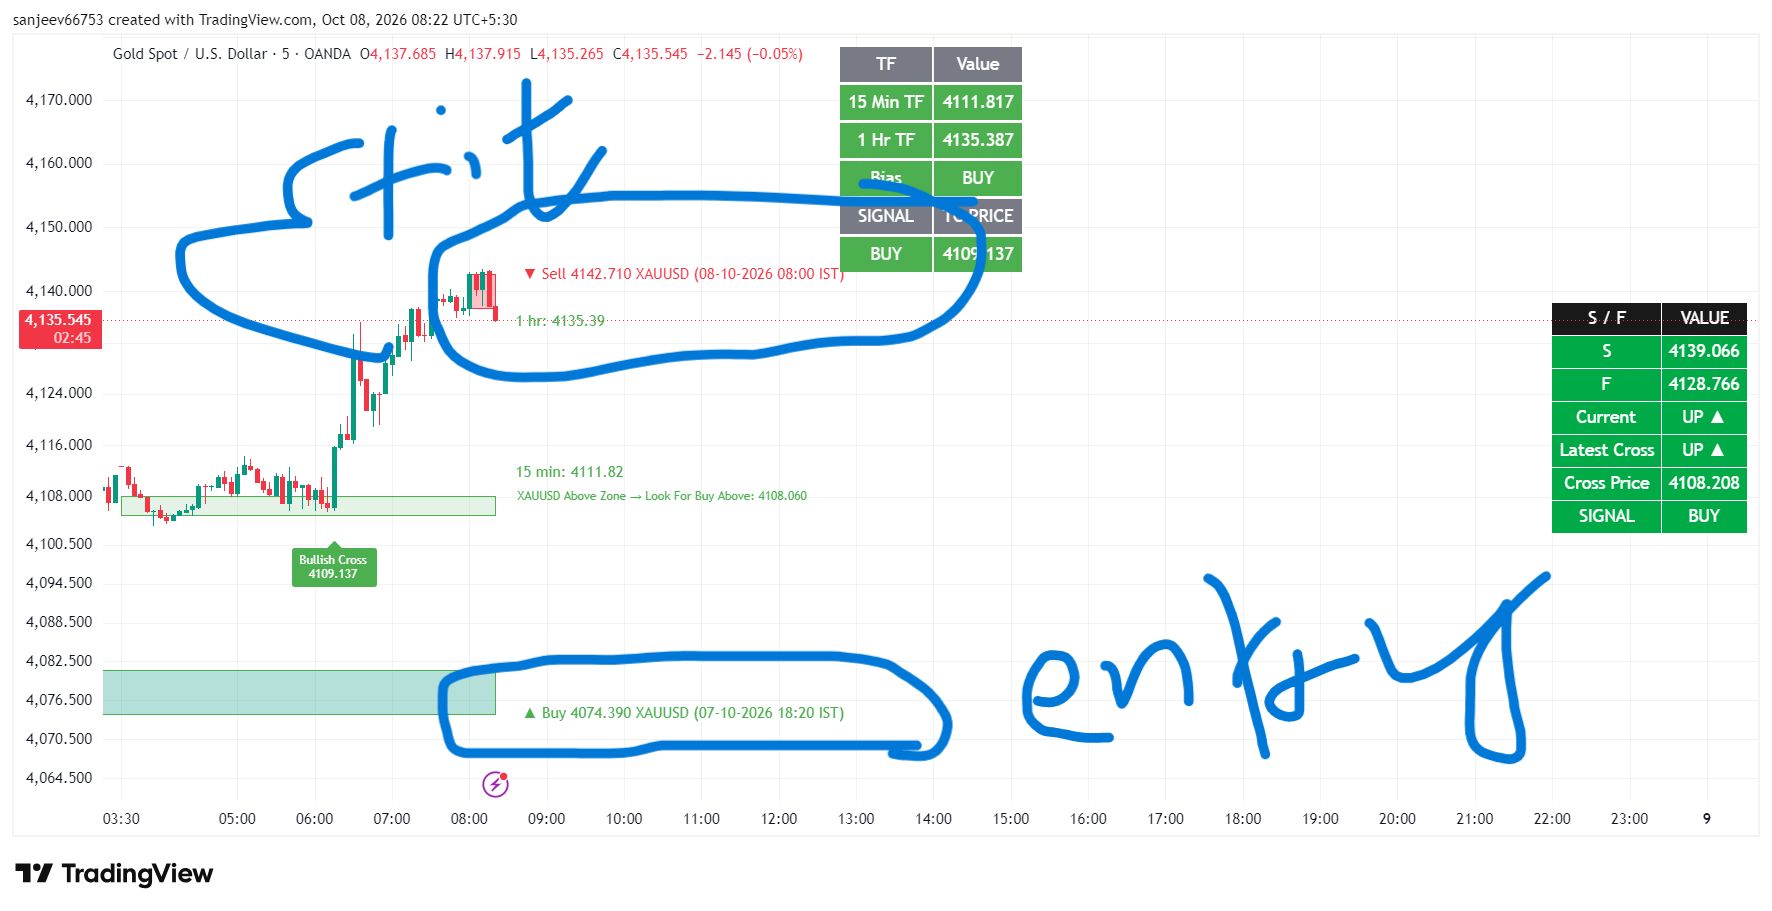
 4074 已经没有机会了 昨天到了目标没有做多了 很难再有机会了







That's certainly how the market looked at things yesterday, after an August US CPI report that was broadly inline with expectations, contrasted with a marked and surprising rise in initial jobless claims.
That's certainly how the market looked at things yesterday, after an August US CPI report that was broadly inline with expectations, contrasted with a marked and surprising rise in initial jobless claims. It's also, of course, how the FOMC are looking at things, after Chair Powell's dovish pivot at Jackson Hole.In terms of the specifics – headline CPI rose 0.4% MoM/2.9% YoY last month, while core CPI rose 0.3% MoM/3.1% YoY. Though this is, clearly, considerably north of the Fed's price target, and the headline metric continues to move in the wrong direction, Chair Powell has indicated that the FOMC will largely look-through any tariff-induced price pressures as a ‘one-time shift in the price level'. Hence, neither the above metrics, nor the 1.5% YoY rate of core goods inflation (the fastest pace since May 2023), will derail the Committee from delivering a 25bp cut next Wednesday.
As for the labour market, initial jobless claims rose to 263k in the week ending 6th September, the highest level since late-2021, though continuing claims unexpectedly fell to 1.939mln, in the seven days before that. That initial claims print, though, is clearly a concern, especially given the dismal July and August jobs reports, which also pointed to the labour market broadly losing momentum. I would flag, however, that the initial claims print did coincide with Labor Day, which could've somewhat skewed the figures higher.
That said, the jobless claims figures, coupled with underlying inflationary pressures not intensifying further last month, as well as the recent poor payrolls prints, has all further raised the risk that the FOMC now decide to make consecutive cuts through year-end, as opposed to the 2x 25bp moves (in Sep & Dec) that remains my base case. Markets are also increasingly of this view, with the USD OIS curve now fully discounting 75bp of easing by year-end.
In contrast to that more dovish path, the policy path for the ECB moving forwards is now a flat one, with yesterday's decision having all-but-confirmed that the easing cycle is done & dusted. As expected, the Governing Council maintained the deposit rate at 2.00%, while maintaining a ‘data-dependent' stance. Despite continuing to forecast an inflation undershoot next year, and now also forecasting an undershoot in 2027, President Lagarde repeated that policy is in a ‘good place', firmly supporting the idea that no further cuts are set to be delivered.
This narrowing US-E/Z rate differential, and in fact the narrowing US-RoW rate spread, adds further support to the bear case for the greenback, which remains predominantly driven by ongoing capital outflows as Fed policy independence is further eroded by the Trump Administration. The buck lost ground against most major peers yesterday, and I remain not only a longer-run dollar bear, but also a rally seller, if any rebounds were to occur.
Elsewhere, yesterday largely brought ‘more of the same' across the board. Equities ground out another day of gains, benefitting this time not from any notable macro optimism, but instead from the aforementioned dovish repricing of Fed policy expectations, in a classic ‘bad news is good news' rally. Typically, those sort of moves make me a little nervous, though for now I'll set those nerves aside as, firstly, I think the present labour market weakness is an adjustment to tariffs as opposed to anything more structural; and, secondly, as earnings growth remains solid, and underlying economic growth appears resilient too.
Finally, it would be remiss not to mention the gains seen across the Treasury curve, with benchmark 30-year yields sliding further below 4.70%, and the benchmark 10-year yield trading under 4.00% for the first time since April. Frankly, with the Fed having all-but-given up on the 2% inflation target, and with the Treasury showing no sign of reigning in runaway fiscal spending, I see little reason to like duration, and little reason not to expect a steeper curve. Mr Market, though, seems to have other ideas right now.
UK GDP figures are due this morning, though it's the very noisy monthly series for July which, while set to show the economy having stagnated last month, remains much too volatile to be of any use. In fact, the ONS would be wise to cancel its publication entirely, and focus its efforts on fixing much more important series such as the flawed inflation, and labour market, reports.
On the subject of volatility, the UMich sentiment index has been all over the place this cycle, largely due to political bias, and a very small sample size. In any case, the prelim. September reading is set to print 58.0 this afternoon, down from the 58.2 seen in August.
Besides that, all participants have to digest will be the typical deluge of ECB speakers that we tend to see the day after a policy announcement. If it being the end of a long week wasn't excuse enough to imbibe later, that lot will almost certainly drive us to a beer!

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


