


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev








Compare invoice prices, implied repo and financing costs for Treasury futures. A two bond example shows when the apparent cheapest delivery changes—and why the calculation is not a locked profit.
A Treasury priced at 96.50 can be more expensive to deliver than one priced at 101.60. The futures seller does not merely buy a cheap bond and hand it over for a fixed 100. The payment received depends on that bond’s conversion factor, the applicable futures settlement price and accrued interest. Funding the purchase adds another bill.
The useful comparison is therefore between the money spent acquiring and carrying each eligible security and the money received through delivery. Start with one contract and one proposed delivery date. Only then compare the candidates. A different contract month, financing rate or coupon date can change the answer.
The short futures position has choices within the contract’s delivery rules; the long cannot demand whichever Treasury looks most attractive. Verify eligibility from the current contract specifications and use the conversion factor for that security and delivery month. The factor is based on a standardized 6% yield convention. It is neither the bond’s current yield nor a promise of a 6% return.
For a contract with $100,000 face value, one full price point represents $1,000. If prices and accrued interest are both stated per $100 face value, the invoice amount in dollars is 1,000 × (futures settlement price × conversion factor + delivery-date accrued interest). Other Treasury futures can have different contract sizes. Never use a familiar multiplier without checking it.
Purchase-date accrued interest and delivery-date accrued interest are not interchangeable. The first is part of the cash needed to acquire the bond; the second enters the delivery payment. Mixing a clean cash price with an interest-inclusive invoice makes the apparent profit too large.
Consider hypothetical eligible bonds A and B, with cash settlement 45 days before a common delivery date and no coupon paid between those dates. The futures price is 118. All table entries are per $100 face value. These are constructed inputs, not quotes for an actual security. Financing uses simple interest on an actual/360 basis.
| Per $100 face value | Bond A | Bond B |
|---|---|---|
| Clean price | 96.50 | 101.60 |
| Initial accrued interest | 0.70 | 0.40 |
| Initial dirty price | 97.20 | 102.00 |
| Conversion factor | 0.8200 | 0.8700 |
| Delivery accrued interest | 1.20 | 0.90 |
| Invoice price | 97.96 | 103.56 |
| Implied repo, annualized | 6.2551% | 12.2353% |
| Financing interest at 4% | 0.486 | 0.510 |
| Surplus after 4% financing | 0.274 | 1.050 |
A costs less to buy, but its smaller conversion factor also produces a smaller delivery payment. At a common financing rate of 4%, A requires 97.20 × 4% × 45/360 = 0.486 in interest. B requires 0.510. Subtract principal and financing from the respective invoices: A leaves 0.274 and B leaves 1.050. Per $100,000 face value, that is $274 versus $1,050 before omitted costs.
The same result can be expressed as net basis. Gross basis is clean price minus futures price times conversion factor: −0.26 for A and −1.06 for B. Carry here is the 0.50 increase in accrued interest minus financing cost. Net basis, gross basis minus carry, is −0.274 for A and −1.050 for B. Under these assumptions the more negative figure corresponds to the larger delivery surplus; it is not a label saying the bond is cheap on every valuation measure.
With no intervening coupon, implied repo is (invoice price / initial dirty price − 1) × 360/45. That gives 6.2551% for A and 12.2353% for B. It is an annualized cash-and-delivery comparison, not a 45-day return, a quoted borrowing rate or a bond yield to maturity. On this common-date comparison B has the higher implied repo.
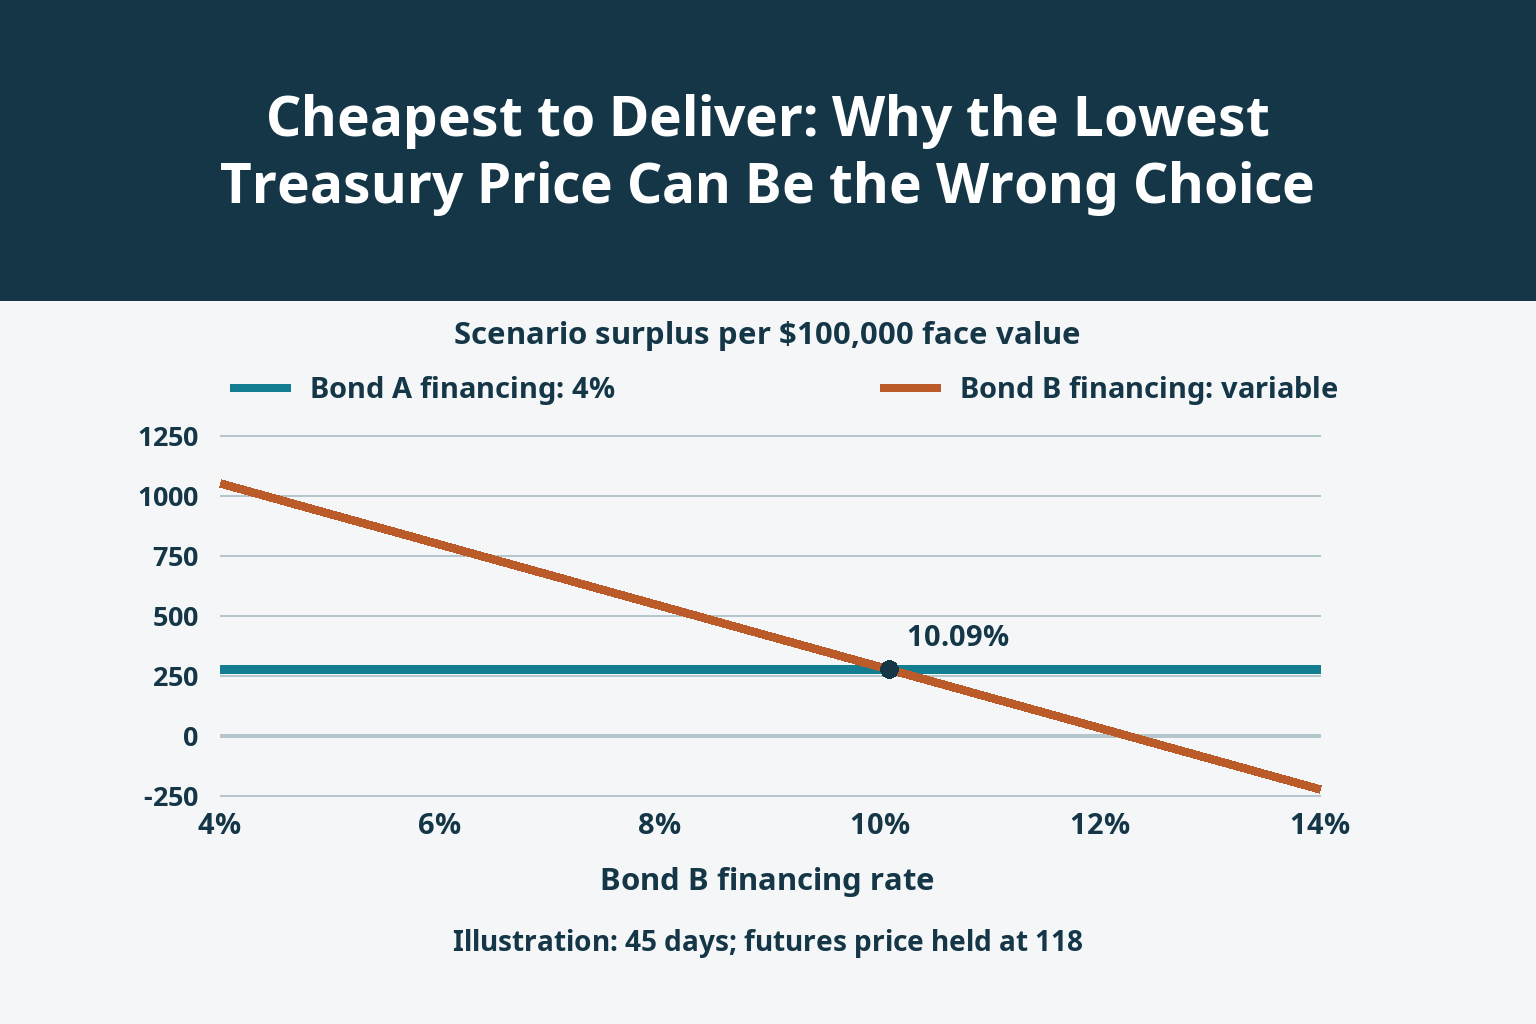
Now leave A’s funding at 4% but raise B’s to a hypothetical 12%. B’s interest becomes 1.53, leaving only 0.03, or $30 per contract-sized amount. A still leaves $274. The trader’s financing-adjusted preference has reversed even though the quoted implied repo numbers have not changed.
The dividing line can be calculated rather than guessed. Solve 103.56 − 102 × (1 + r × 45/360) = 0.274. B’s funding rate is then 10.0863%. Above it, A leaves more under the stated assumptions. The chart isolates this funding sensitivity; it is not evidence that such spreads are available in the market. Actual repo terms, collateral haircuts and the cost of the trader’s own cash must enter a real comparison.
The example holds the futures price at 118 through delivery, so it has no variation-margin cash flow. It also omits fees, taxes and margin funding. A live position cannot assume those conditions. If futures move, the delivery invoice uses the applicable settlement price while the short position generates separate daily gains or losses.
For one $100,000 contract sold at F0 and delivered using F1, cumulative futures price gains are 1,000 × (F0 − F1); the invoice is 1,000 × (F1 × CF + accrued interest). Adding them does not generally equal an invoice calculated at F0 because CF is not usually one. The timing and funding of margin payments introduce further differences.
If a coupon falls before delivery, add its amount and timing explicitly; do not keep using the no-coupon ratio. Repeat the comparison for permitted delivery dates, and use executable prices rather than a stale last trade. Funding availability, bid-ask spreads and delivery options can matter more than a small displayed basis advantage.
Suppose B remains the relevant cheapest-to-deliver bond and its cash DV01 is $80 per $100,000 face value. A local approximation gives futures DV01 of 80/0.87 = $91.95 per contract. A $1 million holding with $800 DV01 would therefore correspond to about 8.7 futures contracts, not automatically ten. Rounding creates residual exposure.
Physical delivery still matches the specified face value per contract. A conversion-factor-weighted basis hedge can therefore leave a delivery tail. Moreover, a change in the likely deliverable bond changes the futures risk profile. Aggregate DV01 does not capture every yield-curve movement; key rate duration and node-by-node hedge checks help explain the remaining mismatch.
The lowest sticker price is only one input. The meaningful result is a dated, funded cash-flow comparison whose assumptions are visible—and whose ranking is recomputed when those assumptions change.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


