


- AUDUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev












Equal total DV01 does not mean equal yield-curve risk. A reproducible 2-, 5- and 10-year example maps node exposures, prices three curve shocks and shows what a single-bond hedge leaves behind.
A hedge can cancel the portfolio’s total DV01 and still lose six figures when the yield curve changes shape. That is not necessarily a failed calculation. It may be a successful hedge of the wrong risk: a parallel shift, when the market actually delivered a twist.
Key rate duration separates interest-rate exposure by maturity. The sum answers how much risk the portfolio carries; the distribution answers where that risk sits. A usable hedge needs both, measured on the same curve and in the same currency.
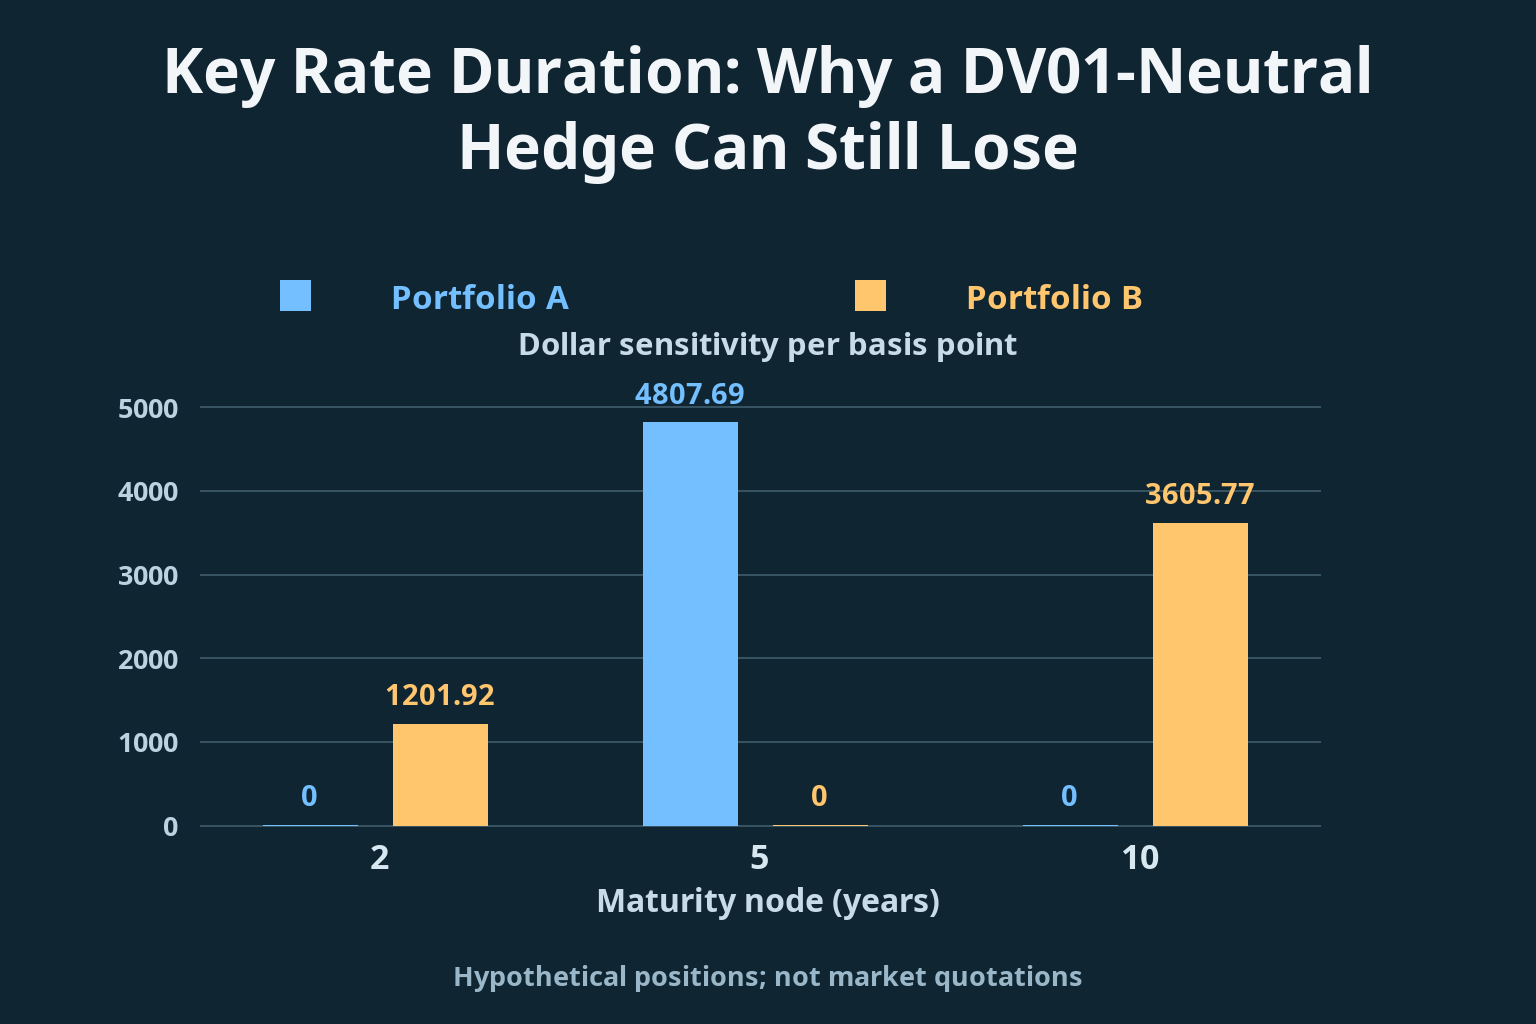
Consider two hypothetical portfolios, each worth $10 million. A holds only a five-year zero-coupon bond. B puts 62.5% of its initial market value in a two-year zero and 37.5% in a ten-year zero. All three annual-compounded spot rates start at 4%. These are market-value weights, not face-value weights. Payments are fixed, with no embedded options or credit changes.
For a zero maturing in t years, modified duration is t ÷ 1.04. A therefore has duration 4.807692. B has 0.625 × 2 ÷ 1.04 + 0.375 × 10 ÷ 1.04 = 4.807692 as well. Multiply by $10 million and 0.0001: both have total DV01 of $4,807.69 per basis point. We quote a positive DV01 as the approximate loss when the relevant rate rises one basis point.
Yet A’s entire exposure is at five years. B’s node DV01 is $1,201.92 at two years and $3,605.77 at ten years. Matching the totals has not matched the cash-flow locations. An unchanged five-year yield can leave A unmoved while B falls.
Bump one curve node up and down, keep the agreed treatment of the other nodes unchanged, and reprice. For node i, KRDᵢ ≈ [P(r − hᵢ) − P(r + hᵢ)] ÷ (2P₀h), with h = 0.0001 for one basis point. Dollar node DV01 is P₀ × KRDᵢ × 0.0001. Summing these node sensitivities approximates parallel-shift duration when the bump functions together reproduce the same parallel shift.
The curve definition is part of the number. Spot-rate bumps, par-yield bumps and swap-quote bumps are not interchangeable. Neither are two systems using different nodes or interpolation. A coupon bond can have exposure between several nodes; allocating its entire DV01 to its final maturity misses its earlier payments. Our zeros mature exactly at the three chosen nodes, so those complications are deliberately absent.
The following shocks occur instantaneously: time does not pass, and funding, dealing costs, taxes and currency changes are excluded. For each zero, new value equals its original market value multiplied by [1.04 ÷ (1.04 + Δr)]ᵗ. Add the two components of B. The table reports changes relative to each portfolio’s own $10 million starting value, not returns over a year.
| Shock at 2 / 5 / 10 years (bp) | A: price change | B: price change |
|---|---|---|
| +25 / +25 / +25 | -1.1933% | -1.1890% |
| -50 / 0 / +50 | 0.0000% | -1.1508% |
| -25 / +50 / -25 | -2.3696% | 1.2150% |
The parallel 25-basis-point rise produces nearly equal losses. The small difference is nonlinear price sensitivity, not a contradiction of equal first-order duration. With the short rate down 50 basis points and the long rate up 50, however, A is unchanged and B loses about $115,079. Its ten-year exposure dominates the benefit at two years.
The third row changes the middle of the curve relative to both ends. A loses about $236,956 while B gains about $121,504. A headline such as “yields rose” cannot describe that outcome. The relevant question is which yields moved and where the portfolio was exposed.
Now hold B and short $10 million of A, assuming the short can be arranged. Net node DV01 becomes [+$1,201.92, −$4,807.69, +$3,605.77]. The sum is zero. The steepening scenario still loses $115,079 because the five-year hedge does nothing when that rate is unchanged.
The linear estimate is −Σ(DV01ᵢ × shockᵢ in basis points). It predicts a $120,192 loss in that scenario, around $5,113 more than exact repricing. Even a correctly specified risk vector is a local approximation. FastBull’s bond convexity analysis explains the separate problem of nonlinear pricing errors.
The hedged book gains about $427 under the parallel rise and $358,460 under the third shock, before costs. Those figures are dollar profit and loss. Dividing them by zero initial net market value would create a meaningless return. Gross positions, collateral, financing, borrowing availability and liquidity still consume capital.
Choose instruments for their node exposures, not simply their labels. With several hedge instruments, arrange each instrument’s dollar sensitivities as a column and solve for positions that reduce the target vector. One five-year instrument generally cannot neutralize independent two- and ten-year exposures. If a perfect match is unavailable, state the residual vector and test the scenarios under which it hurts.
For assets backing liabilities, compare asset and liability sensitivities in money, not just their duration in years. Equal duration on unequal market values leaves dollar risk. Futures bring additional issues: delivery baskets, the cheapest-to-deliver bond, conversion factors and basis can change the effective hedge. A cash-bond example does not settle those risks.
Key rate duration does not forecast the next curve move or assign it a probability. It makes a narrower, useful claim: if a particular part of this specified curve moves a little, this is where the book should react. That is the right level of precision for deciding whether a hedge removes risk or merely renames it.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


