


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev












A reproducible 20-year bond example shows when duration errors matter, what convexity fixes, and why a more convex portfolio can still lose when the yield curve twists.
A duration estimate is useful only if its error is small enough for the decision being made. A long-dated bond can move so far from that estimate that a sensible interest-rate view produces a badly sized position. Convexity corrects the curvature; it does not make a large-shock estimate exact or remove yield-curve risk.
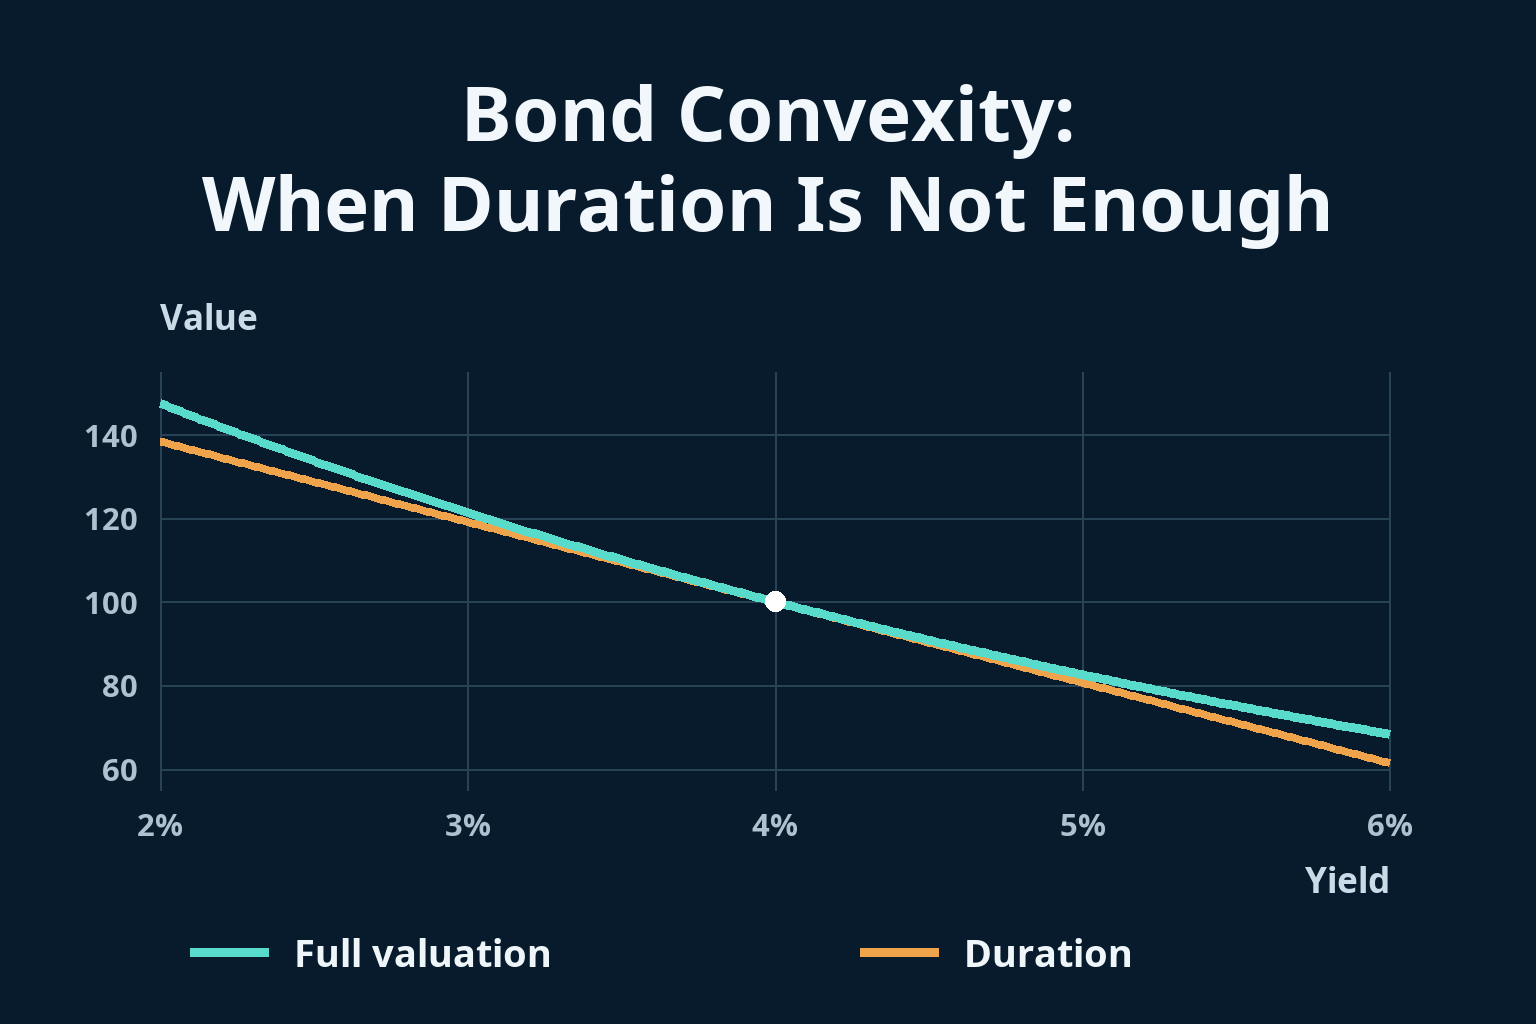
Consider a hypothetical zero-coupon bond paying 100 in exactly 20 years. Its annual-compounded yield is 4%, so its price is 100 ÷ 1.04²⁰ = 45.6387. There are no interim coupons or embedded options. Cash flows remain fixed, time does not advance, and taxes, dealing costs, financing and currency changes are excluded. This is an immediate repricing exercise, not a holding-period return forecast.
Normalize today's market value to 100. If the yield falls to 2%, exact valuation gives 147.46: a 47.46% gain. Duration alone gives 138.46. If yield rises to 6%, exact value is 68.32, against duration's 61.54. The linear approximation understates the gain and overstates the loss because the fixed-cash-flow price curve bends above its tangent.
For this annual-compounded zero-coupon bond, modified duration D = 20 ÷ 1.04 = 19.2308. Yield convexity C = 20 × 21 ÷ 1.04² = 388.3136. The second-order estimate is ΔP/P ≈ −D × Δy + ½ × C × (Δy)². Enter a 100-basis-point change as 0.01, not 1 or 100. Macaulay duration, modified duration and a fund's effective duration are not interchangeable inputs.
The exact normalized price is 100 × [1.04 ÷ (1.04 + Δy)]²⁰. The table keeps all inputs unchanged except yield. Its entries are values, not percentage returns; subtract 100 to obtain the percentage return.
| Shock (bp) | Exact | Duration | With convexity |
|---|---|---|---|
| -200 | 147.46 | 138.46 | 146.23 |
| -100 | 121.32 | 119.23 | 121.17 |
| -25 | 104.93 | 104.81 | 104.93 |
| +25 | 95.31 | 95.19 | 95.31 |
| +100 | 82.58 | 80.77 | 82.71 |
| +200 | 68.32 | 61.54 | 69.30 |
At −200 basis points, convexity lifts the estimate to 146.23, still 1.23 value points below the exact answer. At +200 basis points it gives 69.30, about 0.98 points too high. A second-order correction is much better here, but higher-order terms remain. The discrepancy also differs between equal upward and downward shocks.
Suppose the maximum acceptable valuation error is 0.10% of current market value. Use the curvature term as a screening test: ½C(Δy)² = 0.001 implies |Δy| ≈ 22.69 basis points. This is not a guaranteed error bound. It signals that this particular bond needs full repricing around that shock size, rather than waiting for an arbitrary 100-basis-point rule.
The ±25-basis-point rows confirm why: duration already misses by roughly 0.12 value points. On a current position worth 1 million in its pricing currency, that is about 1,200. Use actual unrounded inputs when testing a limit. For a short-duration bond, a different convexity produces a different threshold. Translating first-order sensitivity into cash is covered in FastBull's DV01 calculation guide; an error budget should be expressed in the same currency as that risk limit.
Compare the 20-year zero with a portfolio split equally by initial market value between 10-year and 30-year zeros, all initially yielding 4%. This barbell has the same modified duration, 19.2308, but convexity of 480.7692. Under an instantaneous parallel shift of 100 basis points, its extra second-order contribution is about 0.46% of initial value: ½ × (480.7692 − 388.3136) × 0.01².
That is a controlled comparison, not free excess return. Now let the 10-year yield fall to 3%, the 30-year yield rise to 5%, and the 20-year yield remain at 4%. The barbell becomes 50 × (1.04/1.03)¹⁰ + 50 × (1.04/1.05)³⁰ = 92.59, while the 20-year bond stays at 100. More convexity has not protected the portfolio from an adverse curve twist. Real comparisons also need credit quality, liquidity, funding and the price paid for the cash flows.
Start with settlement, payment dates, coupon frequency and the full price including accrued interest. Match the yield convention to those cash flows; do not insert semiannual bond statistics into this annual example unchanged. Recompute prices for both directions of the proposed shock and measure the difference from the approximation in currency and as a fraction of the starting value.
For a portfolio, shock maturity nodes separately as well as together. For callable bonds or mortgage-backed securities, cash flows may change when rates fall: redemption or refinancing can cap appreciation and create negative convexity over some ranges. Use a consistent option-sensitive valuation model rather than this fixed-cash-flow formula. Finally separate instantaneous price risk from later coupon income, reinvestment, financing and passage of time. The useful question is not whether a bond has convexity, but whether the chosen pricing method stays within your error budget under the scenarios that matter.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


