


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev











A start-settled FRA discounts an interest difference, not the loan principal. Reconcile a €10 million example across payment dates, then measure the gaps left by reinvestment rates, financing costs and the loan's credit spread.
A company fixes a 4% rate through a forward rate agreement, or FRA. The reference rate subsequently fixes at 6%, so the hedge produces a cash receipt. Has the company's interest bill therefore been reduced to exactly 4%? Not until the cash dates and the treatment of that receipt have been reconciled.
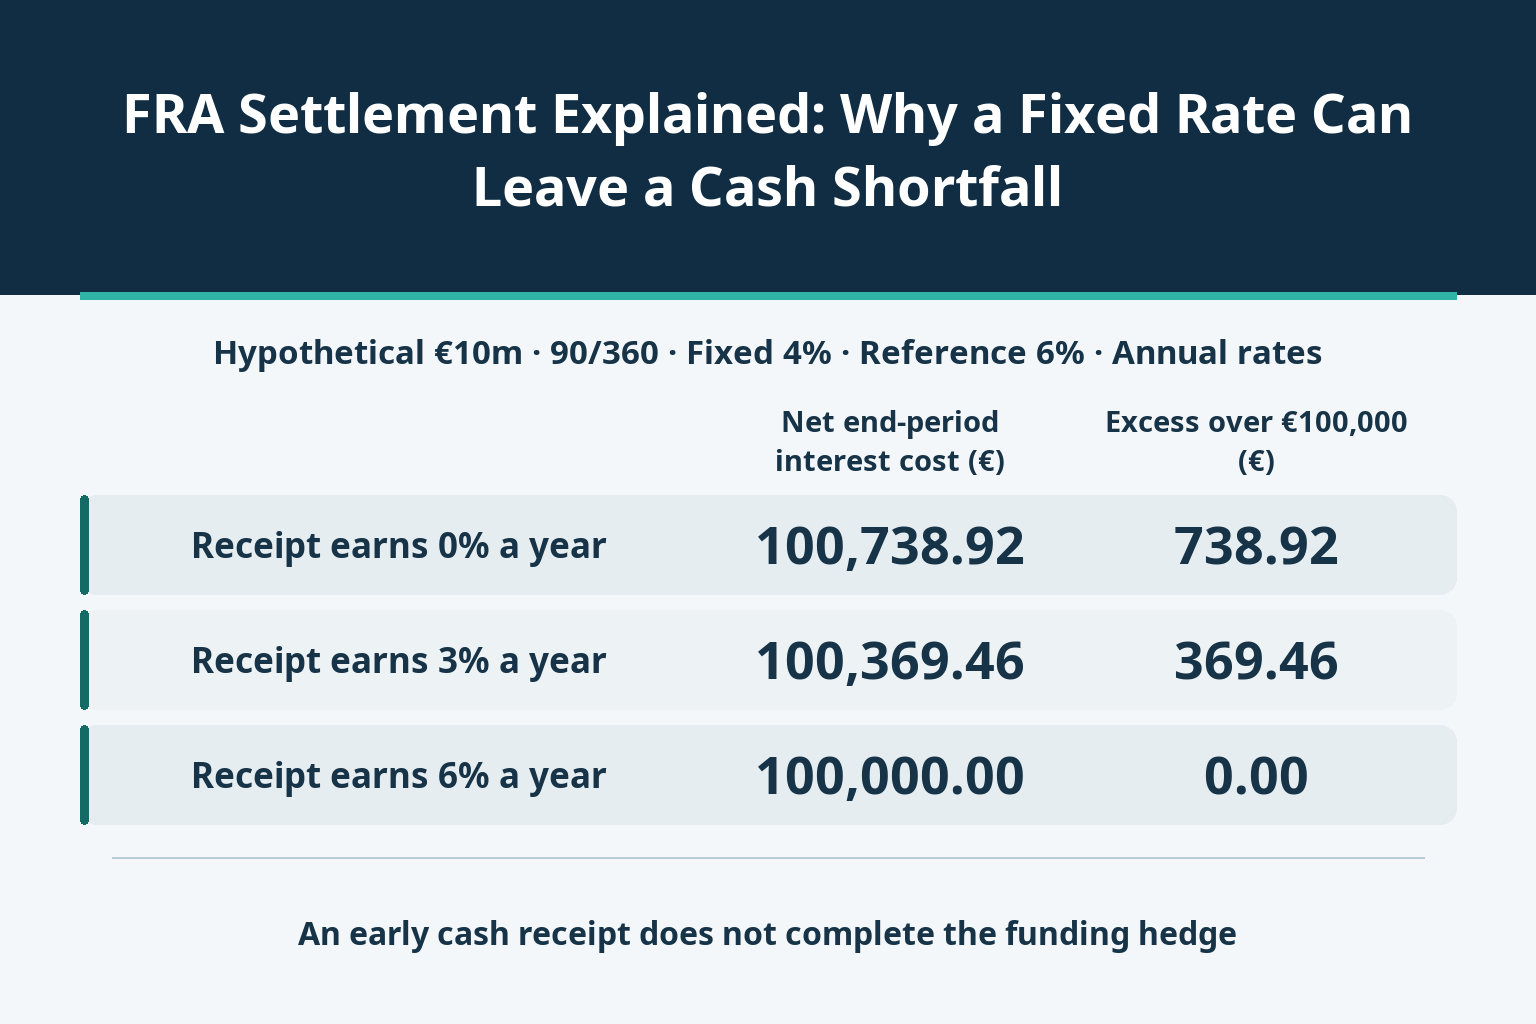
For the explicitly defined start-settled FRA below, the company receives €49,261.08 at the beginning of a 90-day loan period, not €50,000 at its end. If the receipt remains idle, the combined end-period interest cost is €100,738.92 rather than the €100,000 implied by 4% on the original €10 million borrowing. The difference is not a failed subtraction. It is the missing return on money received early.
An FRA specifies an interest-rate exposure for a future interval; it does not itself advance the notional loan principal. The trade date fixes the agreed rate K. The contract's fixing provisions determine when its reference rate L becomes known. The underlying interest period then begins and ends on its specified dates. Fixing and payment need not occur on the trade date, and no universal fixing lag should be inferred from the abbreviation FRA.
Payment conventions also matter. The Basel Committee's current counterparty-credit-risk guidance explicitly distinguishes an example paid at period end from a convention paid at the beginning. A generic instrument name is therefore not enough to select a cash formula. This article assumes a fixed-rate payer receiving the floating rate, with a contractually agreed discounted net payment at the period's start. It is not a statement that every FRA uses that convention.
Assume a €10,000,000 notional, K = 4% a year, exactly 90 accrual days and an ACT/360 year fraction τ = 90/360 = 0.25. All rates are annual simple rates and all amounts are hypothetical. A separate €10 million loan has the same period and initially pays L with no credit spread. Its principal remains separately repayable; only its interest enters the comparison below. Fees, taxes, collateral funding and default are excluded.
The interest difference measured at period end is D = N(L − K)τ. For this contract, the start-date cash is C = N(L − K)τ ÷ (1 + Lτ). Positive C is received by the fixed payer; negative C must be paid. The check is immediate: C(1 + Lτ) = D. The discount factor moves the same modeled difference between dates.
| Annual reference rate L | Interest difference at period end (€) | Net FRA payment at start (€) | Separate loan interest at L (€) |
|---|---|---|---|
| 2% | -50,000.00 | -49,751.24 | 50,000.00 |
| 4% | 0.00 | 0.00 | 100,000.00 |
| 6% | 50,000.00 | 49,261.08 | 150,000.00 |
At L = 6%, the separate loan's interest is €150,000 and D is €50,000. The agreed FRA receipt is €50,000 ÷ 1.015 = €49,261.083743… at the start. At L = 2%, the direction reverses: D is −€50,000 and C is −€49,751.243781…. Equal two-percentage-point moves on opposite sides of 4% do not produce equal absolute start payments because their denominators differ.
The €50,000 end difference and the €49,261.08 start receipt are not two payments owed under the same FRA. Nor is the smaller receipt a fee deducted by the counterparty. An alternative contract paying the difference at the end would have a different cash schedule. Compare those schedules at a common date before describing one as more generous. Calculations here retain full precision; displayed cents are rounded independently.
A frequent mistake is to discount at the fixed FRA rate because that is the rate being hedged. At L = 6%, using 1 + 4% × 0.25 in the denominator gives €49,504.95, overstating the stipulated receipt by €243.87. The numerator asks how far L differs from K; the denominator specifies how this contract converts the end-period difference into an early payment. Those are different jobs.
This is an error under the payment convention we have stated, not a general instruction to use L as the discount rate for every derivative valuation. A pre-fixing mark-to-market calculation, a collateral discount curve and a negotiated settlement formula are not interchangeable objects. Confirm the contractual definitions before changing any input.
Likewise, K is an agreed rate, not evidence that the eventual fixing will be 4%. The distinction between a price-implied forward rate and a forecast is explained in reading the yield curve's reinvestment hurdle. Here, the decision is narrower: once L has fixed, what cash is owed, when is it paid, and how does that cash meet the separate loan bill?
Keep L at 6% and the main loan at €10 million. Hold its €150,000 interest bill unchanged. Let R be the annual simple rate actually available on the FRA receipt over the same 90 days. At period end the receipt and its return are C(1 + Rτ), so the net interest cost is €150,000 − C(1 + Rτ).
| Annual reinvestment rate R | FRA receipt grown to period end (€) | Net end-period interest cost (€) | Excess over €100,000 (€) |
|---|---|---|---|
| 0% | 49,261.08 | 100,738.92 | 738.92 |
| 3% | 49,630.54 | 100,369.46 | 369.46 |
| 6% | 50,000.00 | 100,000.00 | 0.00 |
The rows are separate alternatives, not three successive investments. At R = 6%, the receipt grows to exactly €50,000 and the remaining cost is €100,000. At R = 3%, it grows only to €49,630.54; the remaining €100,369.46 exceeds the target by €369.46. Leaving the receipt idle creates a €738.92 gap. These are annual investment-rate assumptions, not returns earned over just 90 days.
Subtracting the early receipt directly from the later bill is therefore an idle-cash case, not a universal hedge result. A company might instead use the receipt to reduce another borrowing, but then the relevant benefit is the borrowing cost actually avoided, with its own dates and restrictions. It cannot assume the reference rate is an executable deposit return merely because the same number appears in the FRA formula.
At L = 2%, the main loan interest falls to €50,000, but the FRA requires a €49,751.24 payment at the start. Assume the company keeps the main loan principal at €10 million and borrows the FRA debit separately. If that extra cash can be funded at 2% for the same 90 days, its repayment is exactly €50,000. The main loan's interest plus the repayment financing the FRA debit is €100,000.
If the actual annual funding rate is 3%, the extra repayment becomes €50,124.38 and the combined cost becomes €100,124.38. The €124.38 residual is a funding-rate mismatch. The financing repayment includes return of the cash advanced to pay the FRA; it is not a second repayment of the main loan's €10 million principal.
Existing cash is not automatically free either: deploying it may sacrifice a return elsewhere. The comparison must specify that alternative before attaching a cost. More fundamentally, an expected reduction in later loan interest does not supply cash for a debit due now. The facility's availability and payment cut-off are part of the hedge's execution, not just an operational afterthought.
Restore L = 6%, but let the actual loan cost L plus one percentage point. Its interest is now €175,000. Reinvest the unchanged FRA receipt at 6% to obtain €50,000 at period end: the net cost is €125,000, not €100,000. The remaining €25,000 is the loan spread on €10 million for a quarter-year. A hedge on L has not promised to fix the borrower's credit pricing.
Write the loan spread as s and the relevant cash rate as r: use the available reinvestment rate when C is positive and the funding rate when C is negative. Under the matched-date model, net cost − NKτ = Nsτ + C(L − r)τ. This separates the loan-spread contribution from the treatment of the FRA cash. It is a signed cash-flow identity, not a market valuation model.
Other mismatches require their own reconciliation. A loan floor absent from the FRA, a different reference index, unequal notionals or adjusted dates can prevent the floating amounts from cancelling. The formula also requires 1 + Lτ to be positive; no zero floor is silently imposed. Counterparty nonpayment, delayed cash and collateral costs are outside the clean ledger and can matter independently of the borrower's credit spread.
The useful result is conditional but precise: the agreed FRA fixes a reference-rate difference. Turning that into a matched end-period borrowing cost requires a second ledger for the cash it settles early.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


