


- EURUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev










A call can cost more than its matching put without signalling an expected rally. Rebuild the cash flows, account for dividends and funding, then test the apparent gap at executable bid and ask prices.
A call priced at 7 and a put priced at 5 do not, by themselves, show that investors expect the stock to rise. If both options are European, cover the same underlying and have the same strike, expiry and settlement terms, their price difference is constrained by the stock price, the present value of the strike and any distributions. The first question is whether the contracts really match. The second is whether the comparison uses prices you could actually trade. A small discrepancy between screen midpoints can disappear before commissions even enter the calculation.
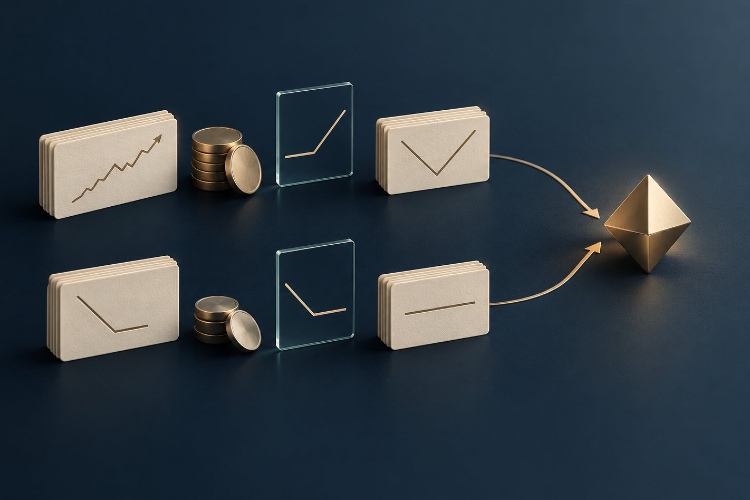
Buy a call and sell a put with a strike of 100. At expiry, the combined payoff is the final stock price minus 100. Below the strike, the short put supplies the loss; above it, the call supplies the gain. At the strike, both pay zero. The following figures are per share and exclude the initial premiums.
| Stock at expiry | Long call | Short put | Combined payoff |
|---|---|---|---|
| 80 | 0 | −20 | −20 |
| 100 | 0 | 0 | 0 |
| 120 | 20 | 0 | 20 |
Add an investment that pays exactly 100 at expiry and the package has the same terminal value as one share, provided there are no intervening distributions. That is the replication behind parity. Long call plus short put is not a free share: it creates a forward-like exposure, requires the initial net premium and leaves the strike-related obligation. Margin and cash-flow timing can differ markedly from owning stock outright.
Write C for the call price, P for the put, S for the stock, K for the strike, r for a continuously compounded annual rate and T for time remaining in years. In the no-dividend, frictionless European model:
C − P = S − K × exp(−rT)
Suppose S=100, K=100, T=0.5 and r=0.04. The present value of the strike is 98.019867, so C−P is 1.980133. If the put costs 5, the matching call implied by this relationship is about 6.980133. Equal spot and strike prices therefore do not imply equal premiums. The difference can arise from carrying costs rather than a directional forecast.
The identity needs no particular volatility model: it compares matching cash flows. But it does not calculate both option prices from nothing. Knowing only that C−P=1.980133 still leaves many possible pairs. Nor should this same-strike relationship be confused with volatility skew across different strikes.
For known cash dividends paid before expiry, subtract their present value from the stock side: C−P = S−PV(dividends)−PV(K). If a hypothetical dividend of 1 is paid in 0.25 years, its present value at the same 4% rate is 0.990050. The required premium difference becomes about 0.990083 rather than 1.980133.
This is a change in the difference, not a claim that a real dividend announcement changes only the call and leaves the put untouched. The stock price and both premiums can adjust. Use dated cash flows consistently; do not subtract a cash dividend and also apply a yield adjustment for the same payment.
The corresponding model forward price is F = [S−PV(dividends)] × exp(rT). It is a carrying-cost relationship, not an estimate of where the stock will finish. A residual may reflect financing, distributions, stock-borrow constraints or bad inputs. One residual cannot identify all those components separately.
Return to the no-dividend example. Suppose synchronized bid/ask quotes are 99.95/100.05 for the stock, 6.80/7.20 for the call and 4.80/5.20 for the put. Midpoints produce C−P+PV(K)−S=0.019867. That small positive number is not available cash.
To test a conversion, buy the stock at 100.05 and the put at 5.20, and sell the call at 6.80. The package costs 98.45 and pays 100 at expiry under the matching European assumptions. Buying the same terminal 100 at the model funding rate costs 98.019867. The option package is therefore 0.430133 more expensive before fees, not an arbitrage gain. With a hypothetical multiplier of 100, the difference is 43.01 currency units; actual contract multipliers must be checked.
Test the opposite direction separately. Short the stock at 99.95, sell the put at 4.80, buy the call at 7.20 and invest 98.019867 to meet the strike-related cash flow. The initial balance is −0.469867 per share. Both directions fail even before commissions. Short-sale proceeds may not be freely available, borrowing and lending rates may differ, and stock-loan fees or collateral requirements can widen the gap further.
American options permit early exercise, so a terminal-payoff comparison alone does not capture all rights and obligations. Assignment can change stock ownership, dividend entitlement and funding before expiry. Do not label an American-option difference a pricing error merely because it fails the European equation.
Also check adjusted deliverables after corporate actions, contract size, settlement currency, cash versus physical delivery and the exact settlement observation. Two options expiring on the same calendar date can still settle against different observations. Options on futures require their own contract and financing conventions. Last-traded prices recorded at different times are another common source of artificial discrepancies.
The same discipline clarifies covered-call premiums and capped upside: collecting an option premium does not remove the other leg’s economic exposure. Equivalent terminal payoffs do not guarantee identical margin, tax treatment or operational risk.
First match underlying, strike, expiry, exercise style, multiplier and settlement. Then timestamp the stock, call and put quotes and confirm that the displayed size covers the intended comparison. Put dividends and funding on dated cash-flow schedules. Calculate both executable directions, buying at offers and selling at bids. Finally include commissions, stock borrow, collateral, assignment and the possibility that one leg fills without the others.
If the contracts or inputs do not match, stop treating the residual as evidence. If a gap survives, it is a question to investigate under actual execution constraints—not proof of bullish sentiment or a guaranteed profit. Parity is most useful as a consistency check: it tells you which cash flow or assumption must be examined next.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


