


- WTI
- XAUUSD
- XAGUSD
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev









A risk reversal compares implied volatility at two Delta points. It does not price a fixed insurance contract. Three hypothetical volatility snapshots and a fixed-strike experiment show how unchanged at-the-money volatility can conceal a different downside wing—and why the strike matters.
At-the-money implied volatility can stay at 20% while the downside wing becomes more expensive in volatility terms. A 25 Delta risk reversal helps identify that relative repricing. It does not, by itself, tell you the cash cost of protecting the same portfolio at the same strike. The distinction matters because a constant-Delta quote can move to a different strike as volatility changes.
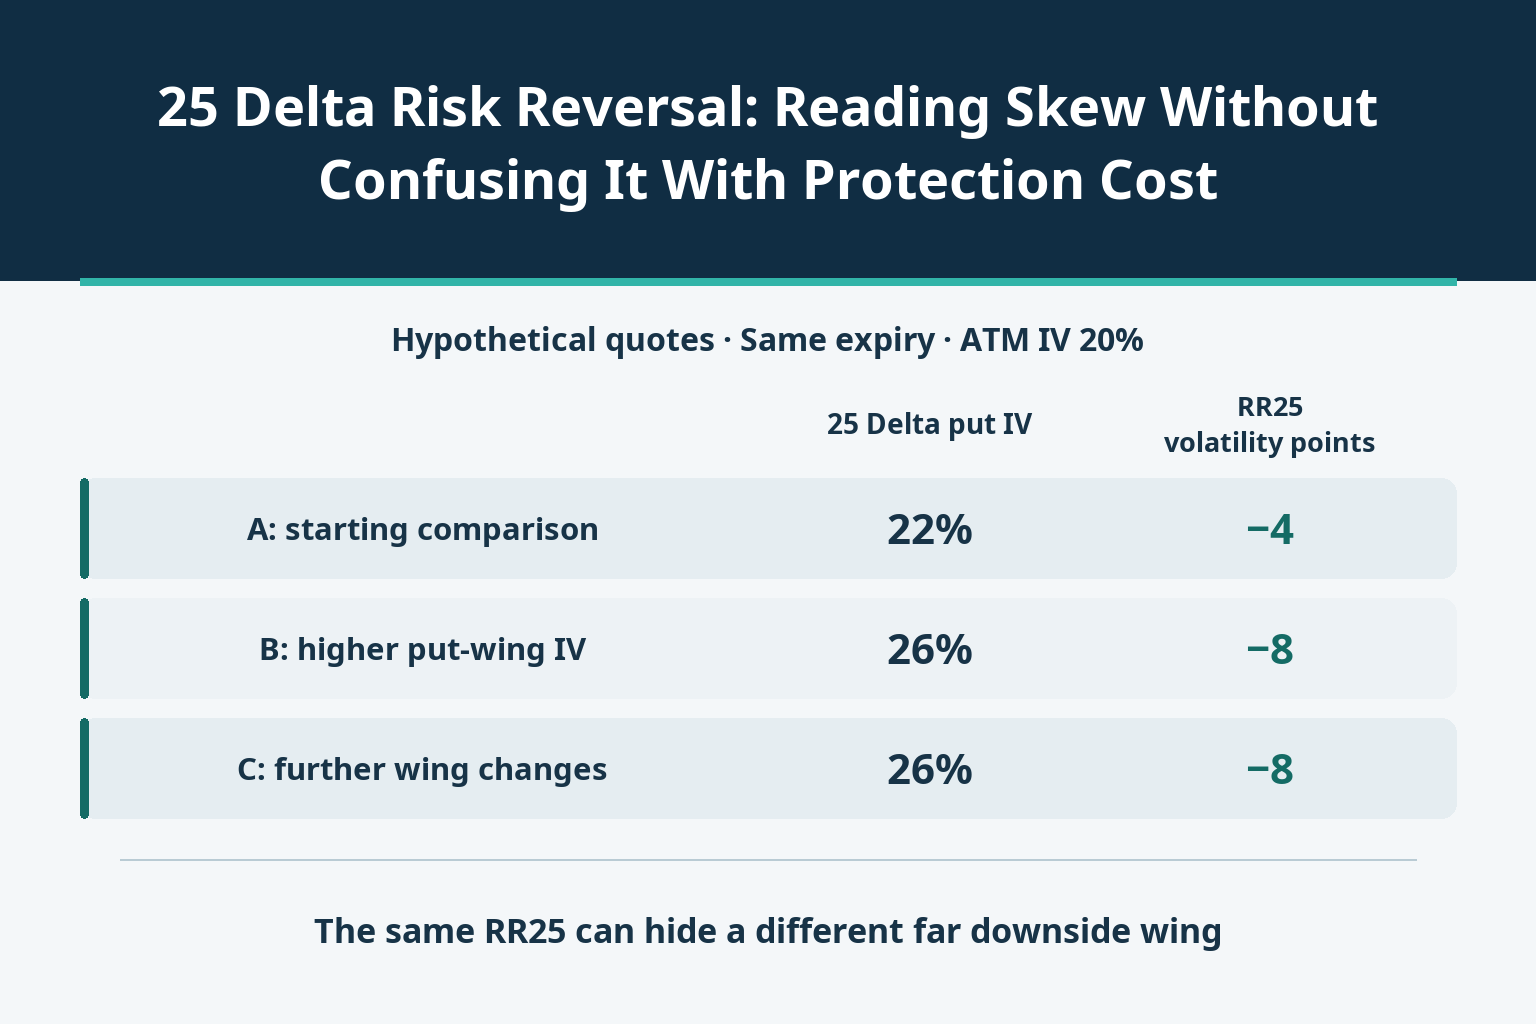
Here, RR25 means the implied volatility of the 25 Delta call minus that of the 25 Delta put, for the same expiry. A call IV of 18% and put IV of 22% produce RR25=−4 volatility percentage points. That is neither a forecast of a 4% fall nor a premium difference of four dollars.
Some displays reverse the subtraction or show an absolute spread. Establish the convention before comparing signs. Also inspect both legs: a more negative RR can result from higher put IV, lower call IV, or both. Without additional evidence, it cannot establish that protection buying has surged, identify a particular investor flow, or give a unique explanation for the move.
Consider three hypothetical cross-sections, not a sequence of market observations. Each uses European options with 0.25 years to expiry, spot and forward both at USD 100, and zero interest and dividend rates. Each option covers one underlying unit. ATM means strike 100; it does not mean 50 Delta.
| Case | ATM IV | 25 Delta put IV | 25 Delta call IV | RR25: vol points | 10 Delta put IV |
|---|---|---|---|---|---|
| A | 20% | 22% | 18% | −4 | 26% |
| B | 20% | 26% | 18% | −8 | 32% |
| C | 20% | 26% | 18% | −8 | 36% |
From A to B, call IV stays at 18% while 25 Delta put IV rises from 22% to 26%. RR25 therefore moves from −4 to −8 points. The put leg explains the change in this constructed comparison because the call leg is held fixed.
B and C have identical ATM IV and RR25, yet their 10 Delta puts have different IVs. The 10 Delta call is 19% in all three cases, giving RR10 values of −7, −13 and −17 points. Two points cannot describe the entire smile. The quoted nodes pass finite-point price-bound and convexity checks; that is not a claim to have built a complete smooth surface across all strikes and expiries.
Delta is the option price sensitivity to a small underlying-price change. We use the standard model Delta, without premium adjustment, holding the node's volatility fixed when calculating that sensitivity. The call's 25 Delta is +0.25; the put's is −0.25.
In this zero-rate model, Delta fixes d1, while the strike follows K=100×exp(0.5×σ²×T−d1×σ×√T). Changing σ while retaining the same Delta generally changes K. The table's first two rows are the floating 25 Delta put points from A and B. Its last two rows are a separate fixed-strike experiment, not interpolated prices from those snapshots.
| Put comparison | IV | Strike: USD | Premium: USD per unit | Model Delta |
|---|---|---|---|---|
| A: floating 25 Delta point | 22% | 93.412607 | 1.735663 | −0.250000 |
| B: floating 25 Delta point | 26% | 92.382403 | 2.072871 | −0.250000 |
| Separate control: fixed strike 95 | 22% | 95.000000 | 2.232607 | −0.301078 |
| Separate control: fixed strike 95 | 26% | 95.000000 | 2.940688 | −0.322915 |
The 25 Delta put strike falls from 93.412607 to 92.382403 as its IV rises. Its premium rises from 1.735663 to 2.072871 dollars per unit, but the threshold for intrinsic value at expiry has moved too. These are not two quotes for identical insurance. An out-of-the-money put can still have time value and price sensitivity before expiry. The unchanged 25 Delta call sits at strike 106.689662, further illustrating that equal absolute Delta does not put the call and put at the same strike.
Now hold the put strike at 95, with all other model inputs unchanged, and independently change its IV from 22% to 26%. The premium rises from USD 2.232607 to USD 2.940688 per underlying unit: an increase of USD 0.708081. This comparison isolates the volatility input for the same payoff. Neither put is a 25 Delta option; their Deltas are about −0.301078 and −0.322915.
The fixed-strike IVs are explicit assumptions. RR25 and the ATM quote alone do not determine what IV should apply at strike 95. Inferring it would require more quotes and a specified interpolation method.
An actual protection budget uses the offer required to buy the option, the contract multiplier, fees, currency and exercise terms. A model price or mid quote is not automatically executable. Comparing two moving Delta points cannot replace that contract-level calculation.
A 25 Delta put does not establish a 25% real-world probability that the underlying finishes below its strike. At each node, using that node's volatility in the Black–Scholes model, call Delta is N(d1) and put Delta is N(d1)−1; N is the standard normal cumulative distribution function. That node's model probabilities of expiring in the money are N(d2) and N(−d2), respectively, with d2=d1−σ√T. These node-by-node calculations are not a probability distribution recovered from the whole skewed surface, nor are they real-world forecasts.
At strike 100 and IV 20%, this example's call Delta is approximately 0.519939 and its put Delta −0.480061. Even ATM is not exactly 50 Delta here. Across dates, spot, remaining time and rates can change as well as volatility, so a Delta label is not a permanent identifier for a contract.
For FX options, specify which currency the call gives exposure to. Reversing a currency pair changes direction, units and quoting conventions; merely flipping the sign of a fixed 25 Delta number is not a complete conversion. Spot versus forward Delta, premium adjustment and ATM definitions must also agree before comparing sources.
“Risk reversal” can also name a trading position: buying a call and selling a put. One unit of a +0.25 Delta call plus a short position in a −0.25 Delta put starts with total Delta +0.50, not zero. A package arranged to have no initial net premium still has risk.
There is no contradiction with put–call parity for options at the same strike. RR compares implied volatilities at different strikes; parity relates call and put cash prices at one common strike under matching contract conditions.
The useful question is what changed in the relative option quotes. Once the question becomes what a specific hedge costs, switch from the Delta grid to the contract that actually provides that hedge.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


