


- USDCAD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev






Learn what a wash sale is, how the 61-day rule works, when stock losses are disallowed, and how to avoid wash sales with practical examples.
A wash sale occurs when you sell a stock or security at a loss and buy the same or a substantially identical investment within 30 days before or after the sale. Under IRS rules, the loss generally cannot be deducted immediately. Understanding the 61-day window can help investors avoid unexpected tax consequences when selling investments at a loss.
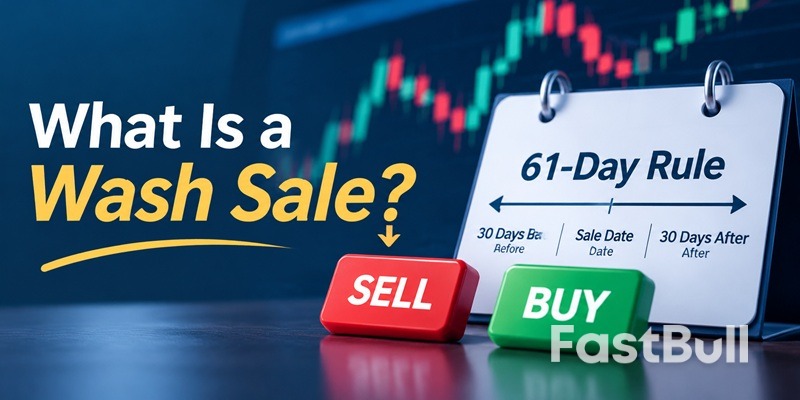
A wash sale occurs when an investor sells stock or securities at a loss and acquires substantially identical investments within a restricted period. The IRS disallows the immediate deduction of the loss because the investor has effectively maintained a similar investment position.
For example, suppose you buy 100 shares of a company for $5,000 and later sell them for $4,000, realizing a $1,000 loss. If you buy substantially identical shares within the wash sale window, you generally cannot deduct that $1,000 loss immediately.
The wash sale rule prevents investors from claiming capital losses for tax purposes while quickly maintaining essentially the same investment exposure. Without this restriction, an investor could sell a declining stock to realize a tax loss and immediately buy it back while continuing to hold the investment.
The rule does not prohibit selling and repurchasing securities. Instead, it changes when the realized loss can be deducted. In most taxable-account transactions, the disallowed loss is added to the cost basis of the replacement shares, postponing the tax benefit until those shares are sold.
A wash sale can occur through more than a straightforward stock purchase. The IRS rules may apply when you:
The rule can also apply when your spouse or a corporation you control purchases substantially identical securities within the restricted period. Therefore, selling shares in one account does not automatically prevent a wash sale if a qualifying purchase occurs through another account or by a related person.
The wash sale rule uses a 61-calendar-day window consisting of the 30 days before the sale, the sale date itself, and the 30 days after the sale. Investors must review transactions on both sides of the sale date.
Suppose you sell shares at a loss on May 15. Your wash sale window runs from April 15 through June 14, covering 61 calendar days.
If you buy substantially identical securities within this window, the corresponding loss may be disallowed. To avoid triggering the rule through a replacement purchase, you generally need to wait until June 15, the 31st day after the sale, before buying the same or substantially identical securities again.
The IRS does not provide a universal list of investments that qualify as substantially identical. Instead, it evaluates the facts and circumstances of each transaction.
Buying the same company's stock after selling it at a loss is a straightforward example. However, the analysis can become more complicated with different share classes, convertible securities, options, and investment funds.
Generally, stocks issued by two different corporations are not substantially identical. However, exceptions may apply, including certain securities involved in corporate reorganizations.
ETFs and mutual funds require particular attention. Two funds with similar holdings or investment objectives are not automatically substantially identical, but investors should not assume that switching between funds always avoids the rule.
Yes. Investors should not assume that using different brokerage accounts automatically avoids a wash sale. The rules can apply to qualifying purchases made outside the account where the original loss occurred.
For example, if you sell shares at a loss and your spouse buys substantially identical shares within the restricted period, the transaction may still trigger a wash sale.
IRA transactions are especially important. If you sell shares at a loss in a taxable brokerage account and acquire substantially identical shares in your traditional IRA or Roth IRA within the 61-day window, the loss is disallowed. Unlike a typical taxable-account wash sale, the loss is not added to the IRA's cost basis.
Broker reporting also has limitations. Form 1099-B generally identifies wash sale losses when replacement securities have the same CUSIP and are purchased in the same account. Transactions across different accounts may not be reported automatically, so investors should review their own records.
The main consequence of a wash sale is that the investor cannot deduct the affected capital loss on the original sale. However, the loss is not necessarily gone forever. Its treatment depends on how and where the replacement investment was acquired.
In most cases involving a replacement purchase in a taxable brokerage account, the disallowed loss is added to the cost basis of the replacement shares. This is known as a basis adjustment.
For example, suppose you have a $500 disallowed loss and purchase replacement shares for $2,000. Your adjusted cost basis becomes $2,500 ($2,000 + $500). When you eventually sell those shares, the higher basis generally reduces your taxable gain or increases your deductible loss.
However, an important exception applies to purchases made through an IRA or Roth IRA. In this situation, the disallowed loss is not added to the IRA's basis. As a result, the tax benefit may be permanently lost rather than deferred to a future sale.
A wash sale does not carry a separate fixed-dollar penalty simply because the transaction occurs. The direct tax consequence is that the affected loss cannot be deducted on the original sale.
However, incorrectly claiming a disallowed loss on a tax return can result in an incorrect tax calculation. If this causes an underpayment, the investor may also face applicable interest or tax penalties under normal IRS rules.
Wash sale transactions are generally reported on Form 8949, which is used to report sales and other dispositions of capital assets.
If you receive Form 1099-B, your broker may report a disallowed wash sale loss in Box 1g when the transaction meets the applicable reporting requirements. However, the absence of a reported wash sale does not mean the loss is automatically deductible.
When reporting a wash sale on Form 8949:
Investors should reconcile brokerage statements and their own transaction records before filing, particularly when purchases involve multiple accounts or securities acquired outside a regular brokerage account.
Actual trading scenarios make the wash sale rule easier to understand. The following examples show how timing and replacement share quantities affect the amount of loss investors can deduct.
Suppose you purchase 100 shares of XYZ stock at $50 per share, investing $5,000. The stock falls to $40, and you sell all 100 shares for $4,000, realizing a $1,000 capital loss.
Ten days later, you buy back 100 shares at $39 per share, paying $3,900. Because you repurchased substantially identical stock within 30 days of the loss sale, the entire $1,000 loss is disallowed for the current tax year.
The disallowed loss is added to the replacement shares' cost basis. Your adjusted basis becomes $4,900 ($3,900 + $1,000), or $49 per share. You generally recognize the deferred tax loss when you eventually sell the replacement shares, provided another wash sale does not apply.
The wash sale rule also looks backward. Suppose you purchase 40 additional shares of XYZ stock on May 1 and sell 100 existing shares at a loss on May 15.
If those 40 shares are matched to 40 of the shares sold, the loss attributable to those 40 shares is disallowed. For example, if the total loss is $1,000 and each share has an equal $10 loss, $400 is disallowed while the remaining $600 can generally be deducted.
This is why investors need to review purchases made before selling a losing investment, not just transactions that occur afterward.
A wash sale does not necessarily disallow the entire loss if you repurchase fewer shares than you sold.
For example, you sell 100 shares at a loss of $10 per share, creating a total loss of $1,000. If you purchase only 60 substantially identical shares within the 30-day window, the loss associated with those 60 matching shares, or $600, is disallowed. The remaining $400 can generally be deducted.
The $600 disallowed amount is added to the cost basis of the 60 replacement shares. The actual matching and basis adjustment depend on the shares acquired and sold, so investors should retain detailed transaction records.
Investors can avoid most wash sale complications by planning purchases and sales around the 61-day window. This is particularly important when using tax-loss harvesting to offset capital gains.
The simplest approach is to avoid buying substantially identical securities during the 30 days before and 30 days after selling an investment at a loss.
For example, if you sell shares at a loss on May 15, generally wait until June 15 before repurchasing substantially identical shares. Also review purchases made during the 30 days before the sale.
If you want to maintain market exposure while harvesting a tax loss, consider replacing the security with a genuinely different investment rather than immediately buying it back.
For example, an investor selling an individual technology stock might consider a diversified fund with different holdings and investment characteristics. However, switching between two ETFs does not automatically avoid the wash sale rule. Whether securities are substantially identical depends on the facts and circumstances.
Automatic transactions can trigger wash sales even when investors do not actively place new orders. Before selling an investment at a loss, review:
Keeping detailed transaction records makes tax-loss harvesting easier to manage, particularly near the end of the tax year when investors may be trying to realize losses before December 31.
Not all investments receive the same treatment under wash sale rules. Cryptocurrency and employee stock compensation require additional attention because their tax treatment depends on the type of asset and how shares are acquired.
Under current federal tax law, the traditional wash sale rule generally applies to stocks and securities, rather than ordinary cryptocurrencies. The IRS treats cryptocurrencies such as Bitcoin as property for federal income tax purposes. Therefore, selling Bitcoin at a loss and buying it back within 30 days generally does not trigger the traditional wash sale rule.
However, proposed legislation could change this treatment. H.R. 10357, the Digital Asset Tax Certainty Act, would extend wash sale restrictions to certain traded digital assets, with special treatment for qualifying U.S. dollar stablecoins. The House Ways and Means Committee advanced the bill on September 16, 2026, but committee approval does not make it law. Investors should check its legislative status before relying on the current treatment.
One important distinction is tokenized securities. Digital assets that qualify as stocks or securities for tax purposes can already fall under existing wash sale rules.
Yes. Shares delivered through Restricted Stock Units (RSUs) may trigger a wash sale if they are substantially identical to shares previously sold at a loss within the restricted period.
For example, suppose you sell shares of your employer's stock at a loss and receive additional shares from an RSU award within 30 days. The newly acquired shares may count as replacement shares, disallowing the loss to the extent of the matching quantity.
An RSU grant alone does not necessarily mean you have acquired shares. The vesting and settlement terms matter because the grant date, vesting date, and actual share delivery date may differ.
Investors should also check their cost basis. The fair market value of RSU shares included in taxable wages generally forms the starting basis for those shares. Incorrect basis information can cause investors to overstate or understate their capital gains and losses.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


