


- GBPUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev







omodihot
ID: 5387652
 Chart

A two-pip spread can be more expensive than a three-pip spread when the best offer covers only part of your trade. Rebuild a EUR/USD purchase through several price levels, find the size at which the cheaper route changes, and separate a low partial-fill price from the cost of completing the order.
The narrowest displayed forex spread does not necessarily give the lowest cost for your full order. A price has a quantity attached to it. Once the best offer is exhausted, a larger purchase may have to use higher offers, so a less attractive headline quote with more available quantity can be cheaper overall.
This example compares a hypothetical EUR 400,000 purchase across two accessible EUR/USD books at the same instant and for the same spot value date. It isolates price and quantity: no commissions, financing, rejections, price changes or replenishment occur within the assumed fill. These conditions make the calculation reproducible; an actual displayed book is not a promise that all of its quantities will remain available when an order arrives.
EUR/USD is quoted here in US dollars per euro. A customer buying euros pays the offer, or ask; a customer selling euros receives the bid. One pip in this example is 0.0001 USD per EUR. Book A shows a best bid of 1.0998 and offer of 1.1000, a two-pip spread. Book B shows 1.1000 and 1.1003, a three-pip spread. Both the offer and the displayed spread initially make A look cheaper.
The missing information is how many euros are available at each offer. A best offer of 1.1000 for EUR 100,000 does not price an entire EUR 400,000 purchase. The amount beyond that first level must be evaluated at the prices that actually cover it, under the applicable execution rules.
Nor is one book the whole forex market. BIS research describes spot FX as an over-the-counter market with trading spread across dealers and several types of venue, including order books and requests for quotes. A depth display represents a particular pool and access arrangement, not every euro that might be tradable worldwide.
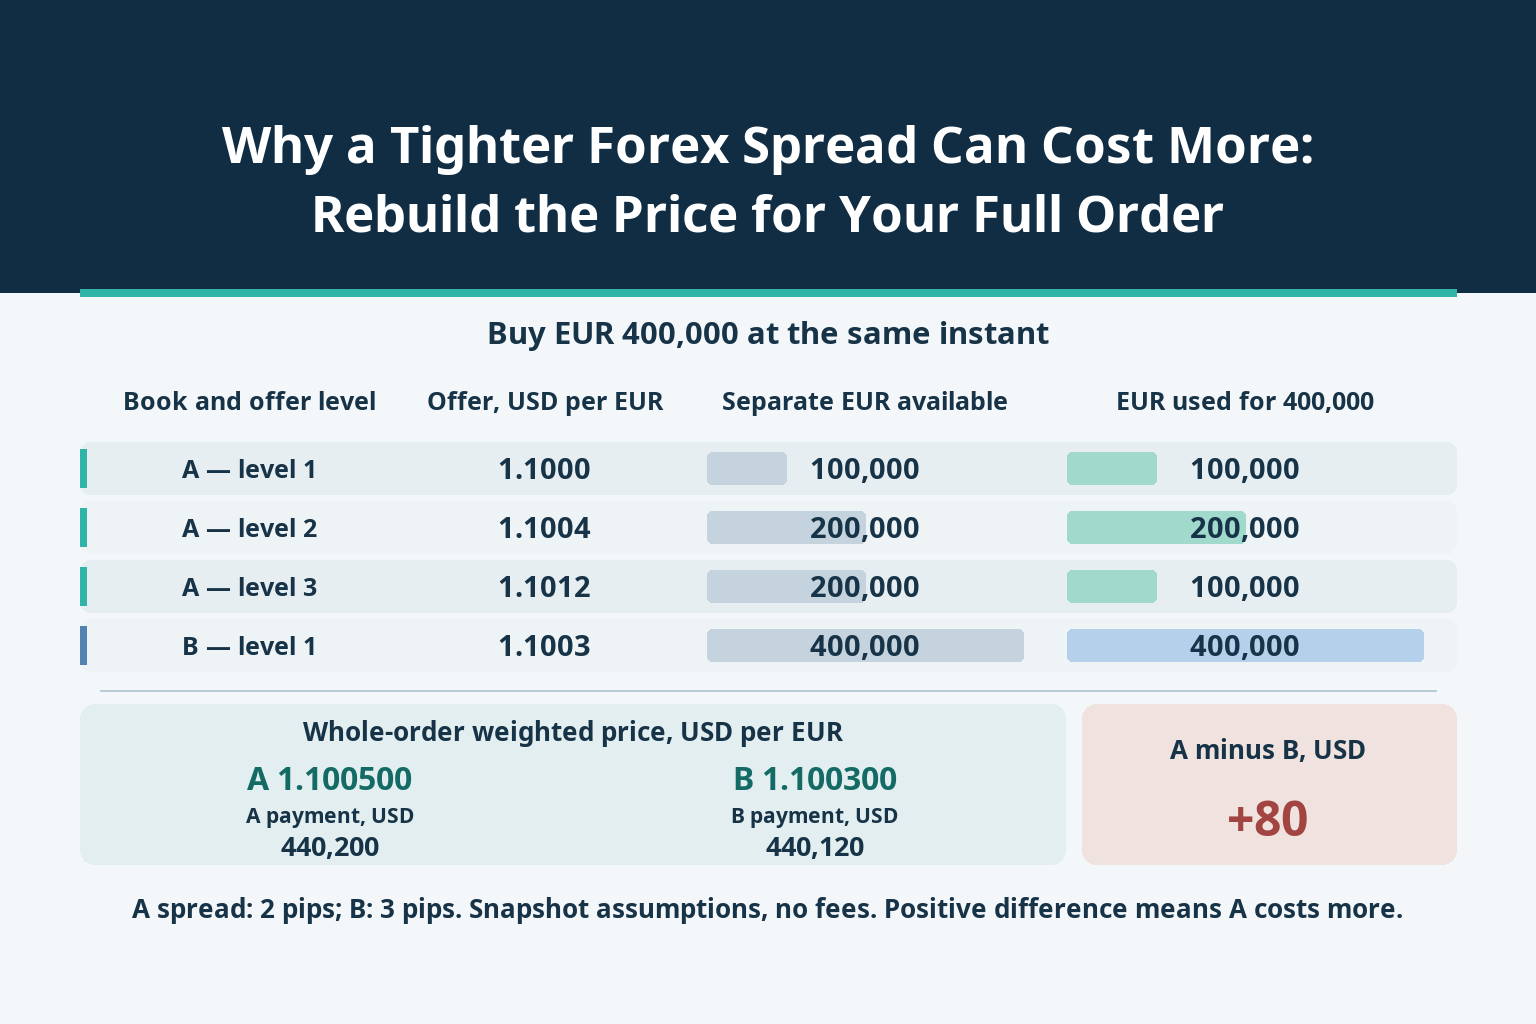
The following hypothetical offers are independently available quantities at each price level in a sweepable book. They are not cumulative totals. In A, EUR 100,000, EUR 200,000 and EUR 200,000 add to EUR 500,000 of offered depth. B has EUR 400,000 at its best offer. The last column shows the amount used when buying EUR 400,000 separately from either book.
| Book and offer level | Offer, USD per EUR | Separate EUR available | EUR used for 400,000 |
|---|---|---|---|
| A — level 1 | 1.1000 | 100,000 | 100,000 |
| A — level 2 | 1.1004 | 200,000 | 200,000 |
| A — level 3 | 1.1012 | 200,000 | 100,000 |
| B — level 1 | 1.1003 | 400,000 | 400,000 |
This convention must be checked, not assumed. If a display instead shows cumulative quantities of EUR 100,000, EUR 300,000 and EUR 500,000, the separate quantities are the differences: EUR 100,000, EUR 200,000 and EUR 200,000. Adding the cumulative figures would incorrectly claim EUR 900,000 of depth.
A full-amount quote ladder is different again: a price for a specified total order from one provider is not automatically extra quantity to combine with its other size quotes. Official electronic FX specifications distinguish sweepable pricing from single-ticket, full-amount pricing. Use the documented book type. An incremental data update describes how messages refresh a book; it does not by itself mean quoted size tiers can be added.
For a buy order, let qᵢ be the quantity actually taken from offer aᵢ. With total filled euros Q=Σqᵢ, dollar payment is C=Σqᵢaᵢ and the volume-weighted average price is C/Q. Fill cheaper eligible offers first in this model and stop when the required quantity is reached. A quantity shown in the book but not used does not belong in the average.
For A, the payment is 100,000×1.1000 + 200,000×1.1004 + 100,000×1.1012 = USD 440,200. The average is 440,200/400,000 = 1.100500. Only half of A’s third-level quantity is needed. Simply averaging its three offer prices would give the wrong weights.
For B, all EUR 400,000 is available at 1.1003, so the payment is USD 440,120 and the average is 1.100300. B costs USD 80 less despite its wider displayed spread. A’s average is five pips above its first offer: 400,000×0.0005 = USD 200. That amount is the cost of using the stated deeper offers relative to filling everything at A’s first offer; it is not an additional commission.
Do not add the two-pip spread again to A’s dollar payment. The purchase already uses offer prices. Nor can this offer-only depth table determine the proceeds from immediately selling all EUR 400,000 back. That calculation requires bid-side quantities and prices for the full amount, not just the best bid.
The comparison is quantity-dependent. The table below applies three separate order sizes to the original, unchanged hypothetical books. Each row starts afresh; it does not reuse liquidity already consumed by an earlier row. A minus B is the difference in dollar payment, so a negative value favours A and a positive value favours B.
| Separate order size, EUR | A payment, USD | B payment, USD | A minus B, USD |
|---|---|---|---|
| 100,000 | 110,000 | 110,030 | −30 |
| 300,000 | 330,080 | 330,090 | −10 |
| 400,000 | 440,200 | 440,120 | +80 |
At EUR 100,000, A saves USD 30. At EUR 300,000, A uses its first two offers and still saves USD 10. At EUR 400,000, its third offer reverses the ranking and A costs USD 80 more. The same two-pip headline spread therefore cannot support a single cost ranking for all sizes.
The crossover can be calculated within the third level. For 300,000<Q≤400,000, A’s cost is 330,080 + 1.1012×(Q−300,000) = 1.1012Q−280, while B’s cost is 1.1003Q. The difference is 0.0009Q−280. Setting it to zero gives Q=280/0.0009, approximately EUR 311,111.11. This is the continuous-size break-even point for this snapshot, before fees; actual permitted quantity increments may put the nearest tradable sizes on either side.
Do not extrapolate that threshold beyond the stated range or treat it as a standing rule. B’s quoted depth ends at EUR 400,000, and either book can change. Fees also matter: if F_A and F_B are dollar charges, compare C_A+F_A with C_B+F_B. At EUR 400,000, B’s USD 80 price advantage disappears if its fee is USD 80 higher than A’s.
Suppose the buyer instead caps the purchase price in A at 1.1004. Under the same snapshot assumptions, only the first two offers qualify: EUR 300,000 is bought for USD 330,080, averaging 1.1002667. EUR 100,000 remains unbought. That lower average cannot be compared as if it were a completed EUR 400,000 purchase.
The treatment of the remainder depends on the order instructions and venue rules. For this separate example, assume the unfilled remainder is cancelled and a new order buys the missing EUR 100,000 later at 1.1016. Total payment becomes 330,080 + 100,000×1.1016 = USD 440,240, with a completed average of 1.100600. It is USD 40 above the original immediate A purchase. The later price is an independent hypothetical outcome, not a forecast or a price available at the original instant.
A better later price could reverse that outcome; cancellation could leave the currency need unfulfilled altogether. The useful distinction is between filled-price control, completion of the required amount and exposure to prices while waiting. None can be inferred from the partial-fill average alone.
The snapshot calculation also stops being an execution prediction if quantities disappear, timestamps do not align, access or credit limits prevent trading, or quotations are subject to acceptance conditions. Requests that can be rejected require a separate check of completion costs; see why rejected forex requests can change the completed trade price. A price ladder and a completed trade report are different evidence.
Start with the same base-currency amount, direction, currency pair and value date. Record the book timestamp, access conditions, best bid and offer, and the price and quantity of every eligible level. Identify whether quantities are per-level, cumulative or full-amount quotes before calculating capacity. A comparison that changes the amount or settlement requirement is no longer comparing the same purchase.
Rebuild the proposed fills without exceeding any level, sum the filled euros and dollar cash, and divide cash by filled euros. Keep the unfilled balance explicit. Compare alternatives only after aligning completion, timing and fees in the same currency. If one route is incomplete, describe the outstanding requirement instead of assigning it zero cost.
After execution, replace the snapshot assumptions with the actual fill quantities, prices, timestamps and charges. Reconcile those amounts to the completed currency purchase and any remaining order. The conclusion is narrow but useful: the best displayed spread is one input; the price for a specified amount comes from the depth that can actually be used under the order’s conditions.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


