


- GBPUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev







omodihot
ID: 5387652
 Chart

A EUR 100,000 purchase can cost USD 260 more than an earlier reference conversion without USD 260 being a fee. Reconcile the reference, the arrival quote, the actual fill and the explicit charge, and distinguish an arithmetic price bridge from proof of what caused the difference.
A forex fill does not have to match a central bank’s published reference rate. The reference may describe an earlier market observation and may not be an offer to trade. A gap between the two amounts can therefore combine differences in time and measurement, the side of the quote used, the eventual fill and separately charged fees.
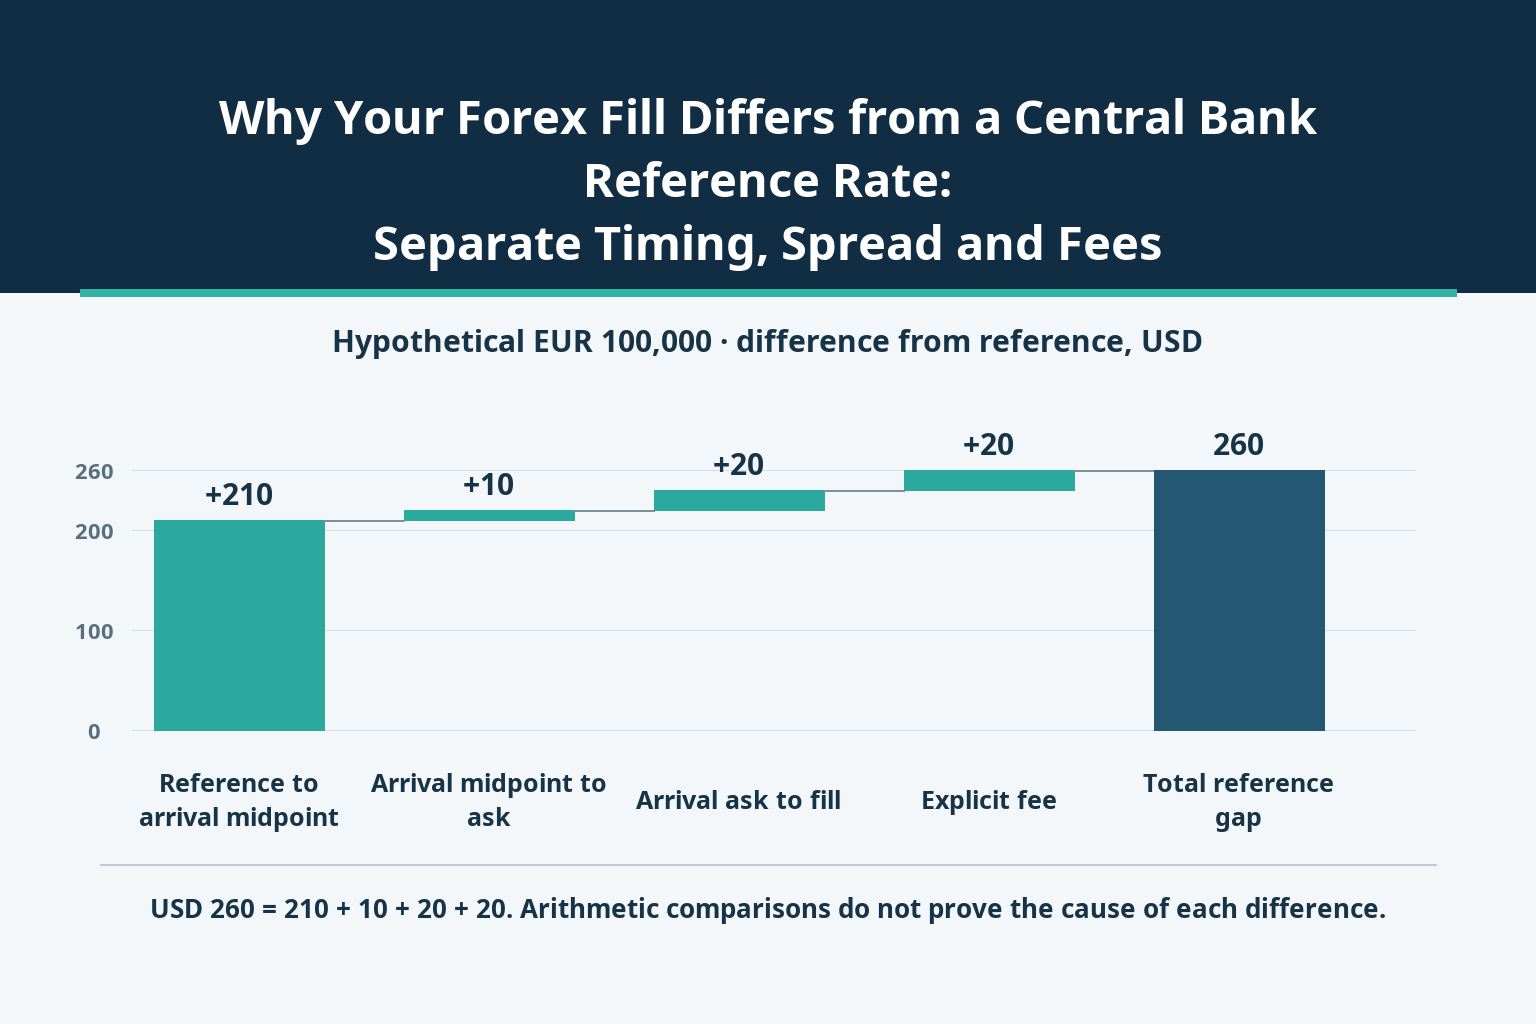
The way to investigate is to compare the same currency amount and follow the price records in order. The hypothetical purchase below ends USD 260 above an earlier reference conversion, but only USD 20 is an explicitly stated fee. The remaining differences are measurable price comparisons; their arithmetic alone neither proves hidden charges nor establishes that execution was fair.
The ECB provides a useful concrete example. Its euro foreign exchange reference rates are published for information, and it strongly discourages their use for transactions. The framework also states that these rates are not intended for market transactions directly or indirectly as an underlying benchmark. A published number therefore does not itself offer a customer a quantity at that price.
The ECB’s current framework distinguishes determination from publication: rates are normally determined around 14:10 CET and published around 16:00 CET. Its reference-rate page also notes that publication normally takes place on working days except TARGET closing days. These are the times and calendar conventions stated by the ECB; the later publication time is not a new observation of the market at that instant.
Identify the specific rate and its stated purpose. Other FX benchmarks, dealer quotes or contractual conversion rules can have different definitions. Do not assume every rate labelled official has the same use, or that a reference date, publication timestamp and your order timestamp describe the same market observation.
Assume a customer buys EUR 100,000 and pays US dollars, with all comparison prices expressed in USD per EUR for a matching spot value date. The earlier informational reference is 1.1000. At order arrival, the accessible quote for the specified amount is bid 1.1020 and ask 1.1022. Its arithmetic midpoint is 1.1021. The actual subsequent purchase fills at 1.1024, with a separately charged USD 20 fee. All values are invented, not ECB observations or current market quotes.
| Record | Value, USD per EUR | Observation stage | Meaning |
|---|---|---|---|
| Informational reference | 1.1000 | Earlier | Comparison value; no assumed fill |
| Arrival bid / ask | 1.1020 / 1.1022 | Order arrival | Two-sided quote for the amount |
| Arrival midpoint | 1.1021 | Order arrival | Calculated; not assumed executable |
| Actual purchase fill | 1.1024 | After arrival | Price used for dollar payment |
The reference conversion is 100,000×1.1000 = USD 110,000. The actual price payment is 100,000×1.1024 = USD 110,240. Adding the fee gives USD 110,260, or USD 260 above the informational comparison. This is a fixed-euro purchase, not a fixed-dollar budget: the euro quantity stays constant while the dollars paid change.
The arrival midpoint is calculated from the two-sided quote; it is not assumed tradable. A euro buyer normally uses the offer side of the quoted market. The record of an arrival ask and a later fill also does not, by itself, explain why they differ. It supplies two points for comparison, not a verdict about execution quality.
Let Q be the euros bought, r the earlier reference, m the arrival midpoint, a the arrival ask, f the fill and F the separate dollar fee. The difference from the reference conversion is Qf+F−Qr. Insert the intervening prices to obtain the identity Q(m−r)+Q(a−m)+Q(f−a)+F. The terms telescope to the actual difference; they do not depend on a claim that the reference or midpoint was executable.
| Arithmetic bridge component | Rate difference, USD per EUR | Dollar contribution |
|---|---|---|
| Reference to arrival midpoint | 0.0021 | 210 |
| Arrival midpoint to ask | 0.0001 | 10 |
| Arrival ask to fill | 0.0002 | 20 |
| Separate fee: equivalent per EUR | 0.0002 | 20 |
Here, 100,000×(1.1021−1.1000) = USD 210 is the reference-to-arrival-midpoint gap. Another 100,000×(1.1022−1.1021) = USD 10 bridges midpoint to ask. The fill is 100,000×(1.1024−1.1022) = USD 20 above the arrival ask. Adding the explicit USD 20 fee gives 210+10+20+20 = USD 260.
The second term is half the two-pip arrival spread in this symmetric arithmetic-midpoint calculation. One pip is defined here as 0.0001 USD per EUR, so one pip on EUR 100,000 equals USD 10. Do not add the full spread again: the actual purchase payment already uses the fill price. The USD 20 fee is added separately only because this model states it is not included in that price payment.
Expressed relative to the reference conversion, the gap is 260/110,000×100 = 0.2363636%, or 23.63636 basis points. That denominator must be named. It is a comparison with USD 110,000, not a declared fee rate, a measured round-trip spread or a percentage return on trading capital.
Take a separate comparison scenario in which the earlier informational reference was instead 1.1030, while the arrival quote, actual fill and USD 20 fee remain exactly as above. The reference conversion would be USD 110,300, but actual total payment would still be USD 110,260. The gap is now −USD 40: the customer pays less than that earlier comparison amount.
The bridge still works. The reference-to-arrival-midpoint term becomes 100,000×(1.1021−1.1030) = −USD 90. The other terms remain +USD 10, +USD 20 and +USD 20. Thus −90+10+20+20 = −USD 40. The explicit fee has not disappeared merely because the all-in result beats an earlier reference.
Likewise, a positive gap in the first scenario does not prove the whole difference was charged by the dealer. A different informational starting point changes the comparison without changing the executed trade. These are independent hypothetical reference scenarios, not two published rates for the same observation or a claim that one can choose a preferred official rate after trading.
Compare service offers using a consistent amount and timing, then reconcile the actual cash and disclosed charges. If the objective is choosing between executable conversion offers rather than explaining a historical reference gap, see how to compare currency-exchange offers by net receipts. An earlier reference is useful context, but it cannot replace like-for-like transaction terms.
The USD 210 term combines a time gap with any difference between the reference methodology and the selected arrival quote. It is not automatically a pure market-movement measure. Calling all USD 210 market movement would require evidence that the two observations were otherwise comparable. Calling it a provider fee would also require separate evidence.
The USD 20 fill-versus-ask term is similarly an observed difference. Possible questions include whether the quote was firm for the amount, whether it remained valid, what happened between timestamps, which execution conditions applied and whether the fill record includes a pricing adjustment. The identity cannot decide among those explanations. A positive difference does not establish misconduct; correct arithmetic does not establish acceptable execution either.
A reference retrieved on a non-publication day may still relate to the previous available observation. Do not silently turn the retrieval date into the rate’s observation date, or treat a missing new reference as proof the market did not move. If the reference source, timestamp or quote units cannot be established, leave that part of the comparison unresolved.
Keep value dates and products aligned as well. A spot reference, a forward outright and a retail conversion with different settlement terms are not automatically comparable quotes. This example excludes financing, taxes and other charges. If actual fees are deducted from the euros delivered instead of added in dollars, both the quantity and cash reconciliation must be rebuilt rather than copied from this fixed-euro model.
Record the reference series, quoted units, observation date or determination convention, publication time and latest available data date. Next record the requested euro amount, direction, value date, order-arrival timestamp, bid and ask for that amount, quote conditions, actual fills and explicit fee entries. A screenshot showing only the reference and final debit is not enough to identify the intermediate terms.
First verify actual cash: multiply each fill quantity by its price, sum the dollar payments and add only fees not already included. Then build the comparison bridge using consistent units and unrounded working values. For the first scenario, the four contributions must total USD 260; for the alternative reference scenario, they must total −USD 40. Round the displayed results after calculating.
Finally separate what is known from what still needs evidence. The statement establishes the money paid, the quote records establish particular observed prices, and the reference documentation establishes the scope of the published rate. Together they can explain the arithmetic gap. They do not turn an informational rate into an executable promise or turn every difference from it into a fee.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


