


- EURUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev











Headline nonfarm payrolls rose +22k last month, considerably below consensus expectations for a +75k increase, but within the typically wide forecast range of 0k to +115k. Concurrently, the prior two payrolls prints were revised by a net -21k, in turn taking the 3-month average of job gains to a rather dismal +29k, probably around half the breakeven pace.
Headline nonfarm payrolls rose +22k last month, considerably below consensus expectations for a +75k increase, but within the typically wide forecast range of 0k to +115k. Concurrently, the prior two payrolls prints were revised by a net -21k, in turn taking the 3-month average of job gains to a rather dismal +29k, probably around half the breakeven pace.
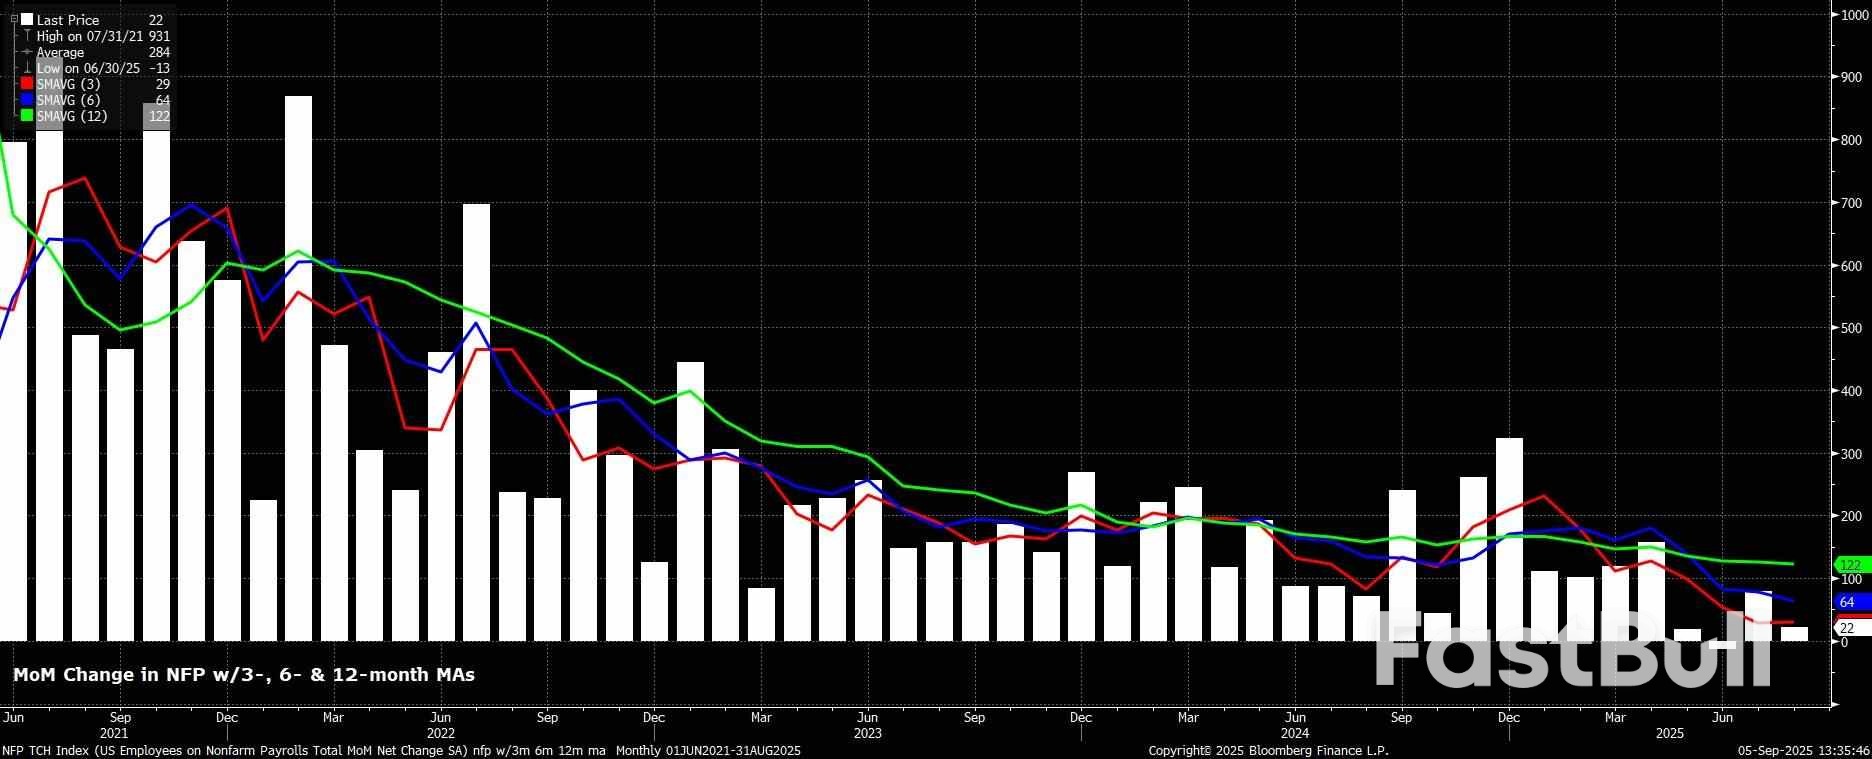
Taking a look under the surface of the payrolls print, things look rather glum. A majority of sectors saw employment decline in August, with those job losses led by Professional & Business Services, and Government employment. Once more, Healthcare (+46k) was the notable growth sector, and continues to prop up the headline figure at large.
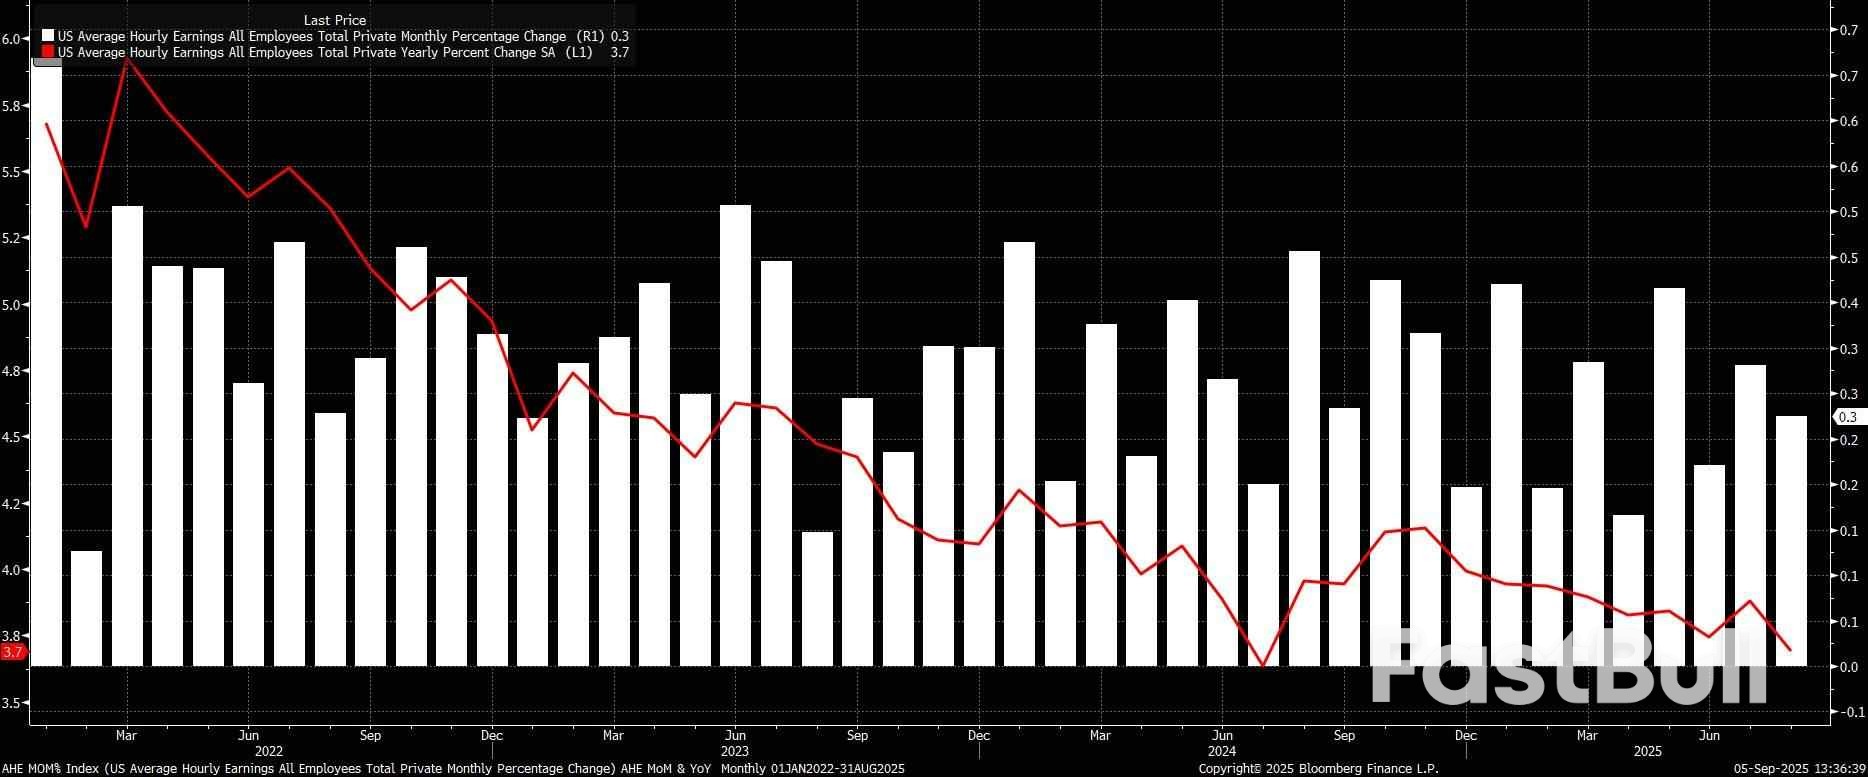
Staying with the establishment survey, the jobs report pointed to earnings pressures again remaining well-contained, reinforcing the FOMC's long-standing view that the labour market is not a source of significant upside inflation risks at the current time.
Average hourly earnings rose 0.3% MoM, bang in line with expectations, which in turn saw the annual rate cool to 3.7% YoY.
Turning to the household survey, headline unemployment rose to 4.3% last month, in line with expectations, and to a fresh cycle high. This, however, was accompanied by an unexpected rise in labour force participation, to 62.3%.
As has now been the case for some time, though, some degree of caution is still required in interpreting this data, as the BLS continue to grapple not only with a sharp decline in survey response rates, but also amid the rapidly changing composition of the labour force.
In reaction to the jobs report, market participants continue to fully price a 25bp cut in September, while also now pricing around 66bp of easing by year-end, up from 59bp pre-release, and implying around a 2-in-3 chance of three cuts being delivered this year.
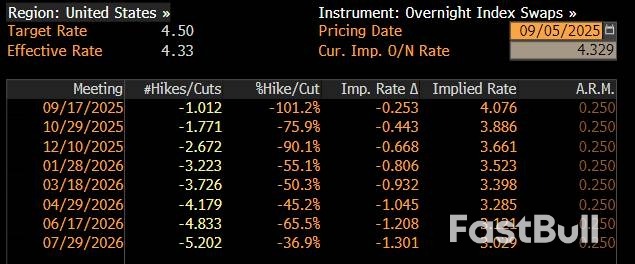
Stepping back, the August jobs report does not materially alter the near-term FOMC policy outlook, and confirms that the labour market continues to lose momentum.
After Chair Powell's dovish pivot at Jackson Hole, a 25bp cut at the September meeting remains locked-in, as the FOMC look set to take out ‘insurance' against a loss of momentum in the labour market. While there are likely to be some dissenters in favour of a larger rate reduction, such a move shan't command support from a majority of Committee members, given continued concern over upside inflation risks, and the desire to ensure that inflation expectations remain well-anchored.
Looking ahead, while the September ‘dot plot' may give a clearer steer on the likely pace of easing through year-end, my base case is that the September cut will be followed with another such move at the December meeting. Risks to this view, though, arguably tilt marginally in a dovish direction, were material labour market weakness to emerge, though the bar to more aggressive easing is clearly a high one, with headline inflation having been north of target for four-and-a-half years, and being set to accelerate further over the next six months or so.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


