


- EURUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev











A stock payment can fall due before the currency purchased to fund it arrives. Compare an earlier FX value date with a committed dollar bridge loan, count weekend interest correctly, and test whether the return forgone on euros reverses the cheaper route.
A cheaper-looking exchange rate is not necessarily the cheaper way to fund a stock purchase. If dollars arrive a day after the stock payment is due, the comparison must include the money borrowed to bridge the gap—and enough currency to repay its interest. The alternative is not to pay the stock bill late; it is to obtain the required dollars on the earlier date.
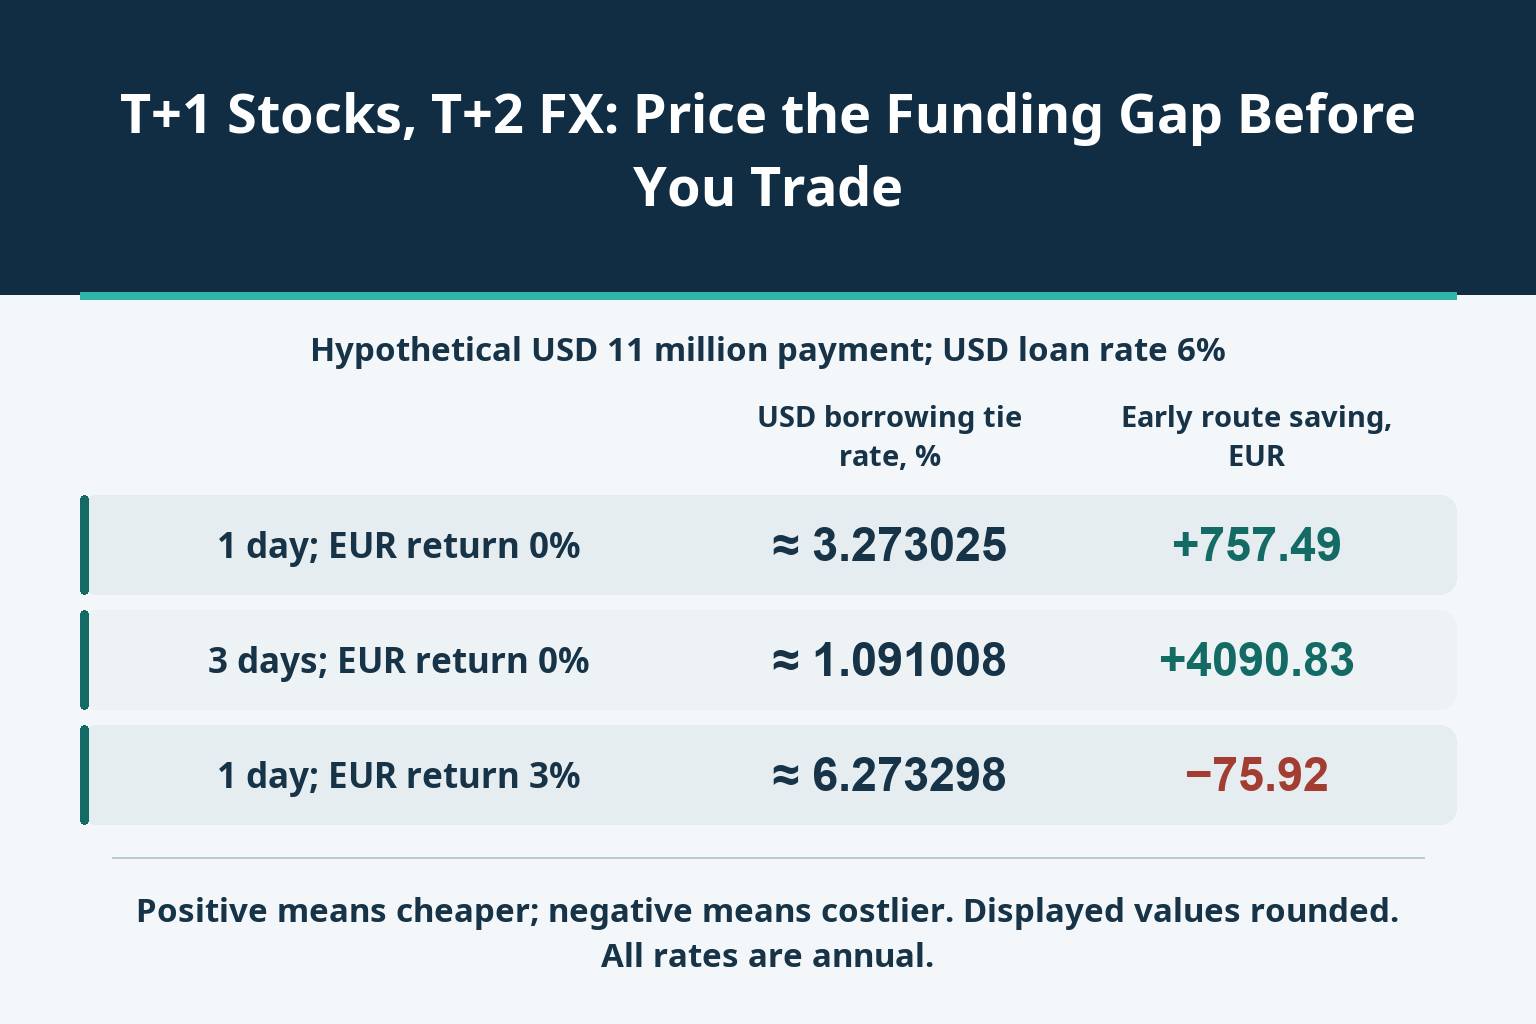
In the hypothetical case below, an earlier EUR/USD value date has a less favourable exchange rate but saves EUR 757.49 against a one-day dollar loan. Across a weekend, the saving rises to EUR 4,090.83. Yet allowing the euros to earn 3% before they are needed reverses the one-day result: the earlier conversion costs EUR 75.92 more on a common-date basis. The decision turns on dated cash flows, not the spot quote alone.
For covered US securities transactions, the T+1 standard took effect on May 28, 2024. It does not mean every security worldwide settles the next day. Nor did the change automatically shorten every currency pair’s settlement cycle. The relevant stock trade confirmation and FX confirmation must identify their own payment dates.
Use EUR/USD here with an ordinary T+2 value date, and consider a separately quoted T+1 conversion. T is the trade date; the business-day labels do not promise cash within 24 or 48 hours. Different currencies and markets have exceptions. A local holiday, an overseas holiday or an earlier operational cut-off can change what is actually available. The investor’s home calendar alone is insufficient.
The first question is therefore practical: what currency must reach which account, by what time, to settle this particular stock purchase? A screen showing an executed FX trade answers the price question, not necessarily the funds-availability question. A later currency receipt is not a substitute for the required stock payment, and a funding shortage does not automatically grant an extension of securities settlement.
Assume a USD 11,000,000 stock payment is due at T+1. Euros are already available in sufficient amount at T+1. On trade date, the investor can obtain an ordinary T+2 conversion at S = 1.10000 dollars per euro, or an earlier T+1 conversion at E = 1.09990 dollars per euro. Both quotes are assumed executable for the necessary amounts and account. The investor sells euros and buys dollars, so the lower E delivers fewer dollars for each euro: it is the worse exchange rate in isolation.
The early route pays P/E euros at T+1 and receives the P dollars needed for the stock bill. The ordinary route uses a committed USD 11,000,000 bridge loan at T+1, settles the same stock purchase, then uses the T+2 FX receipt to repay the loan. Assume the dollar loan charges a fixed 6% annual rate, simple interest and actual calendar days divided by 360. These are model terms, not a universal lending convention.
Crucially, the ordinary conversion arranged on trade date must buy the whole dollar repayment, P(1 + rd/360), not just the stock principal P. Buying USD 11,000,000 leaves the interest unfunded. Waiting until T+2 to buy that interest at an unknown rate also creates a different strategy from the locked-rate comparison here.
With euros initially assigned a zero opportunity return, ordinary-route euro cost is L = P(1 + rd/360)/S; early-route cost is A = P/E. The early outlay is EUR 10,000,909.173561. The model excludes separate commissions, taxes and additional credit charges. The conversion prices already contain their respective quoted exchange terms; the same spread must not be deducted again.
Consider two separate, hypothetical weeks with no relevant securities, dollar or euro holidays. All payment cut-offs can be met. A Friday stock trade settles Monday, while its ordinary T+2 FX settles Tuesday. Borrowing from Monday to Tuesday therefore spans one calendar day. A Thursday stock trade settles Friday, while ordinary FX settles Monday: that bridge spans three calendar days.
Both are one business-day mismatches, but the assumed loan accrues over actual calendar days. At 6%, one-day interest is 11,000,000 × 0.06/360 = USD 1,833.333333. The ordinary FX must provide USD 11,001,833.333333. Across three days, interest is USD 5,500 and the required currency receipt is USD 11,005,500.
| Separate case | Calendar days funded | USD interest | USD repaid at T+2 | Ordinary route, EUR | Early route, EUR | Early route saving, EUR |
|---|---|---|---|---|---|---|
| Friday trade: Monday to Tuesday | 1 | 1833.333333 | 11001833.333333 | 10001666.666667 | 10000909.173561 | 757.493105 |
| Thursday trade: Friday to Monday | 3 | 5500.000000 | 11005500.000000 | 10005000.000000 | 10000909.173561 | 4090.826439 |
All euro amounts in this first table assume zero euro opportunity return. The six decimal places expose the calculation; actual cash payments follow the relevant contractual rounding rules. Savings are calculated from unrounded amounts before display, not by subtracting previously rounded components.
The repeated S and E quotes are inputs to two independent examples, not a claim that actual Thursday and Friday markets offer identical value-date pricing. Real earlier-date quotes can reflect the weekend and each account’s funding conditions. The table isolates the calendar effect; it is not evidence of an arbitrage or a forecast of dealing spreads.
The less favourable early conversion uses approximately EUR 909.17 more than the EUR 10 million that would buy the stock principal alone at S. That is the exchange-price disadvantage. But the ordinary route must also fund the dollar loan interest. Compare both effects in euros, rather than adding a dollar interest amount directly to an exchange-rate difference.
With zero euro opportunity return, setting L = A gives r* = (S/E − 1) × 360/d. For one day, the exact decimal annual rate is 360/10999, or approximately 3.273025%. For three days it is 120/10999, approximately 1.091008%. Equality only ties the two routes; a dollar borrowing rate strictly above the applicable threshold makes the early route cheaper under these assumptions.
The assumed 6% exceeds both thresholds. That explains why the early conversion can win despite its worse exchange rate. It does not mean a three-day market loan should carry one-third of the rate on a one-day loan. These are break-even rates for fixed hypothetical quotes, not observed loan rates or a general pricing law. A different quote, fee structure or day-count convention requires a fresh calculation.
The first comparison treated euros as free to hold. But the early route pays them at T+1, whereas the ordinary route retains them until T+2. If the retained euros can genuinely earn an annual rate g over the gap, value both routes at T+2. Under another explicit simple actual/360 assumption, the early outlay’s common-date equivalent is A₂ = (P/E)(1 + gd/360).
Take the one-day case and change only the euro opportunity rate from zero to 3%. The dollar loan remains 6%; both FX quotes remain unchanged. The early route’s T+2 equivalent rises to EUR 10,001,742.582659. Ordinary-route cost remains EUR 10,001,666.666667, making the early route more expensive by EUR 75.915992.
| EUR opportunity rate, % a year | Ordinary route at T+2, EUR | Early route equivalent at T+2, EUR | Early route saving, EUR | USD borrowing tie rate, % a year |
|---|---|---|---|---|
| 0 | 10001666.666667 | 10000909.173561 | 757.493105 | ≈ 3.273025 |
| 3 | 10001666.666667 | 10001742.582659 | −75.915992 | ≈ 6.273298 |
The revised dollar borrowing threshold is r* = [(S/E)(1 + gd/360) − 1] × 360/d. At g = 3% and d = 1, it is exactly 690/10999 as a decimal annual rate, approximately 6.273298%. The assumed 6% is now below the threshold. This is an economic comparison at a shared date, not an extra EUR 75.92 fee charged by the FX provider.
Use a return that the cash can actually earn over the relevant interval while remaining available for payment, after the costs applicable to that alternative. An inaccessible term investment or a risky expected return is not automatically a like-for-like cash opportunity rate. If euros themselves must be borrowed, trace that funding contract instead of silently treating owned cash and borrowed cash as interchangeable.
A credit line must cover the required dollar amount and allow withdrawal before the stock-payment cut-off. An approved limit is not evidence that cash has arrived. Minimum interest, commitment charges, draw fees or extra custody charges may change the result. Put each charge in its contractual currency and on its actual date, then compare both complete routes on one basis.
Also check the last hours of the cash chain. An FX receipt with the same value date as a loan repayment may arrive after the repayment cut-off; likewise T+1 dollars may arrive too late for the custodian’s stock payment. That can require additional intraday liquidity even when the calendar dates align. A promised price and a matched date do not guarantee timely payment.
This timing problem is distinct from FX principal settlement risk and payment-versus-payment protection. A mechanism designed to limit loss of exchanged principal does not itself finance a stock bill. Conversely, a bridge loan that funds the bill does not remove every risk of the currency exchange. Keep those questions separate instead of declaring the whole transaction safe because one date mismatch was solved.
The two routes compared here are an earlier-value-date currency purchase and an ordinary currency purchase combined with a loan. They are alternatives, not instructions to execute both. Merely quoting two value dates does not create a complete two-legged FX swap; such a trade would need its own confirmed legs and cash flows.
The useful decision is not “T+1 is better” or “the higher EUR/USD quote wins.” It is which available route delivers the required dollars on time at the lower complete cost, after accounting for the actual calendar and the cash given up along the way.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


