


- AUDUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev









A high correlation is not a reason to fade a price gap. Separate cointegration evidence, share sizing, expected convergence speed and the cash costs that can turn a winning spread into a losing trade.
Two stocks can move in the same direction for years while the gap between them keeps widening. Buying the apparent laggard and selling the leader then becomes a bet on a relationship that may never have existed. Correlation describes co-movement; a mean-reversion trade needs evidence that a specifically defined spread remains stable. Even that evidence does not settle whether the position can be financed and closed profitably.
The practical task is to connect three separate objects: the statistical residual, the actual shares traded and the cash ledger. A low test p-value, an attractive chart or a small net cash outlay cannot substitute for this reconciliation.
Return correlation measures linear co-movement over the chosen sample. Cointegration asks a different question: can a linear combination of individually integrated price series be stationary? For a simple level model, write X = a + bY + u. If X and Y are each integrated of order one and u is stationary, they are cointegrated under that specification. The spread S = X − bY fluctuates around a. High price-level correlation alone does not establish this property.
Estimate a and b on a declared training period, align timestamps and currencies, and handle splits and distributions consistently. A stale closing price on one exchange can manufacture a gap. Raw prices, log prices and total-return indexes are not interchangeable inputs: each defines a different residual and may imply different tradable exposures.
A residual-based cointegration test must use critical values appropriate to the estimated relationship, deterministic terms and sample, not simply the ordinary unit-root p-value for an observed series. The usual two-step null is no cointegration. Rejecting it provides conditional statistical evidence, not proof that convergence will occur before funding runs out; failing to reject does not prove the relationship is absent.
Use hypothetical stocks quoted in dollars, with no dividends or corporate actions during this example. A previously fitted level relationship has a = 10 and b = 2. At X = 114 and Y = 50, S is 14, or 4 above its fitted mean. If the training residual standard deviation is 2, the standardized deviation is +2. This does not assign a 95% probability of reversal: normality, independence and stable parameters have not been established.
A short-spread illustration sells 100 shares of X and buys 200 of Y. At entry, gross exposure is $21,400, while the sale proceeds exceed the purchase cost by $1,400. That credit is not profit or the required margin. With fixed quantities, its price profit is:
Profit = 100 × [(X₀ − 2Y₀) − (X₁ − 2Y₁)]
| Closing X | Closing Y | Spread X − 2Y | Gross profit or loss |
|---|---|---|---|
| 120 | 55 | 10 | +400 |
| 108 | 49 | 10 | +400 |
| 126 | 52 | 22 | -800 |
Both prices can rise or both can fall while the same $400 convergence profit is earned. Conversely, the last scenario loses $800 despite the two stocks rising together. The spread, not the sign of the market move, drives this simplified calculation.
The share ratio of two applies only to this raw-price, same-currency model. In a log-price model, b is a local proportional sensitivity; converting it into shares involves current prices and subsequent rebalancing. A regression hedge is not automatically dollar-neutral or market-beta-neutral. Adjusted historical prices must also be mapped back to executable share units rather than traded as imaginary index units.
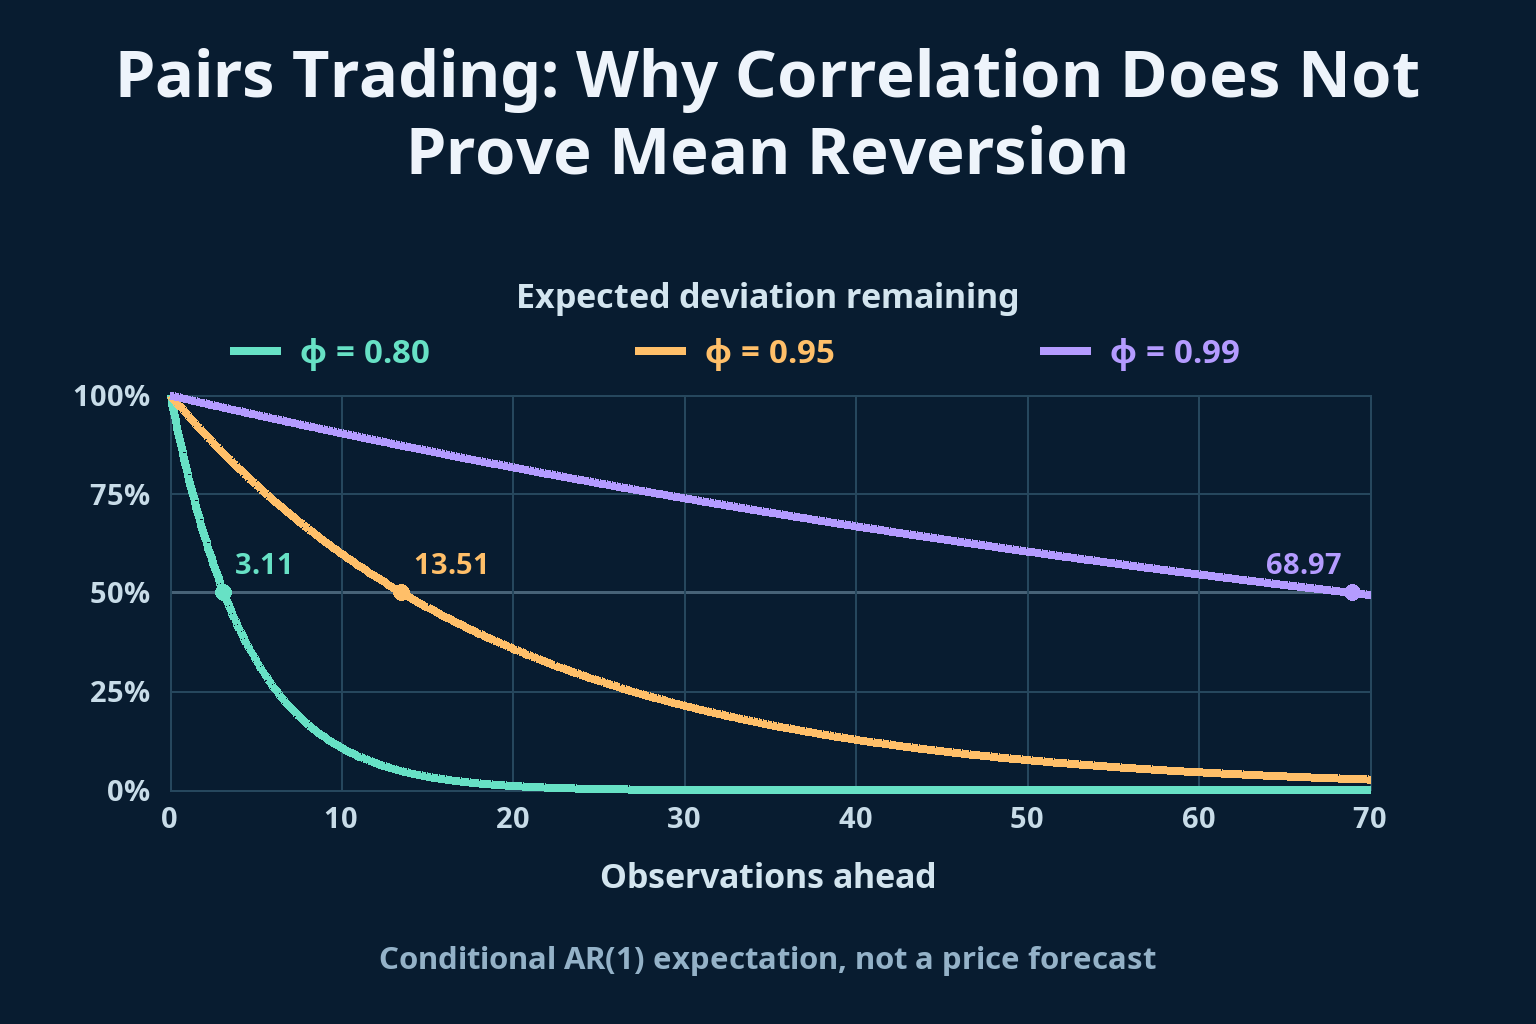
Suppose the deviation from the mean follows uₜ = φuₜ₋₁ + εₜ, with innovations of zero conditional mean and constant 0 < φ < 1. Conditional on today's deviation, its expected value after k observations is φᵏu₀. The half-life is ln(0.5)/ln(φ): about 3.11 observations at φ = 0.80, 13.51 at 0.95 and 68.97 at 0.99.
These are daily periods only if the model was fitted to daily observations. They are neither median first-passage times nor deadlines by which half a loss must recover. Individual paths can widen sharply while their conditional mean decays. Near one, small estimation errors produce very different half-lives; at one there is no finite mean-reversion half-life in this model. Negative or more complex dynamics require another interpretation.
Compare the estimated timescale with the financing horizon and with the length of the available record. A purported 69-observation half-life inferred from a short, unstable sample is weak operational evidence. Re-estimating the mean after every adverse move can disguise a broken relationship as an endlessly renewed opportunity.
Returning from S = 14 to 10 earns $400 before costs in the fixed-share example. Total execution, borrow and funding costs of $80 leave $320; costs of $450 produce a $50 loss despite perfect convergence. These are hypothetical all-in bills, not current broker tariffs. For 100 spread units, the cost break-even move is total dollars of cost divided by 100: 0.8 spread points for $80.
Account for opening and closing both legs, borrow availability and recall, dividends owed on the short, financing, taxes where relevant and the treatment of sale proceeds. A borrow recall can end the trade before the model's horizon. A one-sided fill creates temporary directional exposure. Net sale proceeds do not remove gross-position margin requirements or losses after a gap.
Structural change matters more than a prettier z-score: an acquisition, business-model change, new share class or permanent financing shock can move the equilibrium. Predetermine conditions for suspending the model, rather than promising that every larger deviation offers better value.
Searching thousands of pairs introduces another selection problem. The audit of backtest overfitting and multiple trials explains why the winner must be assessed in the context of the search. Cointegration can justify further investigation of a spread; it does not turn an estimated relationship into a contractual obligation for prices to reunite.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


