


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev










A gold price rally does not flow straight into mining shareholders’ pockets. Rebuild the AISC margin into cash, test sales and cost assumptions, and distinguish a financing gap from a valuation opportunity.
Gold rises 10%, yet a miner has less cash left at the end of the year. That need not involve an accounting mystery. Fewer ounces sold, higher input prices and spending outside the headline cost measure can absorb the benefit. The key is to follow the money from the price actually received to the obligations still waiting to be paid.
All-in sustaining cost, or AISC, helps describe the economics of sustaining gold production. It does not turn the gap between gold and unit costs into distributable cash. A mining share is a claim on a business with reserves, investment needs and financing commitments—not a fixed multiple of the metal’s daily return.
AISC is a non-GAAP measure, so begin with the issuer’s reconciliation, not a comparison website’s headline number. Sustaining capital and corporate costs may already be included. Expansion spending, corporate income taxes and ordinary borrowing interest require separate examination. Lease payments are an important exception to simplistic rules about finance costs: the updated World Gold Council guidance includes the principal and financing components of relevant lease payments.
Nor is AISC necessarily an entirely cash-paid total. Share-based remuneration and other accounting adjustments can enter the calculation. For a real cash bridge, identify those items and reconcile timing differences rather than subtracting every reported cost from bank receipts. Keep company-level and mine-level figures, ownership scope, currencies and reporting periods consistent.
Consider a hypothetical annual model, not a forecast or a quotation for an actual producer. The company sells all 100,000 ounces produced at a realized price of $3,000 an ounce. Its $170 million sustaining-cost pool includes corporate expenses and sustaining capital. For this example only, all of that pool is paid in cash during the year, with no noncash charges, by-product credits, hedges or ownership differences.
AISC is therefore $1,700 an ounce. Revenue is $300 million and the amount remaining after sustaining costs is $130 million. Now subtract $25 million of expansion capital, $8 million of cash interest on non-lease debt, $20 million of corporate income tax and $12 million of additional working-capital funding. Those four items total $65 million; the model’s remaining cash is also $65 million.
This is a defined scenario subtotal before debt principal and shareholder distributions. It is not a universal free-cash-flow formula or a financial-statement line item. Corporate costs and sustaining capital are already inside the $170 million, so deducting them again would understate the result. Conversely, calling the entire $130 million “free cash flow” would omit the specified additional uses.
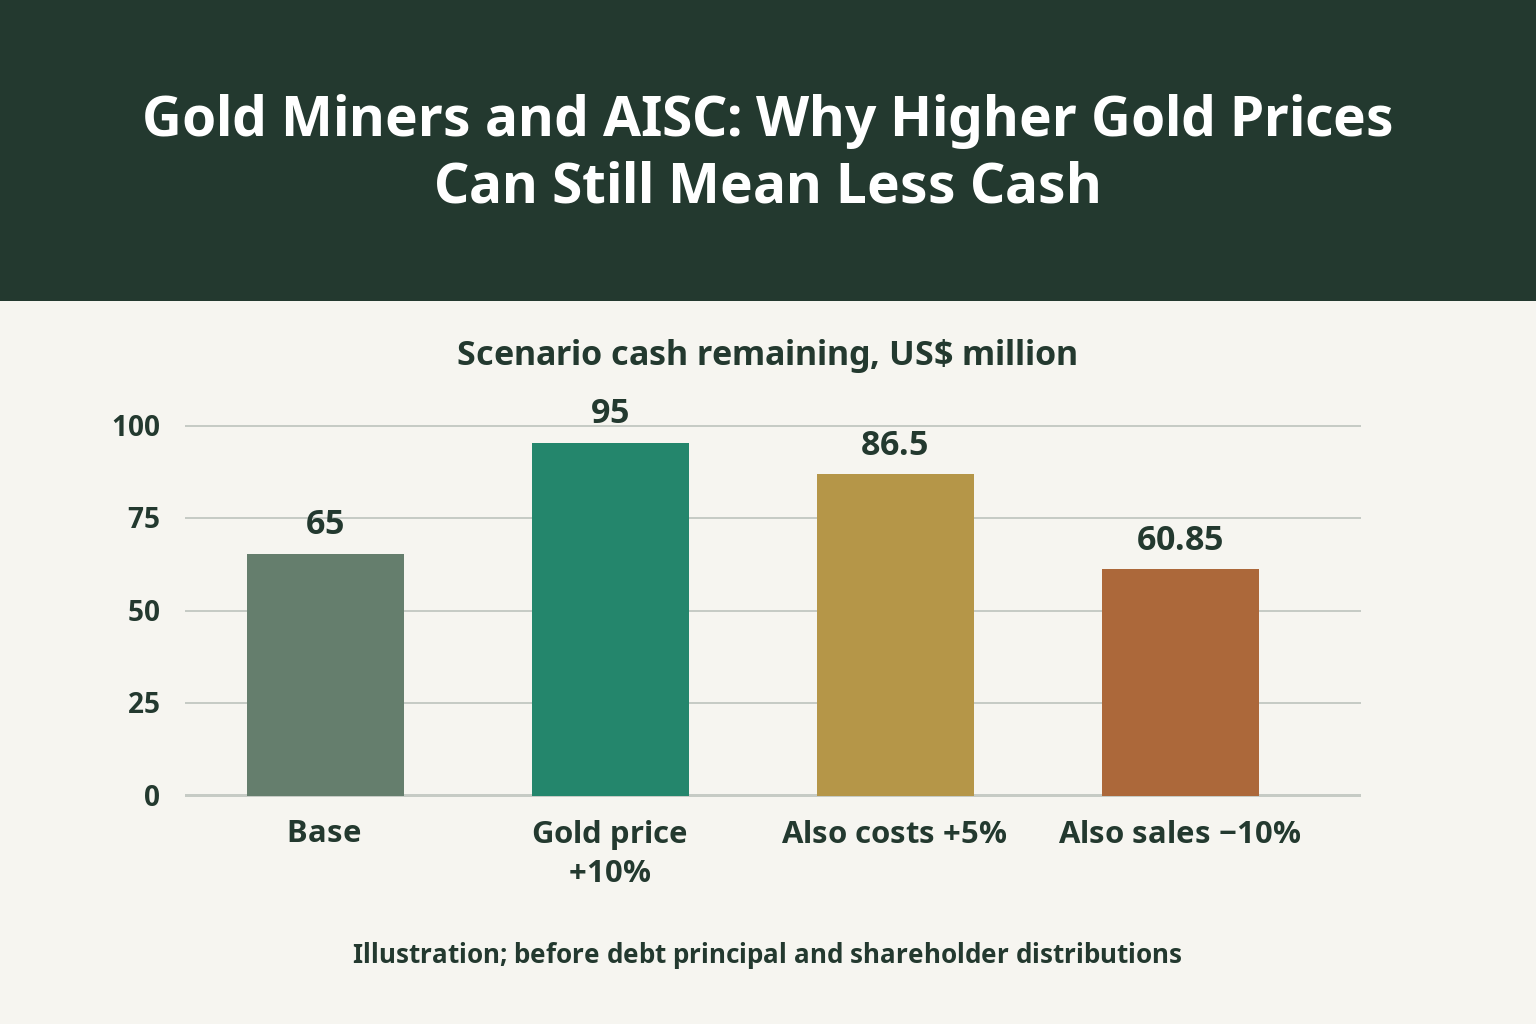
Split the sustaining-cost pool into $100 million fixed for the modeled year and $700 per ounce sold. If only the realized gold price rises 10% to $3,300, revenue becomes $330 million. Costs stay at $170 million, the additional uses remain $65 million, and cash remaining reaches $95 million: a 46.15% increase. That is operating leverage under stated assumptions, not a prediction for the share price.
Now increase both fixed and variable input costs by 5%. With sales unchanged, costs become $178.5 million and remaining cash falls to $86.5 million. Finally, reduce sales 10% to 90,000 ounces. Fixed costs are still $105 million; variable costs are $735 × 90,000 = $66.15 million. Total sustaining costs are $171.15 million, while revenue is only $297 million.
| Annual scenario | Base | Gold price only | Combined pressure |
|---|---|---|---|
| Realized gold price, $/oz | 3,000.00 | 3,300.00 | 3,300.00 |
| Ounces sold | 100,000 | 100,000 | 90,000 |
| Revenue, $m | 300.00 | 330.00 | 297.00 |
| Fixed sustaining costs, $m | 100.00 | 100.00 | 105.00 |
| Variable sustaining costs, $m | 70.00 | 70.00 | 66.15 |
| Total sustaining costs, $m | 170.00 | 170.00 | 171.15 |
| AISC, $/oz | 1,700.00 | 1,700.00 | 1,901.67 |
| After sustaining costs, $m | 130.00 | 160.00 | 125.85 |
| Additional cash uses, $m | 65.00 | 65.00 | 65.00 |
| Remaining cash, $m | 65.00 | 95.00 | 60.85 |
After the same $65 million of additional uses, just $60.85 million remains—6.38% less than the base case despite a gold price 10% higher. AISC rises to about $1,901.67 an ounce. Reusing the old $1,700 unit cost and multiplying by fewer ounces would incorrectly make fixed spending disappear.
The four bars isolate these effects in sequence. Taxes, expansion spending and working-capital funding are held constant to keep the arithmetic auditable; a real forecast must recalculate them. Royalties may also respond to price, and lower output does not always reduce variable costs proportionately. The stress case demonstrates vulnerability, not the probability of that outcome.
By-product credits can lower gold AISC when another metal sells for more, even if the gold operation has not become more efficient. Newmont’s full-year 2025 release illustrates the size of the presentation difference: gold AISC was $1,358 an ounce on a by-product basis and $1,609 on a co-product basis. The $251 gap is a difference in allocation, not evidence that the same mines suddenly changed their underlying costs.
Also check the denominator: ounces sold are not always ounces produced. Inventory movements, acquisitions, disposals and attributable versus consolidated reporting can defeat an apparently straightforward comparison. A lower mine-site measure may exclude overhead present in the group number. A cost league table is useful only after these definitions are reconciled.
Spending classified as growth rather than sustaining also affects the headline. Examine the project and the reconciliation before treating a lower AISC as improved efficiency. Maintenance deferred into a later year can improve current cash without improving the asset’s economic life.
Under the base assumptions, the model’s cash subtotal reaches zero at ($170 million + $65 million)/100,000 = $2,350 per ounce. Under the combined-pressure assumptions, the corresponding number is ($171.15 million + $65 million)/90,000, or about $2,623.89. These are one-year scenario thresholds, not mine-closure prices, intrinsic values or promises that a producer is safe above them.
Suppose the stressed company also has $50 million of debt principal due. The $60.85 million subtotal leaves only $10.85 million before distributions, acquisitions and other excluded commitments. Existing cash, committed facilities, restrictions and maturities now matter. Refinancing is a possible funding source, not an assumption that can be silently guaranteed.
A profitable current year can coexist with a falling share price if investors already expected more, the mine’s remaining life is shorter, or future investment and risk have risen. Conversely, spending on a sound project can depress this year’s cash while adding future value. The model identifies cash drivers; valuing the equity still requires multiple periods and the claims ahead of shareholders.
A durable improvement would be supported by stronger realized prices without a matching deterioration in sales, recovery rates, maintenance needs or cash conversion. A quarter helped by selling stored gold or postponing supplier payments is different. The same distinction appears in checking whether operating cash-flow growth comes from working-capital release: cash can be real without being repeatable.
The attractive-margin thesis weakens if achieved prices lag the assumed price, payable ounces fall, sustaining work catches up or near-term financing consumes the surplus. None of those observations alone proves misreporting. They identify an assumption to revise and a disclosure to examine.
The useful question is not simply whether gold trades above AISC. It is how much of the price advantage survives the miner’s actual sales, spending and obligations—and whether that survival is already reflected in the share price.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


