


- EURUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev
















A negative accrued-interest line reduces a gilt’s settlement payment because the buyer misses the imminent coupon. Reconcile the record-date boundary, a £3,000 coupon error and penny rounding without mistaking a lower invoice for an investment gain.
A gilt purchase can show negative accrued interest without having a negative coupon or a negative yield. The adjustment concerns who receives the next coupon. After the entitlement cutoff, the buyer pays less at settlement but does not receive that imminent payment. Reading only the smaller invoice creates a misleading impression of a discount.
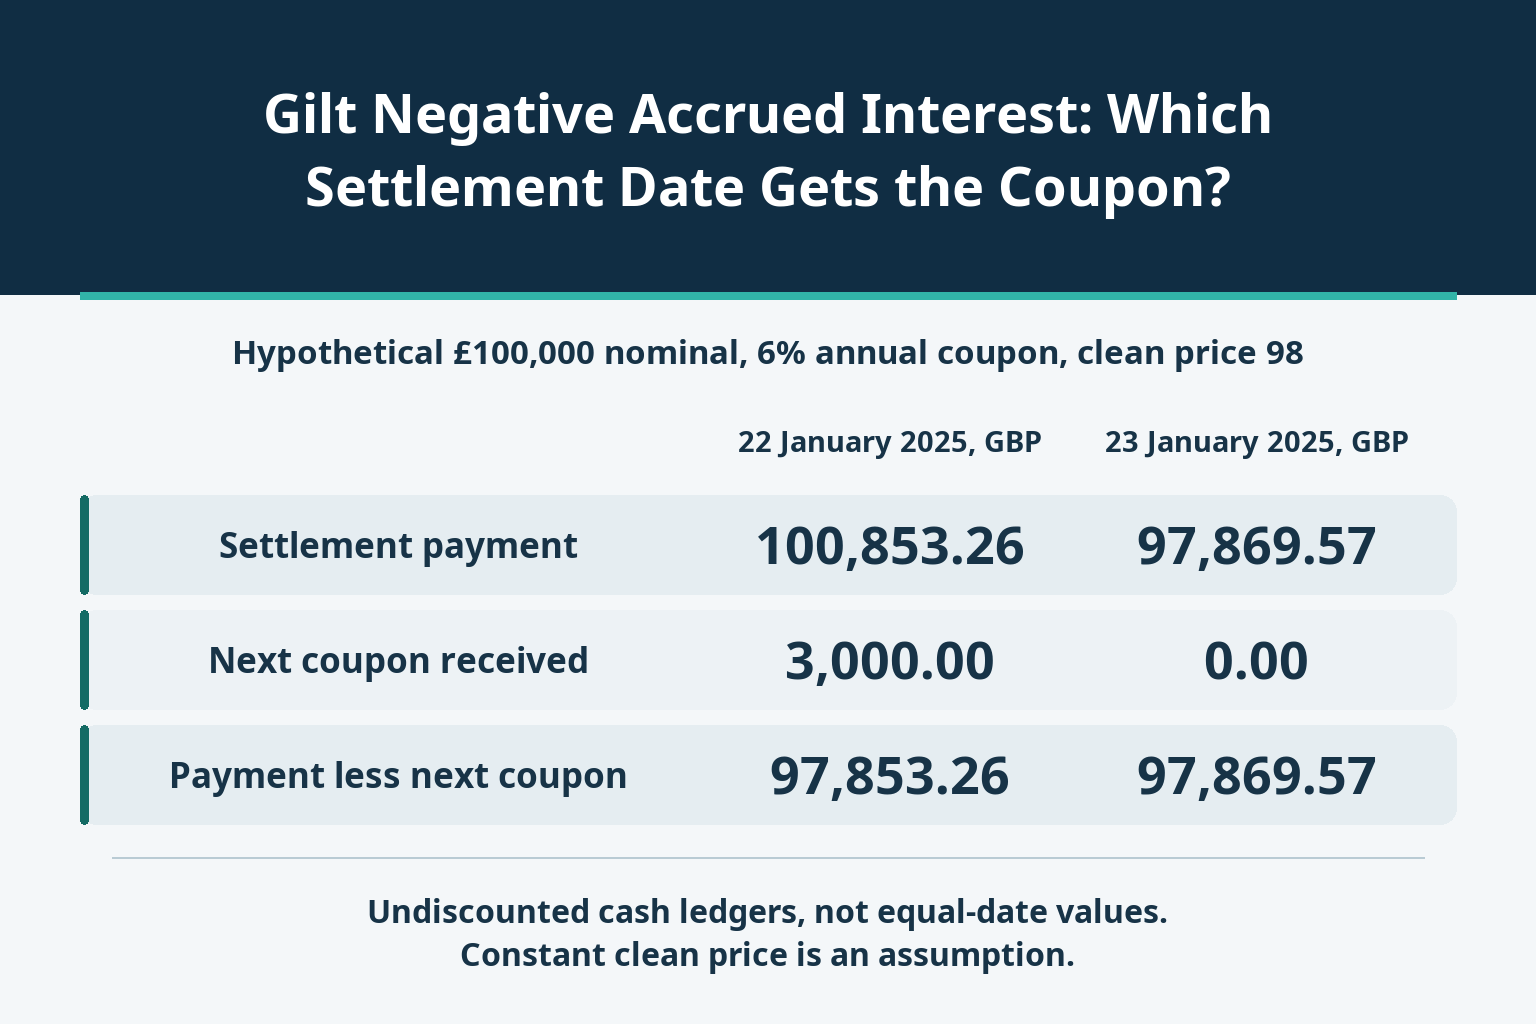
For this gilt convention, settlement on the record date still carries the next coupon; settlement after it does not. In the hypothetical ledger below, a purchase settling on 22 January 2025 costs £100,853.26 and carries a £3,000 coupon. Settlement on 23 January costs £97,869.57 but carries none of that payment. The £2,983.69 reduction in the invoice is not a free £2,983.69 gain.
The UK Debt Management Office describes the gilt ex-dividend date as the record date: entitlement is determined by the registered holding at that day’s close of business. Its published example gives 22 January 2025 as the record date for a payment due on 31 January 2025, seven business days later. This historical calendar is the basis of the example, not a forecast of a new bond’s payment schedule.
The wording matters. A trade settling on 22 January remains on the side that carries the forthcoming coupon. A trade settling on 23 January is in the ex-dividend period and does not carry it. Do not treat the label “ex-dividend date” as a shortcut for excluding every settlement on that date, or import an equity-trading convention without checking the gilt rule.
The relevant field is the agreed settlement date, not the date the order was entered or executed. The two purchases below assume normal completion and the relevant registered entitlement. A failed settlement or unresolved entitlement claim needs operational reconciliation; a calculator cannot prove what was delivered or credited to an account.
Invent a conventional fixed-rate sterling gilt with £100,000 nominal, a 6% annual coupon paid semi-annually and a clean price of 98 per £100 nominal. Its half-year coupon is £3,000, and the clean-price consideration is £98,000. The bond matures after the payment studied here. It has a standard coupon period, no inflation adjustment and no irregular first coupon. Fees, tax and funding are excluded.
Use the real interval from 31 July 2024 to 31 January 2025: 184 calendar days. There are 175 elapsed days at settlement on 22 January and 176 on 23 January. The invented 6% coupon is not the coupon on the DMO’s actual illustrative security. Likewise, 98 is a fixed teaching input, not an observed market price or an assumption that prices never move around a coupon boundary.
For this standard period, write the full-trade coupon as C, elapsed calendar days as t and period days as s. Accrued interest is C × t/s on or before the record date. After it, use C × (t/s − 1). The second branch deducts one whole coupon from the first; it does not merely change a day count by one.
On 22 January, accrued interest is £3,000 × 175/184 = £2,853.260869… . Rounded to pence on the traded nominal, this adds £2,853.26 to the clean consideration. The settlement payment is therefore £100,853.26. The buyer then carries the full £3,000 payment on 31 January, compensating the seller at settlement for the elapsed part of the coupon period.
On 23 January, the calculation is £3,000 × (176/184 − 1) = −£130.434782… . Equivalently, it is −£3,000 × 8/184, using the eight calendar days remaining. Rounded accrued interest is −£130.43, so the buyer pays £98,000 − £130.43 = £97,869.57 and receives no 31 January coupon. The rebate compensates for the remaining part of a period whose full coupon stays with the entitled holder.
The negative amount is normally netted into settlement. It is not necessarily a separate payment that can be counted again after the reduced invoice. This is a signed version of the bridge from a bond’s clean price to its settlement payment, not a second source of return.
In the DMO accrued-interest formula, the published coupon per £100 remains £3. It does not become zero just because this buyer receives none of the imminent coupon. Substituting zero would erase the rebate. Distinguish the security’s published coupon amount from the cash flow belonging to the buyer.
The following table subtracts only the forthcoming coupon from each purchase payment. It does not value the bond’s remaining life, deduct a future sale price or calculate investment profit. Both alternatives still hold the bond after this coupon date.
| Settlement date | Elapsed calendar days | Accrued interest, GBP | Settlement payment, GBP | Next coupon received, GBP | Undiscounted net outlay, GBP |
|---|---|---|---|---|---|
| January 22, 2025 | 175 | +2,853.26 | 100,853.26 | 3,000.00 | 97,853.26 |
| January 23, 2025 | 176 | −130.43 | 97,869.57 | 0.00 | 97,869.57 |
The 22 January ledger leaves £100,853.26 − £3,000 = £97,853.26. The 23 January ledger leaves £97,869.57 − £0 = £97,869.57. Their difference is £16.31. Comparing invoices alone hides the loss of the £3,000 entitlement; adding a £3,000 coupon to the second route would invent a payment the buyer does not receive.
There is a small but important rounding distinction. Before rounding either settlement, the difference is £3,000/184 = £16.304347826… . That exact difference rounds separately to £16.30. But the two actual penny-rounded ledger amounts shown above differ by £16.31. These are different rounding operations, not contradictory economics. Do not print £16.30 as the subtraction result of £97,869.57 and £97,853.26.
These are undiscounted ledgers with different payment dates, not equal-date values. The first buyer pays a day earlier and receives a coupon later; the second has another cash pattern. Funding, discounting, actual clean-price changes and costs would be needed to rank the alternatives economically. Constant clean price isolates the entitlement adjustment; it does not create a coupon-capture trade or predict a one-day return.
If a system incorrectly keeps the positive-accrual branch on 23 January, it calculates £3,000 × 176/184 = £2,869.565217… and demands £100,869.57. That is exactly £3,000 above the correct £97,869.57. A discrepancy of this size points to an entitlement or formula-branch problem, not an extra day of accrued interest.
A smaller error can arise from rounding at the wrong level. DMO guidance rounds accrued interest to the nearest penny on the traded nominal amount. It does not say to round the per-£100 accrual to two decimals first and then multiply by 1,000.
| Calculation error | Wrong payment, GBP | Correct payment, GBP | Overpayment or underpayment, GBP |
|---|---|---|---|
| 23 January: positive branch used | 100,869.57 | 97,869.57 | +3,000.00 |
| 22 January: per-100 amount rounded first | 100,850.00 | 100,853.26 | −3.26 |
| 23 January: per-100 amount rounded first | 97,870.00 | 97,869.57 | +0.43 |
For 22 January, prematurely rounding the per-£100 amount to £2.85 produces only £2,850 of total accrued interest and an invoice understated by £3.26. On 23 January, using −£0.13 per £100 produces −£130 and an invoice overstated by £0.43. Carry the fraction through the nominal scaling, then round the trade amount.
Neither test proves that every account discrepancy is an error: actual commissions or other separately identified charges can also change the debit. Reconcile those items explicitly. The table holds all such charges at zero so that the date branch and rounding defects can be identified without mixing them with a real fee.
The DMO glossary describes normal gilt-market settlement as T+1 while allowing other bilaterally negotiated dates. Thus an ordinary trade executed on 22 January would be due to settle on 23 January and would not carry this coupon. A trade that actually settles on 22 January is different. The apparent conflict disappears once trade date and settlement date are kept in separate columns.
Use the registrar’s published record date for the specific payment. Business-day counting around holidays, unusual settlement arrangements or a changed instruction should not be inferred from a generic weekday calculator. Our January dates match the DMO’s own historical example; that does not make them a reusable timetable for another gilt.
The final ex-dividend period before maturity is especially important: DMO guidance does not permit trades to settle in that period. This nonfinal coupon example cannot be extended to buying immediately before redemption. Inflation-linked gilts and irregular first coupons also need their own formulas. A negative accrued-interest convention is not a universal rule for every government bond market.
The useful result is not simply a negative number in the accrued-interest field. It is a settlement debit and a coupon entitlement that agree with each other, with the date boundary and penny rounding visible enough to audit.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


