


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev












Reconcile an FX forward’s mark-to-market with its actual unwind quote. A worked EUR/USD example separates discounting, bid–ask costs and the liability being hedged.
A forward can have a positive value even when spot equals the exchange rate written into the contract. It can also show a profit that the holder cannot collect immediately. The missing pieces are the remaining delivery date, the interest rates embedded in today’s replacement forward, and the terms on which the bank will actually close the position.
For a contract to buy euros, compare the agreed rate with a new forward for the same euro amount and delivery date, then discount the dollar difference. That produces a valuation benchmark. An executable unwind requires the correct bid or ask and any fees; a successful hedge must also be judged alongside the payment it protects.
Consider an existing contract to receive €1,000,000 and pay $1,100,000 in 90 days. Its locked rate K is 1.1000 dollars per euro. This is a hypothetical deliverable forward with a fixed maturity, not a rolling retail FX position or a futures contract. The original rate stays fixed while the market value changes.
Let S be today’s spot rate in dollars per euro, F today’s replacement forward rate to the original delivery date, and D the dollar discount factor for the remaining period. From the euro buyer’s perspective:
V = 1,000,000 × (F − 1.1000) × D
The result is dollars, not pips or a percentage return on margin. A contract to sell the same euros reverses the sign. Changing the quote to euros per dollar also changes which notional belongs in the formula; simply taking a reciprocal and retaining the same million-unit input can value a different trade.
Assume spot is 1.1200, the dollar rate is 5% and the euro rate 3%, all hypothetical annual simple rates for the same remaining 90 days. Use 90/360 = 0.25, comparable funding and collateral terms, and initially ignore basis, spreads, credit adjustments and fees.
D_USD = 1 / (1 + 0.05 × 0.25)
D_EUR = 1 / (1 + 0.03 × 0.25)
F = 1.1200 × D_EUR / D_USD = 1.12555831
The forward’s value is $25,242.78 using unrounded inputs. An independent check values the two promised payments separately: the present dollar value of receiving the euros is $1,111,662.53; that of paying the dollars is $1,086,419.75. Their difference gives the same answer. The shortcut 1,000,000 × (1.1200 − 1.1000) gives $20,000, but compares today’s spot exchange with a future delivery obligation.
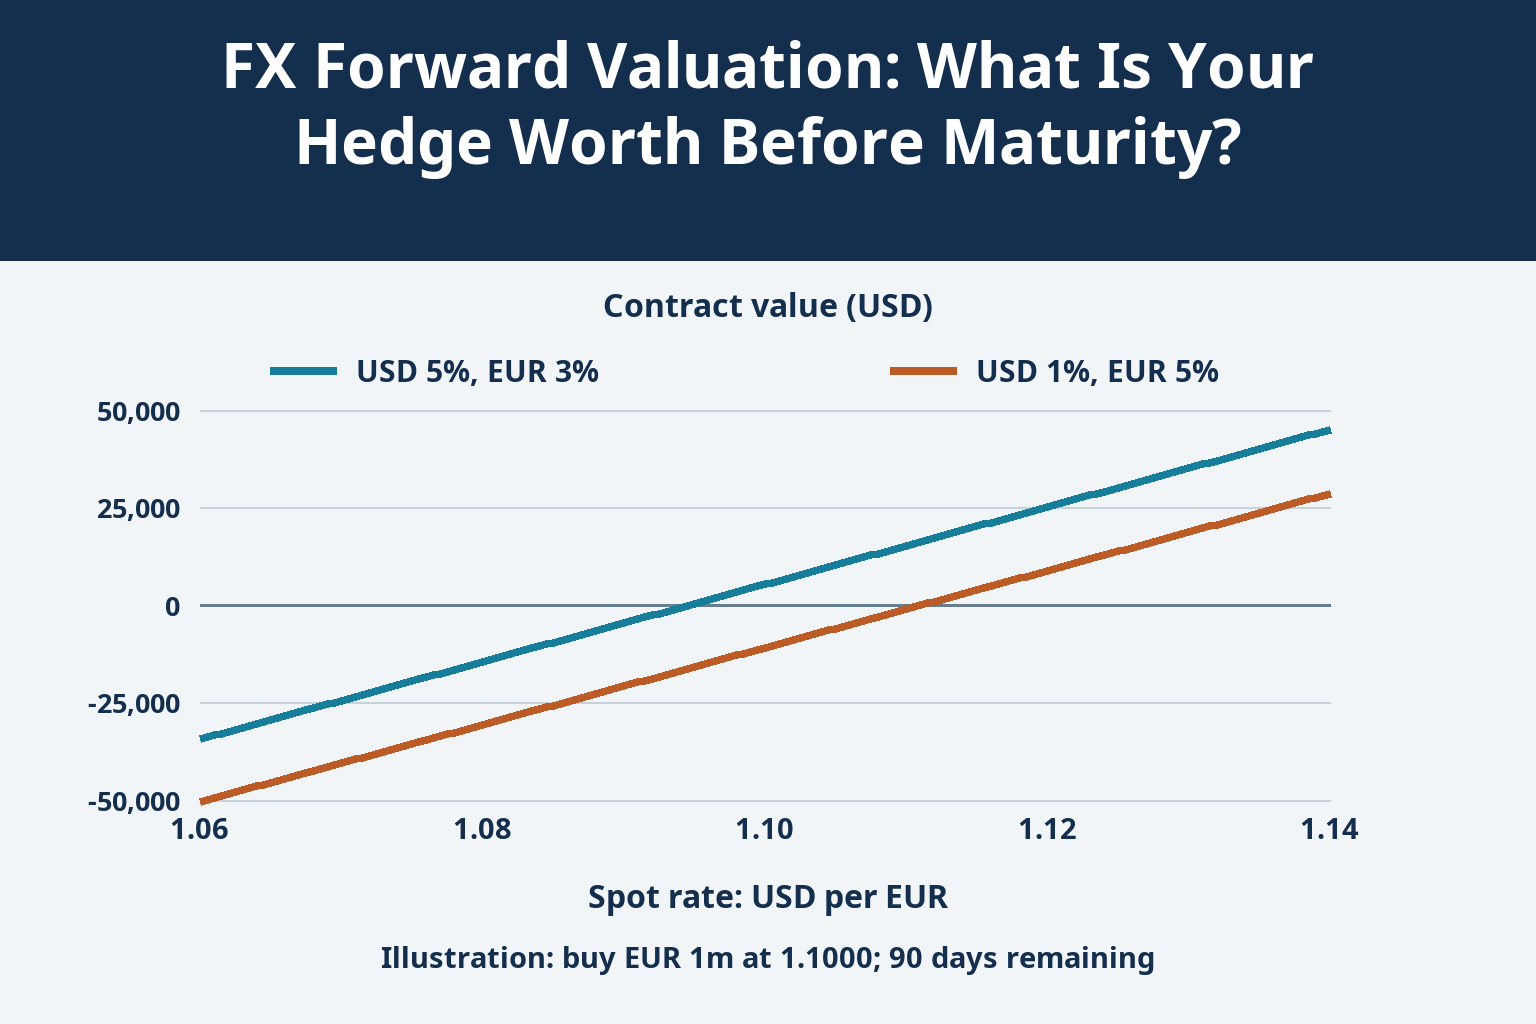
The table changes the inputs at one valuation date; it is not a historical price series. Each row keeps the original contract and 90-day remaining term unchanged.
| Spot USD/EUR | USD rate | EUR rate | New forward USD/EUR | Value USD |
|---|---|---|---|---|
| 1.1200 | 5% | 3% | 1.12555831 | 25242.78 |
| 1.1000 | 5% | 3% | 1.10545906 | 5391.66 |
| 1.1000 | 1% | 5% | 1.08913580 | -10837.10 |
| 1.0800 | 5% | 3% | 1.08535980 | -14459.46 |
With spot still at 1.1000, the contract is worth +$5,391.66 under the 5%/3% rates, but −$10,837.10 under 1%/5%. A spot chart alone cannot settle the question. At expiry, discount factors become one and forward converges to the relevant settlement spot; only then does the simple spot-minus-contract-rate payoff apply to this model.
Now obtain a hypothetical executable two-way quote of 1.1250 bid and 1.1260 ask for precisely the remaining maturity and €1 million. The existing position buys euros, so its offset sells euros at the dealer’s bid. The original contract receives euros while the offset delivers them; at maturity their dollar cash flows leave $25,000 net receivable.
If the bank agrees to terminate both obligations for cash today using the assumed 5% dollar discount rate, that future amount is worth $24,691.36. A separate $150 fee payable today leaves $24,541.36. That differs from the model midpoint valuation without implying an accounting error.
Using the ask would overstate the maturity receipt by $1,000. Discounting for an original 180-day term instead of the remaining 90 days would also be wrong. A fee due at maturity must be discounted with the cash flow rather than treated as an identical fee payable now. Ask for the actual settlement amount, date and currency, not just an attractive replacement rate.
Suppose the original purpose was to hedge a €1 million invoice due on exactly the same date. In the frictionless example, the euro liability’s current dollar value is $1,111,662.53. Deducting the forward asset of $25,242.78 leaves a net payment value of $1,086,419.75—the present value of the locked $1.1 million payment.
At maturity, paying $1.1 million under the forward produces the euros needed for the invoice. Celebrating the derivative gain while ignoring the higher dollar value of the invoice counts only the pleasant half of the hedge. This economic reconciliation does not determine how a company must present hedge accounting or tax.
If the invoice is cancelled, reduced or postponed, the forward does not automatically change with it. Closing a derivative while retaining the invoice restores currency exposure; retaining the derivative after cancellation creates unmatched exposure. Moving a payment 30 days later requires a new date-matching assessment, not merely a relabelling of the old deal.
The two-rate formula is a deliberately simple replication benchmark. Actual market forwards can embed cross-currency basis, credit limits, collateral terms and liquidity costs. Where a reliable executable same-date forward is available, first compare against that quote; do not replace a market curve with two policy rates and call every difference a mispricing. The distinction between forward points and the final exchange rate matters when reconstructing the quote.
A second trade with a different counterparty may offset exchange-rate exposure economically without cancelling either legal obligation. Net settlement, early termination and collateral return require the applicable agreement and confirmations. Collateral already posted must be reconciled separately rather than added to valuation profit a second time. Non-deliverable forwards have fixing and settlement conventions that need their own cash-flow calculation.
The useful answer is therefore three numbers, not one: a model value, an executable close-out amount, and the combined value of the hedge plus its underlying exposure. Confusing them is how a correct exchange-rate calculation turns into the wrong cash decision.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


