


- XAUUSD
- XAGUSD
- WTI
- USDX



Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev









Lease liabilities and lease cash must be treated consistently with the earnings denominator. A worked example separates four possible multiples, explains why two coherent approaches can reverse a stock screen, and reconciles EBITDA with cash without mislabelling the result as free cash flow.
A stock screen shows a company at five times EBITDA. Another calculation produces 6.5 times, while an adjustment for cash rent produces about 7.14 times. Before deciding which number looks attractive, establish whether the enterprise value and the earnings measure describe the same treatment of leases.
A lower multiple can come from leaving a lease obligation out of the numerator while also leaving its cash cost out of the denominator. Fixing that mismatch is necessary, but it does not make every consistently defined approach deliver the same answer. In the hypothetical example below, company A falls below a lease-free peer on one coherent measure and above it on another. The result changes a screen's ordering; it does not establish which shares are undervalued.
The IFRS Foundation describes IFRS 16 as a lessee model that recognizes a right-of-use asset and a lease liability, with relevant short-term and low-value exemptions. It has applied to annual reporting periods beginning on or after January 1, 2019. That description establishes an accounting framework, not a mandatory enterprise-value formula.
The Foundation's January 2016 effects analysis explained that replacing former operating lease expense with depreciation and interest could raise EBITDA without changing total lease cash. This is historical implementation analysis, not a newly announced rule. Its comparison also distinguishes IFRS treatment from US operating-lease accounting: do not assume every company reporting under a different framework has removed the same lease expense from EBITDA.
The operational question is therefore narrower than “does the company apply IFRS 16?” Obtain the actual EBITDA reconciliation. Determine which lease charges remain in operating expenses, which depreciation and interest have been excluded, and whether management has already made an additional rent adjustment. A label such as “adjusted EBITDA” is not enough to identify the denominator. In particular, deducting a cost that is already included would not improve comparability.
All monetary amounts in this example are millions of one unspecified currency. The companies and figures are invented. Company A has equity market value of 600, nonlease interest-bearing debt of 500 and eligible cash of 100. Its enterprise value excluding leases is E = 600 + 500 − 100 = 1,000. Assume all the stated cash is eligible and there are no preferred shares, noncontrolling interests, pension claims, separate investments or other adjustments.
A also has recognized lease liabilities L = 300. A lease-inclusive numerator is consequently E + L = 1,300. The bridge between market capitalization and enterprise value must use the same scope throughout. If a data provider's debt figure already includes those lease liabilities, adding another 300 would duplicate the claim.
Do not add the right-of-use asset as a second liability adjustment. Nor is the undiscounted sum of all future rent interchangeable with the recognized liability used here. This model deliberately takes L as a stated balance rather than attempting to estimate lease fair value. In a real company, first document whether an input is a reported carrying amount or an analyst's valuation adjustment, and keep that choice consistent across peers.
Let B = 200 be reconciled EBITDA, with depreciation and interest on the modeled capitalized fixed leases excluded. Let R = 60 be normalized annual lease cash for exactly that same population. The analytical after-cash-rent proxy is B − R = 140. This is a defined analytical measure, not reported EBITDA, a reconstruction of former IAS 17 profit or a prescribed accounting subtotal.
Timing matters to that distinction. Rent-free periods, prepayments and other payment patterns can make cash rent differ from the expense associated with the same year. R must also exclude variable or short-term lease costs that have already reduced B. The example holds the population homogeneous so that the numerator and denominator can be followed without silently changing the contracts being compared.
| Comparison lens | EV, millions | Denominator, millions | Multiple, times |
|---|---|---|---|
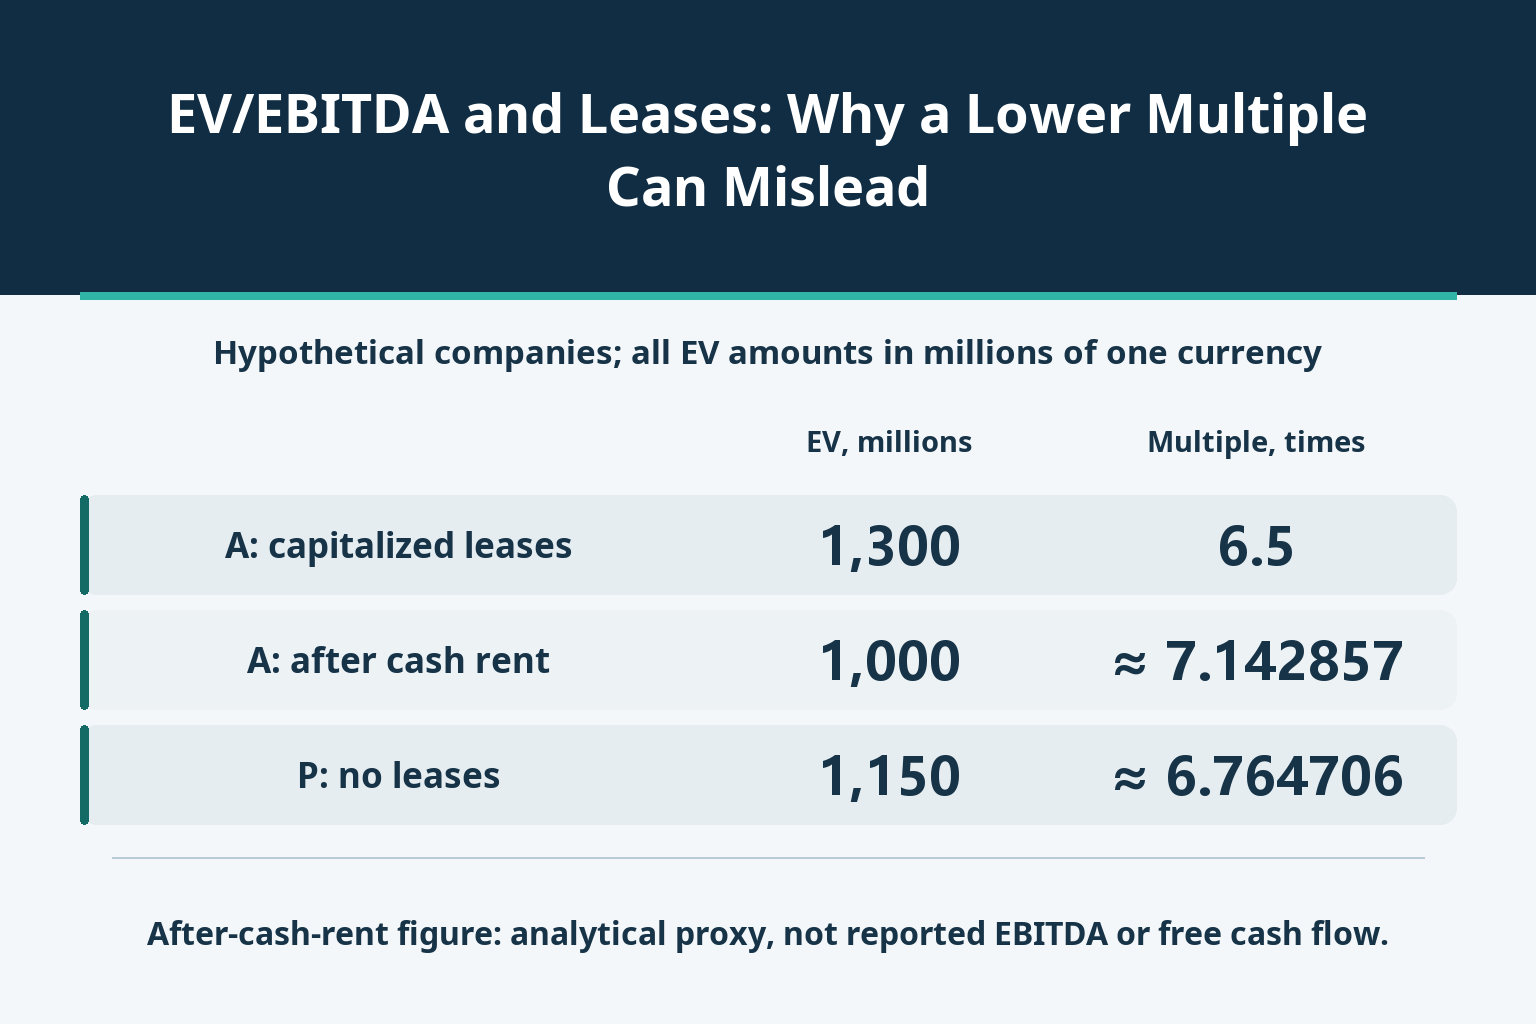
| Capitalized lease view | 1,300 | 200 | 6.5 |
| After-cash-rent proxy | 1,000 | 140 | ≈ 7.142857 |
| Mismatch: omit liability and rent deduction | 1,000 | 200 | 5 |
| Mismatch: liability plus rent deduction | 1,300 | 140 | ≈ 9.285714 |
The capitalized view places the lease liability in EV and uses the corresponding pre-lease-cash EBITDA: 1,300 / 200 = 6.5 times. The alternative removes the liability from EV and deducts the specified cash rent from the operating measure: 1,000 / 140 = 50/7, or approximately 7.142857 times. The second measure must be labelled EV divided by an after-cash-rent proxy, not passed off as the same reported EV/EBITDA ratio.
By contrast, 1,000 / 200 = 5 omits the lease claim without imposing the corresponding rent deduction. At the other extreme, 1,300 / 140 = 65/7, approximately 9.285714, combines the lease-inclusive numerator with the rent-reduced denominator. These are mismatches within the two comparison frameworks defined here. That is not a universal prohibition on every differently constructed valuation ratio; another framework needs its own explicit economic justification.
With E > 0, L ≥ 0 and B > R ≥ 0, the two coherent ratios are equal only when E / (B − R) = (E + L) / B. Rearranging gives L = ER / (B − R). With E = 1,000, B = 200 and R = 60, the equality balance is 3,000/7, approximately 428.571429, not the assumed lease liability of 300.
Alternatively, keep E, B and L fixed and solve for rent: R = BL / (E + L). The boundary is 600/13, approximately 46.153846. Rent below that exact value makes the cash-proxy multiple lower than 6.5; rent above it makes the multiple higher, provided the denominator stays positive. As an independent control, R = 40 gives 1,000 / 160 = 6.25. The baseline R = 60 instead produces about 7.14.
These are algebraic equality conditions, not a method for measuring a lease liability or setting its fair value. L is a balance at a date; R is an annual flow. Remaining contract length, payment timing and the composition of the lease portfolio can change their relationship. Six displayed decimals explain the calculation rather than claim that an analyst knows normalized rent with such precision. A zero or negative denominator cannot be ranked as an ordinary positive multiple.
Now introduce lease-free peer P, with EV of 1,150 and EBITDA of 170. Its multiple is 115/17, approximately 6.764706. As P has no leases in this controlled example, it has no corresponding adjustment between the two lenses.
| Consistently defined lens | Company A, times | Lease-free peer P, times |
|---|---|---|
| Capitalized lease view | 6.5 | ≈ 6.764706 |
| After-cash-rent proxy | ≈ 7.142857 | ≈ 6.764706 |
A's capitalized multiple of 6.5 is below P's approximately 6.76. A's after-cash-rent measure of approximately 7.14 is above it. No share price, operating forecast or contractual payment changed between those comparisons; the analytical basis changed. A filter that reports only the lower number conceals information that can matter to its selection process.
Neither ordering proves relative value. The model has not established equivalent growth, asset ages, maintenance capital expenditure, residual ownership rights or business risk. A company owning its premises may face a different renewal investment from one renting them. Present both reconciled views, explain which question each is intended to answer, and examine those economic differences before assigning a valuation conclusion. Choosing a definition merely because it places a preferred company first is not analysis.
Assume the annual lease cash of 60 consists of principal of 45 and interest of 15. Also assume right-of-use depreciation of 50. Starting from the defined EBITDA of 200, the partial cash bridge is 200 − 45 − 15 = 140. The payment split does not make the interest disappear. Subtracting only principal produces 155 and leaves 15 of lease cash unaccounted for.
Nor is 200 − 50 − 60 = 90 the correct bridge from EBITDA to cash after these leases. EBITDA already excludes the noncash depreciation charge; deducting it as well as the full cash payment mixes an expense bridge with a cash bridge. If the starting point is EBIT instead, the relevant depreciation must first be added back before substituting lease cash. Different starting subtotals require different adjustments.
The resulting 140 is still not free cash flow. Nonlease financing interest, taxes, working-capital movements, capital expenditure and other relevant cash adjustments have not been deducted. Cash-flow presentation can also place components in different sections; reconcile total payments rather than interpreting a classification shift as new cash generation. Finally, a payment of principal of 45 alone does not prove the lease liability fell by 45: new leases and other changes have deliberately not been supplied.
The useful output is not a single “correct” low number. It is a traceable set of claims, operating measures and cash payments that lets a reader see why the ratio changes. Only after that reconciliation does the multiple become a defensible starting point for valuation.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG





The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


