


- WTI
- XAUUSD
- XAGUSD
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev







A deferred futures contract can receive a daily settlement reference without an outright trade in the settlement window. A worked crude-oil example reconstructs calendar-spread weights, distinguishes an implied range from a unique price, and tests what a ten-contract exit would actually achieve.
A deferred crude-oil futures contract can have no outright trade during the settlement window and still receive a new daily settlement price. The missing print does not mean the exchange has no pricing evidence: calendar spreads link that contract to other delivery months. Reconstructing those links explains the reference, but it does not establish that a trader can close a position at that price.
The example uses the normal daily settlement procedure for NYMEX Light Sweet Crude Oil futures, CL. It is not a universal algorithm for all futures, and the expiring contract's final settlement has separate procedures. M1, M2 and M3 are consecutive delivery months; M1 is the designated active month, away from expiry and active-month-switch exceptions. All prices and volumes below are hypothetical.
For this procedure, the active-month and calendar-spread settlement window is 14:28–14:30 Eastern Time. Suppose M1 trades 20 contracts at USD 69.98 per barrel, 60 at 70.00 and finally 20 at 70.02. Its volume-weighted average is 70.00. The last print is 70.02. Neither number is an error: they answer different measurement questions.
Now give the M1−M2 calendar spread a window VWAP of −0.30. Throughout this article a spread means the nearer month minus the deferred month. M2's reference is therefore 70.00−(−0.30)=70.30. This established monthly reference can anchor the next calculation. A stale M3 outright print alone could not reconstruct those changes in related months.
Assume M3 has no outright trade in this window, but two relevant calendar-spread routes do trade. That is not the same as saying M3 has no transactions or zero reported volume: spread legs can contribute to activity in the underlying month. In this model there are no other effective sources to include.
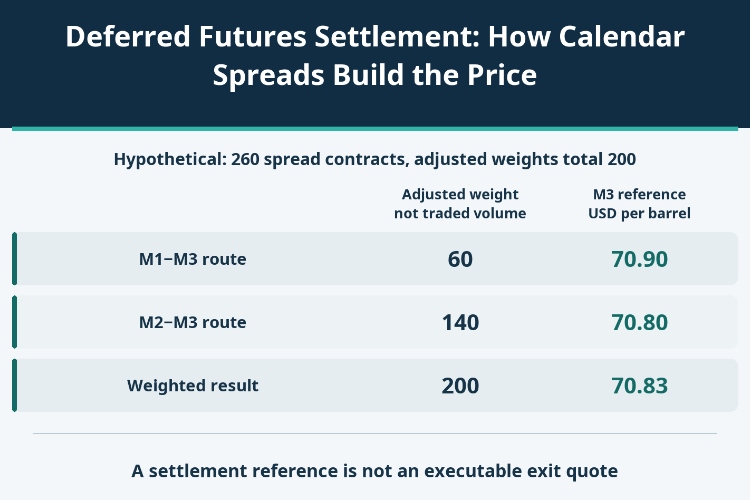
The CL procedure weights each spread's volume by dividing it by the number of calendar months separating its legs. The target month is the deferred leg, and the known earlier settlements supply the anchors. Prices and spread values in the table are dollars per barrel; the traded quantities are spread contracts.
| Spread route | Known anchor (USD per barrel) | Spread VWAP (USD per barrel) | Contracts traded | Months apart | Adjusted weight | Implied M3 price (USD per barrel) |
|---|---|---|---|---|---|---|
| M1−M3 | 70.00 | −0.90 | 120 | 2 | 60 | 70.90 |
| M2−M3 | 70.30 | −0.50 | 140 | 1 | 140 | 70.80 |
The M1−M3 route implies 70.00−(−0.90)=70.90. The M2−M3 route implies 70.30−(−0.50)=70.80. A negative nearer-minus-deferred spread puts the deferred price above the anchor; reversing that sign would price the wrong relationship.
The two-month route contributes 120/2=60 of adjusted weight. The one-month route contributes 140/1=140. Combining the candidate prices gives:
(70.90×60 + 70.80×140)/(60+140) = 70.83.
There are 260 actual spread contracts in the two routes, but the sum of adjusted weights is 200. The latter is an input to the averaging rule, not a replacement figure for reported trading volume. Dividing a route's weight by its two-month distance does not halve the number of contracts actually traded.
If the candidate prices were weighted directly by 120 and 140, the result would be 70.846153846… rather than 70.83. Rounded to cents for this comparison, that is 70.85: a two-tick difference. CL's ordinary price increment is USD 0.01 per barrel, and a contract covers 1,000 US barrels, making one tick USD 10 per contract.
The proper result already lies on the tick grid. The incorrect comparison is not a half-tick tie either, so this example does not establish how every rounding boundary should be handled. It shows why matching the exchange's weighting rule matters before debating the last decimal. Nor does the weighting prove that one route was manipulated or that the next oil-price move has a particular direction.
Consider a separate scenario in which there are no relevant calendar-spread trades. Do not add these quotes to the traded-volume inputs above. Known monthly settlements and spread bids and offers can instead define reference-implied boundaries. If A is the anchor, b the spread bid and a the spread ask, then:
Implied deferred interval = [A−a, A−b].
Subtracting the spread reverses the sides. With the same hypothetical anchors, the following quotes produce two intervals.
| Spread route | Known anchor (USD per barrel) | Spread bid (USD per barrel) | Spread ask (USD per barrel) | Implied bid boundary (USD per barrel) | Implied ask boundary (USD per barrel) |
|---|---|---|---|---|---|
| M1−M3 | 70.00 | −0.92 | −0.86 | 70.86 | 70.92 |
| M2−M3 | 70.30 | −0.61 | −0.55 | 70.85 | 70.91 |
The highest implied bid boundary is 70.86, and the lowest implied ask boundary is 70.91. Six one-cent grid points fall within that range, from 70.86 through 70.91. These inputs do not identify a unique official settlement.
The relevant CL procedure calls for settlement within an implied range when the Global Command Center's reasonability conditions are met; it does not prescribe a midpoint for every case. Those conditions have not been verified in this hypothetical scenario. Counting six grid points is not evidence that every one has been approved. If a suitable implied range is unavailable, the hierarchy includes a fallback using the preceding delivery month's daily net change from its prior trading-day settlement. It is not a previous calendar month's return, or permission to invent a threshold or an arbitrary quote.
The anchor in that calculation is an established settlement reference, not a live bid or offer on which another order can necessarily execute. Treating it as a tradeable near-month price would silently replace one type of evidence with another.
To evaluate an actual synthetic execution, the trader would need the correct-side near-month quote, synchronized spread quotes, sufficient quantity on each leg and a feasible execution method. Those conditions are absent from the interval example. It cannot establish a risk-free arbitrage or the ability to acquire the target month at the calculated lower boundary.
This distinction also helps diagnose missing data. A published reference can be consistent with the settlement hierarchy even if an observer cannot reproduce it from a screen showing only M3. The appropriate response is to obtain the relevant spread window and anchors, not to assume that a missing outright print proves a faulty settlement.
Return to model A's 70.83 reference, then move to an independently assumed later order book. M3 bids are 70.76 for eight contracts and 70.74 for two; the best offer is 70.88. Suppose a sale closing ten long contracts fills those bids exactly, without fees, cancellations, queue delay, price changes or alternative routes.
The average sale is (70.76×8+70.74×2)/10=70.756. An average can sit between legal single-order ticks; this does not posit a 70.756 order. Relative to selling at 70.83, the execution reduces P&L by USD 740: (70.83−70.756)×1,000×10. Applying the top bid to all ten contracts would show only USD 700, missing USD 40 from depth.
This is a hypothetical shortfall against a reference, not an absolute account loss without a cost basis. Because the reference and book are from different times, the entire USD 740 is not a simultaneous bid–ask cost or a pure slippage estimate. Nor is the sale price multiplied by barrels and contracts the cash proceeds of closing a futures position. The daily futures settlement ledger and closing cash flows address that separate accounting question.
Although 70.83 lies between the best bid and offer, no displayed buyer has agreed to take ten contracts there. Eligible Trading at Settlement, or TAS, orders are a separate mechanism: an executed order can establish a price at the daily settlement determined later, plus or minus a specified differential. That does not make every month eligible, guarantee a zero-differential fill or turn a published reference into a retroactive ordinary-market execution.
The useful chain is evidence, reference, then execution. A calculation can explain the reference precisely while leaving the trading question open; the order book and the order actually filled must answer that last question.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


