


- XAUUSD
- XAGUSD
- WTI
- USDX


Markets
Analysis
User
24/7
Economic Calendar
Education
Data
- Names
- Latest
- Prev












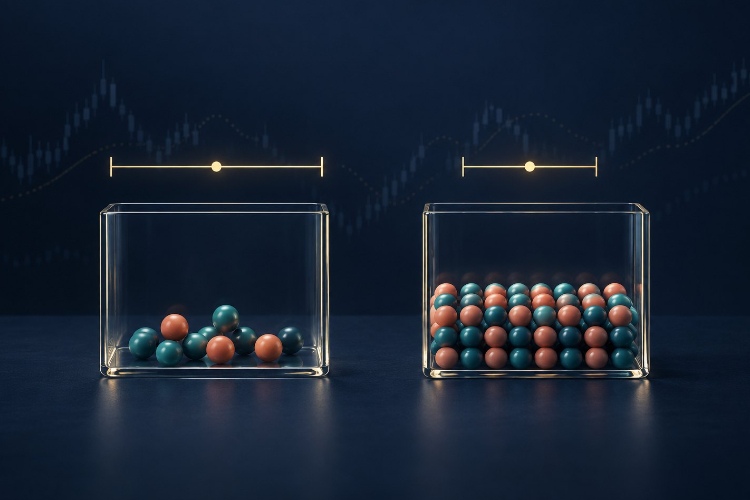
Twelve wins in 20 trades and 120 wins in 200 both produce a 60% win rate, but very different evidence. Recalculate the uncertainty, then test whether costs and the sampling design overturn the conclusion.
Twelve winning trades out of twenty is a 60% win rate. It is not yet convincing evidence that the strategy has a stable 60% probability of winning. Under a simple independent-trade model, a two-sided 95% Wilson interval runs from about 38.66% to 78.12%. It does not even rule out a win probability below one half. The useful question is not whether 60% sounds high, but whether the evidence remains persuasive after sampling uncertainty, trading costs and the way the results were selected.
Start with one complete economic position, from entry to exit, and a rule for classifying its result. Several fills or partial exits from the same position do not automatically become independent trials. State whether a win means a positive result before or after costs. Decide how a zero-return trade is treated; quietly dropping flat trades changes the question being estimated.
For the calculations below, each hypothetical trade has exactly two possible outcomes, all observations are independent and the underlying win probability is constant. These are modelling assumptions, not characteristics that a spreadsheet can certify. The interval describes uncertainty about that probability. It does not describe the range of returns on the next trade.
Let k be the number of wins, n the number of trades and q=k/n. For a two-sided 95% Wilson interval, use z=1.96. Calculate the centre m and half-width h, then report m−h and m+h:
m = (q + z²/(2n)) / (1 + z²/n)
h = z × √[q(1−q)/n + z²/(4n²)] / (1 + z²/n)
| Wins / trades | Observed win rate | 95% Wilson interval |
|---|---|---|
| 12 / 20 | 60% | 38.66%–78.12% |
| 120 / 200 | 60% | 53.08%–66.54% |
Use the unrounded values in the formula and round only the result. With 200 observations, the estimate has not risen: its sampling uncertainty has narrowed. Wilson is a nominal 95% procedure, not a promise of exactly 95% coverage for every finite sample. Its frequentist meaning concerns coverage across repeated samples generated under the model. It does not assign a 95% posterior probability to the particular interval already calculated.
Consider a deliberately restricted payoff model. Each winner earns +1R before costs, each loser loses −1R, and every completed trade costs a fixed 0.05R. R is a fixed risk unit here, not a percentage of account equity. If p is the unknown win probability, expected net profit per trade is 2p−1−0.05 in R units. The break-even win rate is therefore 52.5%, not 50%.
At the observed 60%, estimated expectancy is +0.15R per trade. Substituting the unrounded Wilson endpoints gives an interval of approximately −0.277R to +0.512R for the 20-trade model mean. With 200 trades, it becomes about +0.012R to +0.281R. Only the second lower endpoint is above zero, and then only under these fixed-payoff, fixed-cost assumptions.
Now raise the cost to 0.08R without changing the win count. Break-even moves to 54%. The 200-trade lower win-rate limit, 53.08%, no longer clears it; the corresponding lower mean is about −0.018R. A seemingly small execution-cost change reverses that narrow conclusion. Neither calculation guarantees a profitable next month or bounds the possible drawdown.
Real trades rarely all win or lose exactly 1R. If payoff sizes, gaps and costs vary, a confidence interval for the win probability alone is not an interval for expectancy. Analyse the distribution of net trade outcomes and the uncertainty in payoff sizes as well. A high win rate can coexist with rare, oversized losses.
Five positions opened around one central-bank announcement may share the same underlying bet. Splitting a position into ten tickets does not create ten fresh pieces of evidence. The issue resembles concentration in common risk factors despite holding several positions: counting instruments is not the same as identifying independent exposures.
Dependence can make the simple binomial interval too optimistic. Keep event dates, strategy identifiers and overlapping exposure in the trade log. A more appropriate analysis may need event-level grouping or a resampling method that preserves time dependence. Do not repair the problem by arbitrarily halving the trade count. Nor does a large old sample establish that the same probability persists after a market regime, execution venue or strategy rule changes.
There is no universal minimum. For planning the precision of a proportion estimate, a rough normal approximation is n ≈ z²p(1−p)/e², where e is the desired absolute half-width. Taking p=0.5 conservatively, z=1.96 and e=0.05 gives 384.16, rounded up to 385 observations. Five percentage points means 0.05, not 5.
This is a planning approximation, not an exact Wilson sample-size solution, a power calculation for profitability or permission to trade once the counter reaches 385. It assumes the sampling conditions hold. A precise estimate from a biased selection remains biased.
Freeze the entry, exit, cost and win-classification rules before the evaluation sample begins. Specify when the evaluation will take place. Checking after every trade and stopping at the first favourable interval changes the sampling procedure; an ordinary fixed-sample interval no longer justifies the original confidence claim.
Keep the number of strategy variants tested and separate development data from an untouched chronological validation period. Choosing the best-looking result from many variants, then presenting its ordinary interval as if it were the only test, hides selection risk. Record the trade count, win count, interval method, cost model, dependence checks and market period together. If the lower limit fails the relevant threshold, the result is insufficient evidence under that test—not proof that the strategy must lose. If it passes, it is one conditional piece of evidence, not a substitute for execution and payoff analysis.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


The risk of loss in trading financial instruments such as stocks, FX, commodities, futures, bonds, ETFs and crypto can be substantial. You may sustain a total loss of the funds that you deposit with your broker. Therefore, you should carefully consider whether such trading is suitable for you in light of your circumstances and financial resources.
No decision to invest should be made without thoroughly conducting due diligence by yourself or consulting with your financial advisors. Our web content might not suit you since we don't know your financial conditions and investment needs. Our financial information might have latency or contain inaccuracy, so you should be fully responsible for any of your trading and investment decisions. The company will not be responsible for your capital loss.
Without getting permission from the website, you are not allowed to copy the website's graphics, texts, or trademarks. Intellectual property rights in the content or data incorporated into this website belong to its providers and exchange merchants.
Not Logged In
Log in to access more features


Log In
Sign Up


