


- GBPUSD
- XAUUSD
- XAGUSD
- WTI
- USDX


行情
分析
用户
快讯
财经日历
学习
数据
- 名称
- 最新值
- 前值







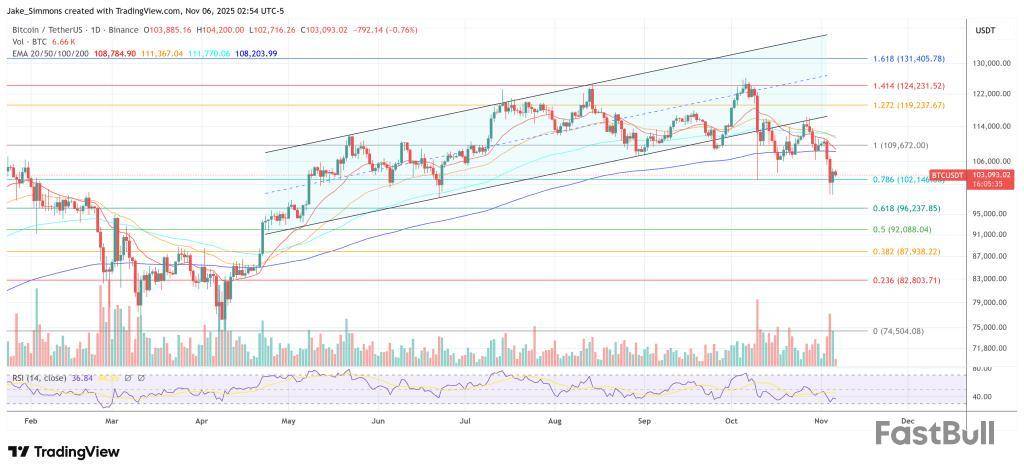
Galaxy Digital has cut its 2025 year-end Bitcoin target to $120,000 from $185,000 in a new research alert circulated on November 5 and shared via screenshots on X by Alex Thorn, the firm’s head of firmwide research. In the note titled “Bitcoin Outlook Update: Lowering 2025 YE Target to $120,000,” Thorn situates the downgrade squarely in the context of a “major, multi-week selloff,” writing that “Bitcoin is trading below $100k for the first time since late June, with other cryptos faring worse.”
Thorn stresses that the shift is cyclical rather than existential, stating plainly: “While bitcoin’s structural investment case remains strong, cyclical dynamics have evolved.” The firm frames the current backdrop as a decisive turn in market microstructure: “Bitcoin has entered a new phase – what we call the ‘maturity era’ – in which institutional absorption, passive flows, and lower volatility dominate.”
That regime change helps explain both the tempered year-end target and the altered cadence of price discovery that Galaxy now expects. As Thorn puts it, “If bitcoin can maintain the ~$100k level, we believe the almost three-year bull market will remain structurally intact, though the pace of future gains may be slower.” Short-term optimism is not abandoned: “Still, we think nearing prior all-time highs before year-end is a reasonable target for short-term bulls.”
Reasons For The Bitcoin Downgrade
The downgrade aggregates several identifiable drags, beginning with distribution patterns across the holder base and the market’s capacity to absorb them. Galaxy writes: “Significant coin transfers from old holders to ETFs and new institutional buyers signal maturity, not weakness, but have presented headwinds.” This redistribution—whales handing supply to passive and institutional channels—may strengthen long-term ownership but has, in Galaxy’s telling, blunted near-term momentum.
Positioning and leverage are the second leg of the argument. Thorn flags the “significant leverage wipeout from Oct. 10” and adds that it “continues to dent market liquidity and confidence.” The October flush sits at the center of Galaxy’s cyclical reassessment: forced de-risking weakened order-book depth just as large-holder distribution accelerated, leaving price vulnerable into the latest drawdown.
A third component is the rotation of capital and narrative attention into other trades. Galaxy is explicit that “Bitcoin started the year as the hottest investment narrative, but AI, hyperscalers, gold, and the Magnificent 7 have absorbed capital and attention that might otherwise flow into BTC.”
That diversion extends into crypto-adjacent plumbing as well: “Rapid stablecoin growth has redirected venture and equity interest into fintech and payments infrastructure.” The net effect, according to the note, has been a drag on incremental demand for direct BTC exposure and a tougher funding environment for pure-play Bitcoin vehicles.
Retail participation, which defined prior peaks, is notably absent at sustained scale, and when it surfaces it tends to be flighty. Thorn writes: “Retail never fully returned at scale post-2021; when it did, the memecoin mania fostered short-termism that is not conducive to understanding and adopting bitcoin’s long-term value proposition.” Without sustained retail sponsorship, Galaxy expects ETF and institutional flows to “define BTCUSD behavior,” adding that “Passive Flows Dominate… lowering volatility and moderating cycles.” This, again, is part of the “maturity era” thesis rather than a repudiation of Bitcoin’s core investment case.
Policy timing features as a missing catalyst rather than a negative shock. The note observes that “Despite positive rhetoric, no government bitcoin purchases have been announced. In general, the US government has been very quiet on the Strategic Bitcoin Reserve (SBR).” Galaxy does not ascribe immediate downside to the absence, but it removes a bullish tail event that some investors had hoped would materialize this year.
Corporate treasuries and listed “Bitcoin-as-reserve” plays also receive a recalibration. Galaxy argues that the next iteration will demand business fundamentals rather than balance-sheet optics alone: “BTCTC Phase 2: The next wave of bitcoin treasury companies will mostly need revenue generation and operating businesses beyond reserve accumulation to differentiate themselves and thrive.” The firm also points to “poor performance of BTC treasury companies” as part of the year’s defining headwinds.
Taken together, the factors map to a post-$100k market defined less by reflexive retail surges and more by methodical institutional accumulation. Galaxy calls it the “Post-$100k Regime,” in which “Bitcoin’s ascendance above six figures earlier this year marked the transition from early-era speculation to mature, institutionalized markets.”
The conclusion threads the needle between structural conviction and cyclical prudence: “As a result of this market performance, and other factors, we are revising our 2025 year-end bullish bitcoin target from $185,000 to $120,000.”
At press time, BTC traded at $103,093.

728 RM B 7/F GEE LOK IND BLDG NO 34 HUNG TO RD KWUN TONG KLN HONG KONG


交易股票、货币、商品、期货、债券、基金等金融工具或加密货币属高风险行为,这些风险包括损失您的部分或全部投资金额,所以交易并非适合所有投资者。
做出任何财务决定时,应该进行自己的尽职调查,运用自己的判断力,并咨询合格的顾问。本网站的内容并非直接针对您,我们也未考虑您的财务状况或需求。本网站所含信息不一定是实时提供的,也不一定是准确的。本站提供的价格可能由做市商而非交易所提供。您做出的任何交易或其他财务决定均应完全由您负责,并且您不得依赖通过网站提供的任何信息。我们不对网站中的任何信息提供任何保证,并且对因使用网站中的任何信息而可能造成的任何交易损失不承担任何责任。
未经本站书面许可,禁止使用、存储、复制、展现、修改、传播或分发本网站所含数据。提供本网站所含数据的供应商及交易所保留其所有知识产权。


